



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


Match each of the following items with the appropriate description in applying the P.L. 86-272 definition of solicitation.
-Owning a tablet computer that is used on sales trips to the state.
(Multiple Choice)
4.8/5  (75)
(75) Match each of the following items with the appropriate description in determining whether sales/use tax typically must be collected.
-Fees paid to an accounting firm for the conduct of a financial audit.
(Multiple Choice)
5.0/5 (77)
(77) Typically, the state's payroll factor _________does/does not) include the salaries and bonuses paid to its corporate executives.
(Short Answer)
4.8/5 (82)
(82) When included in the property factor, leased property usually is valued at ______times its annual rental even though the taxpayer does not own the asset.
(Short Answer)
4.8/5 (63)
(63) Mercy Corporation, headquartered in State F, sells wireless computer devices, including keyboards and bar code readers. Mercy's degree of operations is sufficient to establish income tax nexus only in States E and F. Determine its sales factor in those states.
State E applies a throwback rule to sales, but State F does not. State G has not adopted an income tax to date. Mercy reported the following sales for the year. All of the goods were shipped from Mercy's F manufacturing facilities.

(Essay)
4.9/5 (65)
(65) Match each of the following items with the appropriate description in applying the P.L. 86-272 definition of solicitation.
-Training administrative personnel to use an update to ordering software.
(Multiple Choice)
4.7/5 (80)
(80) Trayne Corporation's sales office and manufacturing plant are located in State X. Trayne also maintains a manufacturing plant and sales office in State W. For purposes of apportionment, State X defines payroll as all compensation paid to employees, including elective contributions to § 401k) deferred compensation plans. Under the statutes of State W, neither compensation paid to officers nor contributions to § 401k) plans are included in the payroll factor. Trayne incurred the following personnel costs. 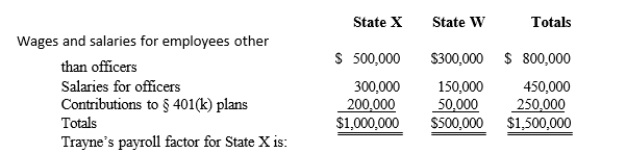
(Multiple Choice)
4.8/5 (80)
(80) A state can levy an income tax on a business only if the business was incorporated in the state.
(True/False)
4.7/5 (83)
(83) Politicians frequently use tax credits and exemptions to create economic development incentives.
(True/False)
4.8/5 (88)
(88) Under P.L. 86-272, the taxpayer is exempt from state taxes on income resulting from the mere solicitation of orders for the sale of stocks and bonds.
(True/False)
4.8/5 (80)
(80) Under common terminology, a unitary group files a _________combined/consolidated) state income tax return.
(Short Answer)
4.8/5 (82)
(82) Allocation is a method under which a corporation's _____________taxable income is directly assigned to the specific states where the income is derived.
(Short Answer)
4.8/5 (76)
(76) In determining state taxable income, all of the following are adjustments to Federal income except:
(Multiple Choice)
4.8/5 (85)
(85) In the apportionment formula, most states assign more than a one-third weight to the___________factor.
(Short Answer)
4.9/5 (61)
(61) Apportionment is a means by which a corporation's _________taxable income is divided among the states in which it conducts business.
(Short Answer)
4.9/5 (85)
(85) Typically exempt from the sales/use tax base is the purchase of tools by a manufacturer to make the widgets that it sells.
(True/False)
4.8/5 (69)
(69) The__________ tax usually is applied at the city or county level as its main source of revenue.
(Short Answer)
4.9/5 (89)
(89) Match each of the following events considered independently to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S. More than one choice may be correct.
-Q adopts a sales-only apportionment formula.
(Multiple Choice)
4.9/5 (88)
(88) Typically included in the sales/use tax base is the purchase of tablet computers and cell phone equipment by a large manufacturing firm whose sales force uses the items.
(True/False)
4.9/5 (65)
(65) Boot Corporation is subject to income tax in States A and B. Boot's operations generated $200,000 of apportionable income, and its sales and payroll activity and average property owned in each of the states is as follows: State A State B T otals Sales \ 200,000 \ 600,000 \ 800,000 Payroll 100,000 50,000 150,000 Property 200,000 50,000 250,000 How much more less) of Boot's income is subject to State A income tax if, instead of using an equally weighted three-factor apportionment formula, State A uses a formula with a double-weighted sales factor?
(Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)