



 Chat with AI
Exam 16: Multistate Corporate Taxation

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


Ramirez Corporation, which is subject to income tax only in State A, generated the following income and deductions: Federal taxable income \ 500,000 State A income tax expense 45,000 Depreciation allowed for Federal tax purposes 300,000 Depreciation allowed for state tax purposes 250,000 Federal taxable income is the starting point in computing A taxable income. State income taxes are not deductible for A tax purposes. Ramirez's A taxable income is:
(Multiple Choice)
5.0/5  (83)
(83) Typically exempt from the sales/use tax base is the purchase of prescription medicines by an individual.
(True/False)
4.9/5 (75)
(75) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following: State X State Z Totals Sales \ 1,500,000 \ 1,000,000 \ 2,500,000 Property 500,000 -0- 500,000 Payroll 2,000,000 -0- 2,000,000 Z utilizes a double-weighted sales factor in its three-factor apportionment formula. How much of José's taxable income is apportioned to Z?
(Multiple Choice)
4.9/5 (89)
(89) In conducting multistate tax planning, the taxpayer should:
(Multiple Choice)
4.9/5 (88)
(88) Match each of the following items with the appropriate description in determining whether sales/use tax typically must be collected.
-Computer equipment purchased by a charity.
(Multiple Choice)
4.9/5 (78)
(78) Hopper Corporation's property holdings in State E are as follows: Item Property Factor
Valuation $M)
Manufacturing equipment 100
Land held for potential appreciation 25
Manufacturing equipment that is not currently needed and sits idle 15
Manufacturing equipment that is not currently needed and is leased
To another taxpayer 20
Compute the numerator of Hopper's E property factor.
(Multiple Choice)
4.8/5 (79)
(79) Several states allow the S corporation to file an) ____________income tax return, usually in the form of a state-by-state spreadsheet, on behalf of its out-of-state shareholders.
(Short Answer)
4.9/5 (78)
(78) The property factor includes land and buildings used for business purposes.
(True/False)
4.9/5 (79)
(79) Most states exempt consumer purchases of groceries from the collection of the local sales tax.
(True/False)
4.9/5 (66)
(66) Roughly 5% of all taxes paid by businesses in the United States are to state, local, and municipal jurisdictions.
(True/False)
4.9/5 (84)
(84) A typical state taxable income addition modification is for the state's NOL allowed the taxpayer for the tax year.
(True/False)
4.8/5 (86)
(86) Pail Corporation is a merchandiser. It purchases overstock garments from various suppliers and sells the goods in its
State L retail store.
Sales to State L residents \ 600,000 Sales to homeless shelter operated by a local church 80,000 Sales to residents who cross the border from nearby State M 100,000 Sales to a similar merchandiser located in another State L town 20,000
Determine the total sales that are subject to the State L sales tax.
(Essay)
5.0/5 (84)
(84) Kim Corporation, a calendar year taxpayer, has manufacturing facilities in States A and B. A summary of Kim's property holdings follows:
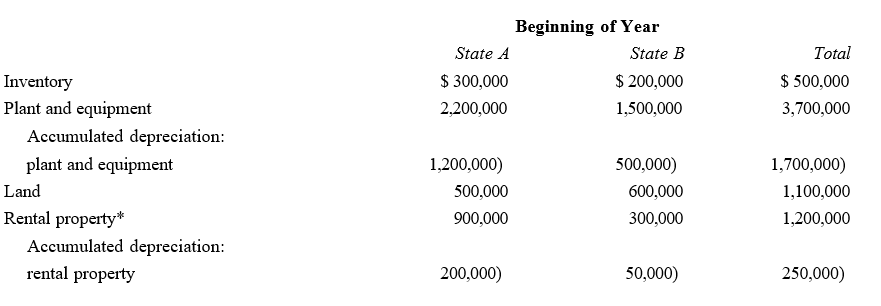 State A State B Total Inventory \ 400,000 \ 100,000 \ 500,000
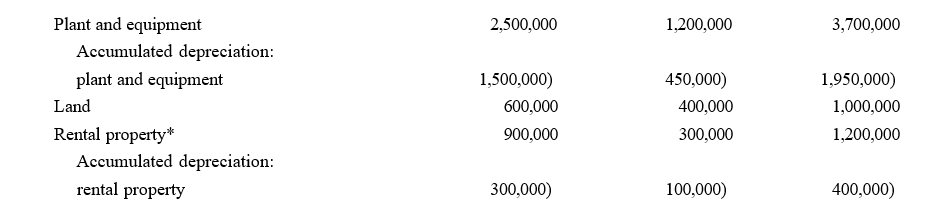 *Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. State A's statutes provide that the average historical cost of business property is to be included in the property factor. State B's statutes provide that the property factor is based on the average depreciated basis of in-state business property.
State A State B Total Inventory \ 400,000 \ 100,000 \ 500,000
*Unrelated to Kim's regular business and operations.
Determine Kim's property factors for the two states. State A's statutes provide that the average historical cost of business property is to be included in the property factor. State B's statutes provide that the property factor is based on the average depreciated basis of in-state business property. (Essay)
4.8/5 (62)
(62) When a _________________________ rule is in effect, out-of-state sales that are not subject to tax in the destination state are pulled back into the sales factor numerator of the origination state.
(Short Answer)
4.8/5 (61)
(61) Although apportionment formulas vary among jurisdictions, most states use the same three factors in the formula.The factors are____________________,____________________, and ____________________.
(Essay)
4.9/5 (84)
(84) Valdez Corporation, a calendar year taxpayer, owns property in States M and O. Both states require that the average value of assets be included in the property factor. State M requires that the property be valued at its historical cost, and State O requires that the property be included in the property factor at its net depreciated book value. 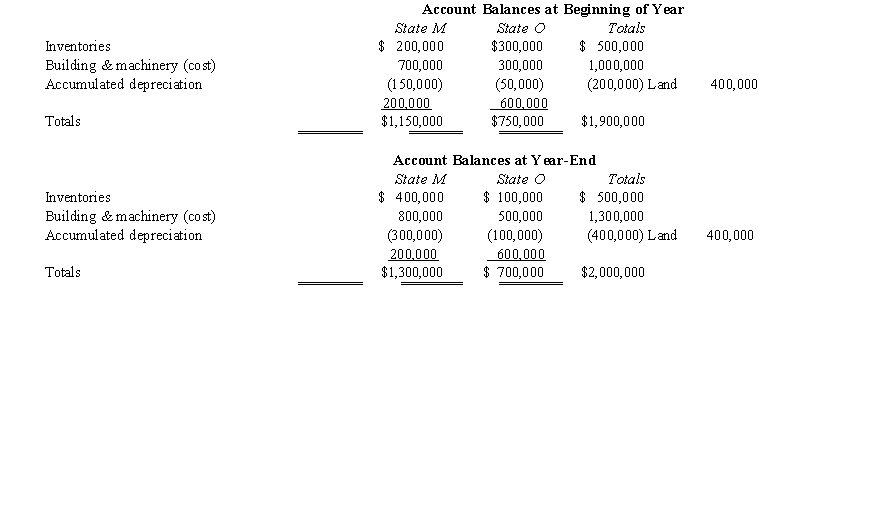 Valdez's O property factor is:
 (Multiple Choice)
4.8/5 (82)
(82) Marquardt Corporation realized $900,000 taxable income from the sales of its products in States X and Z. Marquardt's activities establish nexus for income tax purposes in both states. Marquardt's sales, payroll, and property among the states include the following: State X State Z Totals Sales \ 1,000,000 \ 3,000,000 \ 4,000,000 Property 2,000,000 -0- 2,000,000 Payroll 1,000,000 -0- 1,000,000 Z utilizes an equally weighted three-factor apportionment formula. Marquardt is incorporated in X. How much of
Marquardt's taxable income is apportioned to Z?
(Multiple Choice)
4.8/5 (75)
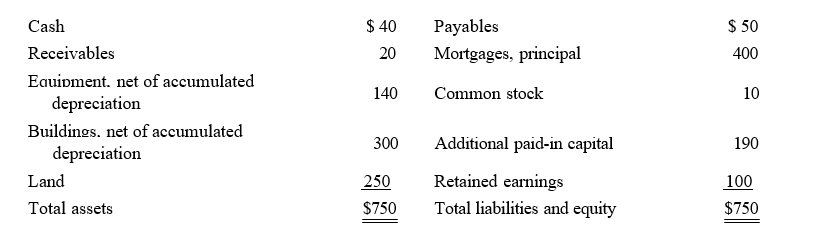
(75) Hambone Corporation is subject to the State E capital stock tax. The tax is levied at 2% of the entity's net worth that is apportioned to State E. Hambone conducts 30% of its operations in State E. Hambone's current book balance
sheet is as follows with amounts in millions. Compute Hambone's liability for the State E capital stock tax.
(Essay)
4.9/5 (84)
(84) All of the U.S. states use an apportionment formula based on the sales, property, and payroll factors.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)