



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


A table that shows the relationship between the price of a good and the quantity demanded of that good is called a
(Multiple Choice)
4.7/5  (74)
(74) Suppose roses are currently selling for $40 per dozen, but the equilibrium price of roses is $30 per dozen. We would expect a
(Multiple Choice)
4.8/5 (69)
(69) Figure 4-24
The diagram below pertains to the demand for turkey in the United States. 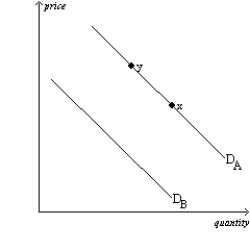 -Refer to Figure 4-24. All else equal, an increase in the productivity of turkey farmers would cause a move from
 (Multiple Choice)
4.9/5 (68)
(68) Table 4-14
The table below shows the quantities demanded of milk per month by four families at various prices. 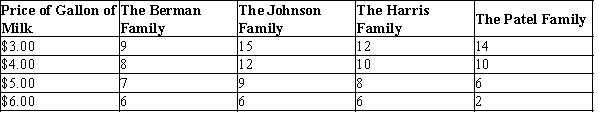 -Refer to Table 4-14. If the four families listed are the only demanders in this market and the price of a gallon of milk increases from $4.00 to $5.00, what is the change in the market quantity demanded?
 (Short Answer)
4.7/5 (87)
(87) In a competitive market, each seller has limited control over the price of his product because
(Multiple Choice)
4.9/5 (71)
(71) The equilibrium price is the same as the market-clearing price.
(True/False)
4.8/5 (82)
(82) Figure 4-30
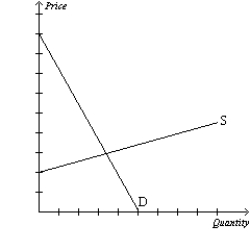 -Refer to Figure 4-30. In this market for iPhones, the technology improves while all other factors remain constant. Explain the change(s) in the equilibrium price and quantity.
 (Essay)
4.8/5 (80)
(80) If income rises in the market for an inferior good, will the demand curve for the inferior good shift to the right or to the left?
(Short Answer)
4.8/5 (82)
(82) Assume a market is perfectly competitive. When a new producer enters the market, the
(Multiple Choice)
4.8/5 (77)
(77) A market demand curve shows how the total quantity demanded of a good varies as
(Multiple Choice)
5.0/5 (78)
(78) Suppose the incomes of buyers in a market for a particular normal good decrease and there is also a reduction in input prices. What would we expect to occur in this market?
(Multiple Choice)
5.0/5 (78)
(78) Pens are normal goods. What will happen to the equilibrium price of pens if the price of pencils rises, consumers experience an increase in income, writing in ink becomes fashionable, people expect the price of pens to rise in the near future, the population increases, fewer firms manufacture pens, and the wages of pen-makers increase?
(Multiple Choice)
4.9/5 (75)
(75) Figure 4-20 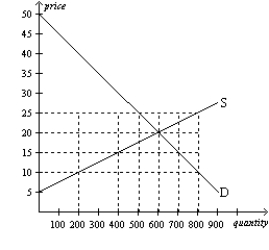 -Refer to Figure 4-20. If the price is $25, then there would be an excess
 (Multiple Choice)
4.8/5 (69)
(69) Which of these statements does not apply to market economies?
(Multiple Choice)
4.8/5 (64)
(64) Most studies indicate that tobacco and marijuana tend to be
(Multiple Choice)
4.9/5 (76)
(76) When the market price is above the equilibrium price, the quantity of the good demanded exceeds the quantity supplied.
(True/False)
4.7/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)