



 Chat with AI
Exam 16: Dilutive Securities and Earnings Per Share

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Grant, Inc. had 60,000 shares of treasury stock ($10 par value) at December 31, 2014, which it acquired at $11 per share. On June 4, 2015, Grant issued 30,000 treasury shares to employees who exercised options under Grant's employee stock option plan. The market value per share was $13 at December 31, 2014, $15 at June 4, 2015, and $18 at December 31, 2015. The stock options had been granted for $12 per share. The cost method is used. What is the balance of the treasury stock on Grant's balance sheet at December 31, 2015?
(Multiple Choice)
4.9/5  (92)
(92) On January 2, 2014, Farr Co. issued 10-year convertible bonds at 105. During 2014, these bonds were converted into common stock having an aggregate par value equal to the total face amount of the bonds. At conversion, the market price of Farr's common stock was 50 percent above its par value. On January 2, 2014, cash proceeds from the issuance of the convertible bonds should be reported as
(Multiple Choice)
4.9/5 (83)
(83) On April 7, 2014, Kegin Corporation sold a $4,000,000, twenty-year, 8 percent bond issue for $4,240,000. Each $1,000 bond has two detachable warrants, each of which permits the purchase of one share of the corporation's common stock for $30. The stock has a par value of $25 per share. Immediately after the sale of the bonds, the corporation's securities had the following market values: 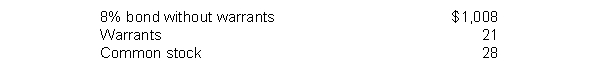 What accounts should Kegin credit to record the sale of the bonds?
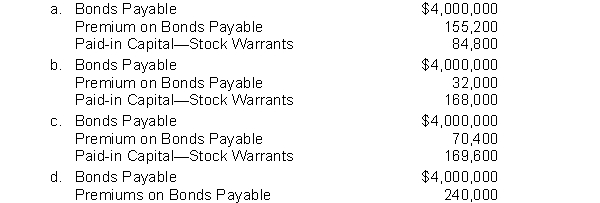
What accounts should Kegin credit to record the sale of the bonds? (Short Answer)
4.8/5 (72)
(72) In computing earnings per share, the equivalent number of shares of convertible preferred stock are added as an adjustment to the denominator (number of shares outstanding). If the preferred stock is cumulative, which amount should then be added as an adjustment to the numerator (net earnings)?
(Multiple Choice)
5.0/5 (80)
(80) On June 30, 2014, Yang Corporation granted compensatory stock options for 25,000 shares of its $24 par value common stock to certain of its key employees. The market price of the common stock on that date was $31 per share and the option price was $28. Using a fair value option pricing model, total compensation expense is determined to be $80,000. The options are exercisable beginning January 1, 2016, providing those key employees are still in the employ of the company at the time the options are exercised. The options expire on June 30, 2017.On January 4, 2016, when the market price of the stock was $36 per share, all options for the 25,000 shares were exercised. The service period is for two years beginning January 1, 2014. Using the fair value method, what should be the amount of compensation expense recorded by Yang Corporation for these options on December 31, 2014?
(Multiple Choice)
4.9/5 (76)
(76) A company should report per share amounts for income before extraordinary items, but not for income from continuing operations.
(True/False)
4.8/5 (72)
(72) Marsh Co. had 2,400,000 shares of common stock outstanding on January 1 and December 31, 2015. In connection with the acquisition of a subsidiary company in June 2014, Marsh is required to issue 100,000 additional shares of its common stock on July 1, 2016, to the former owners of the subsidiary. Marsh paid $100,000 in preferred stock dividends in 2015, and reported net income of $1,700,000 for the year. Marsh's diluted earnings per share for 2015 should be
(Multiple Choice)
4.8/5 (69)
(69) An executive pays no taxes at the time of exercise in a(an)
(Multiple Choice)
4.8/5 (82)
(82) At December 31, 2014, Emley Company had 1,200,000 shares of common stock outstanding. On October 1, 2015, an additional 400,000 shares of common stock were issued. In addition, Emley had $10,000,000 of 6% convertible bonds outstanding at December 31, 2014, which are convertible into 800,000 shares of common stock. No bonds were converted into common stock in 2015. The net income for the year ended December 31, 2015, was $3,750,000. Assuming the income tax rate was 30%, what should be the diluted earnings per share for the year ended December 31, 2015, rounded to the nearest penny?
(Multiple Choice)
4.8/5 (76)
(76) What effect will the acquisition of treasury stock have on stockholders' equity and earnings per share, respectively?
(Multiple Choice)
4.7/5 (64)
(64) When the cash proceeds from a bond issued with detachable stock warrants exceed the sum of the par value of the bonds and the fair market value of the warrants, the excess should be credited to
(Multiple Choice)
4.8/5 (68)
(68) Use the following information for questions 12 and 13
Florence Inc. issued 8,000, 5-year convertible bonds of $2,000 each for $4,000,000 at the beginning of 2012. The bonds have a stated rate of interest of 9% and interest is payable annually. Each bond can be convertible into 100 shares with a par value of $10. The market rate of similar nonconvertible debt is 10%.
-Determine the fair value of liability component using the "with-and-without" method.
(Multiple Choice)
4.9/5 (83)
(83) The following information is available for Barone Corporation: 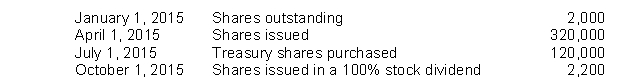 The number of shares to be used in computing earnings per common share for 2015 is
 (Multiple Choice)
5.0/5 (77)
(77) Companies recognize a gain or loss when stockholders exercise convertible preferred stock.
(True/False)
4.9/5 (81)
(81) Use the following information for questions 117 and 118.
Lerner Co. had 200,000 shares of common stock, 20,000 shares of convertible preferred stock, and $500,000 of 10% convertible bonds outstanding during 2015. The preferred stock is convertible into 40,000 shares of common stock. During 2015, Lerner paid dividends of $.45 per share on the common stock and $1.50 per share on the preferred stock. Each $1,000 bond is convertible into 45 shares of common stock. The net income for 2015 was $300,000 and the income tax rate was 30%.
-Basic earnings per share for 2015 is (rounded to the nearest penny)
(Multiple Choice)
4.8/5 (82)
(82) Use the following information for question 14 and 15
Swing High Inc. offers its 100 employees to participate in an employee share-purchase plan. Under the terms of plan, employees are entitled to purchase 10 shares at 10% discount. The par values of shares were $10. Overall, 60 employees accepted the offer and each employee purchased six shares. The market price on purchase date was $100.
-What is the compensation expense recorded by Swing High Inc.?
(Multiple Choice)
4.9/5 (77)
(77) Use the following information for questions 46 through 48.
Chang Corporation issued $4,000,000 of 9%, ten-year convertible bonds on July 1, 2014 at 96.1 plus accrued interest. The bonds were dated April 1, 2014 with interest payable April 1 and October 1. Bond discount is amortized semiannually on a straight-line basis. On April 1, 2015, $800,000 of these bonds were converted into 500 shares of $20 par value common stock. Accrued interest was paid in cash at the time of conversion.
-What should be the amount of the unamortized bond discount on April 1, 2015 relating to the bonds converted?
(Multiple Choice)
4.9/5 (75)
(75) During 2014, Gordon Company issued at 104 four hundred, $1,000 bonds due in ten years. One detachable stock warrant entitling the holder to purchase 15 shares of Gordon's common stock was attached to each bond. At the date of issuance, the market value of the bonds, without the stock warrants, was quoted at 96. The market value of each detachable warrant was quoted at $40. What amount, if any, of the proceeds from the issuance should be accounted for as part of Gordon's stockholders' equity?
(Multiple Choice)
4.8/5 (81)
(81) Use the following information for questions 59 and 60.
On May 1, 2014, Marly Co. issued $1,500,000 of 7% bonds at 103, which are due on April 30, 2024. Twenty detachable stock warrants entitling the holder to purchase for $40 one share of Marly's common stock, $15 par value, were attached to each $1,000 bond. The bonds without the warrants would sell at 96. On May 1, 2014, the fair value of Marly's common stock was $35 per share and of the warrants was $2.
-On May 1, 2014, Marly should record the bonds with a
(Multiple Choice)
4.9/5 (57)
(57) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)