



 Chat with AI
Exam 16: Dilutive Securities and Earnings Per Share

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Use the following information for questions 124 and 125.
Information concerning the capital structure of Piper Corporation is as follows: 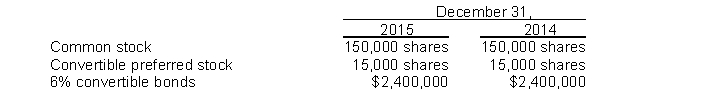 During 2015, Piper paid dividends of $0.60 per share on its common stock and $1.50 per share on its preferred stock. The preferred stock is convertible into 30,000 shares of common stock. The 6% convertible bonds are convertible into 75,000 shares of common stock. The net income for the year ended December 31, 2015, was $300,000. Assume that the income tax rate was 30%.
-What should be the basic earnings per share for the year ended December 31, 2015, rounded to the nearest penny?
During 2015, Piper paid dividends of $0.60 per share on its common stock and $1.50 per share on its preferred stock. The preferred stock is convertible into 30,000 shares of common stock. The 6% convertible bonds are convertible into 75,000 shares of common stock. The net income for the year ended December 31, 2015, was $300,000. Assume that the income tax rate was 30%.
-What should be the basic earnings per share for the year ended December 31, 2015, rounded to the nearest penny? (Multiple Choice)
4.7/5  (76)
(76) Beaty Inc. purchased Dunbar Co. and agreed to give stockholders of Dunbar Co. 10,000 additional shares in 2016 if Dunbar Co.'s net income in 2015 is $500,000; in 2014 Dunbar Co.'s net income is $520,000. Beaty Inc. has net income for 2014 of $400,000 and has an average number of common shares outstanding for 2014 of 100,000 shares. What should Beaty report as diluted earnings per share for 2014?
(Multiple Choice)
4.7/5 (84)
(84) The date on which to measure the compensation element in a stock option granted to a corporate employee ordinarily is the date on which the employee
(Multiple Choice)
4.8/5 (74)
(74) On January 1, 2015, Evans Company granted Tim Telfer, an employee, an option to buy 3,000 shares of Evans Co. stock for $25 per share, the option exercisable for 5 years from date of grant. Using a fair value option pricing model, total compensation expense is determined to be $22,500. Telfer exercised his option on September 1, 2015, and sold his 1,000 shares on December 1, 2015. Quoted market prices of Evans Co. stock during 2015 were 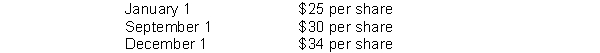 The service period is for three years beginning January 1, 2015. As a result of the option granted to Telfer, using the fair value method, Evans should recognize compensation expense for 2015 on its books in the amount of
 (Multiple Choice)
4.7/5 (89)
(89) At December 31, 2014 Rice Company had 300,000 shares of common stock and 10,000 shares of 8%, $100 par value cumulative preferred stock outstanding. No dividends were declared on either the preferred or common stock in 2014 or 2015. On January 30, 2016, prior to the issuance of its financial statements for the year ended December 31, 2015, Rice declared a 100% stock dividend on its common stock. Net income for 2015 was $1,520,000. In its 2015 financial statements, Rice's 2015 earnings per common share should be
(Multiple Choice)
4.9/5 (88)
(88) The service period in stock option plans is the time between the grant date and the vesting date.
(True/False)
4.8/5 (86)
(86) Terry Corporation had 480,000 shares of common stock outstanding at December 31, 2014. In addition, it had 90,000 stock options outstanding, which had been granted to certain executives, and which gave them the right to purchase shares of Terry's stock at an option price of $37 per share. The average market price of Terry's common stock for 2014 was $50. What is the number of shares that should be used in computing diluted earnings per share for the year ended December 31, 2014?
(Multiple Choice)
4.8/5 (71)
(71) Use the following information for questions 59 and 60.
On May 1, 2014, Marly Co. issued $1,500,000 of 7% bonds at 103, which are due on April 30, 2024. Twenty detachable stock warrants entitling the holder to purchase for $40 one share of Marly's common stock, $15 par value, were attached to each $1,000 bond. The bonds without the warrants would sell at 96. On May 1, 2014, the fair value of Marly's common stock was $35 per share and of the warrants was $2.
-On May 1, 2014, Marly should credit Paid-in Capital from Stock Warrants for
(Multiple Choice)
4.7/5 (84)
(84) Warrants exercisable at $20 each to obtain 60,000 shares of common stock were outstanding during a period when the average market price of the common stock was $25. Application of the treasury stock method for the assumed exercise of these warrants in computing diluted earnings per share will increase the weighted average number of outstanding shares by
(Multiple Choice)
5.0/5 (76)
(76) When a company has a complex capital structure, it must report both basic and diluted earnings per share.
(True/False)
4.9/5 (79)
(79) Which of the following is not a characteristic of a noncompensatory stock option plan?
(Multiple Choice)
4.9/5 (72)
(72) If preferred stock is cumulative and no dividends are declared, the company subtracts the current year preferred dividend in computing earnings per share.
(True/False)
4.7/5 (80)
(80) Companies recognize the gain or loss on retiring convertible debt as an extraordinary item.
(True/False)
4.9/5 (74)
(74) On January 1, 2013, Orr Co. established a stock appreciation rights plan for its executives. They could receive cash at any time during the next four years equal to the difference between the market price of the common stock and a preestablished price of $16 on 400,000 SARs. The market price is as follows: 12/31/13-$21; 12/31/14-$18; 12/31/15-$19; 12/31/16-$20. On December 31, 2015, 65,000 SARs are exercised, and the remaining SARs are exercised on December 31, 2016.
Instructions
(a) Prepare a schedule that shows the amount of compensation expense for each of the four years starting with 2013.
(b) Prepare the journal entry at 12/31/14 to record compensation expense.
(c) Prepare the journal entry at 12/31/16 to record the exercise of the remaining SARs.
(Essay)
4.7/5 (87)
(87) A company uses income from continuing operations to determine whether potential common stock is dilutive or antidilutive, and this is referred to as
(Multiple Choice)
4.9/5 (89)
(89) Morgan Corporation had two issues of securities outstanding: common stock and an 8% convertible bond issue in the face amount of $12,000,000. Interest payment dates of the bond issue are June 30th and December 31st. The conversion clause in the bond indenture entitles the bondholders to receive forty shares of $20 par value common stock in exchange for each $1,000 bond. On June 30, 2014, the holders of $1,800,000 face value bonds exercised the conversion privilege. The market price of the bonds on that date was $1,100 per bond and the market price of the common stock was $35. The total unamortized bond discount at the date of conversion was $750,000. In applying the book value method, what amount should Morgan credit to the account "paid-in capital in excess of par," as a result of this conversion?
(Multiple Choice)
4.9/5 (73)
(73) Nolte Co. has 4,500,000 shares of common stock outstanding on December 31, 2014. An additional 200,000 shares are issued on April 1, 2015, and 480,000 more on September 1. On October 1, Nolte issued $6,000,000 of 9% convertible bonds. Each $1,000 bond is convertible into 40 shares of common stock. No bonds have been converted. The number of shares to be used in computing basic earnings per share and diluted earnings per share on December 31, 2015 is
(Multiple Choice)
4.9/5 (89)
(89) issued $4,000,000 of 12%, 5-year convertible bonds on December 1, 2014 for $4,016,900 plus accrued interest. The bonds were dated April 1, 2014 with interest payableApril 1 and October 1. Bond premium is amortized each interest period on a straight-line basis. Garr Co. has a fiscal year end of September 30.On October 1, 2015, $2,000,000 of these bonds were converted into 28,000 shares of $15 par common stock. Accrued interest was paid in cash at the time of conversion.
Instructions
(a) Prepare the entry to record the interest expense at April 1, 2015. Assume that interest payable was credited when the bonds were issued (round to nearest dollar).
(b) Prepare the entry to record the conversion on October 1, 2015. Assume that the entry to record amortization of the bond premium and interest payment has been made.
(Essay)
4.9/5 (79)
(79) Assume that the following data relative to Kane Company for 2015 is available: 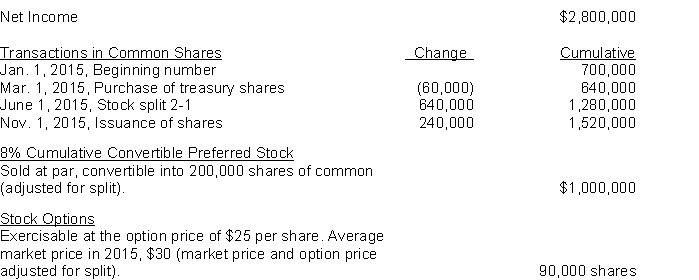 Instructions
(a) Compute the basic earnings per share for 2015. (Round to the nearest penny.)(b) Compute the diluted earnings per share for 2015. (Round to the nearest penny.)
Instructions
(a) Compute the basic earnings per share for 2015. (Round to the nearest penny.)(b) Compute the diluted earnings per share for 2015. (Round to the nearest penny.) (Essay)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)