



 Chat with AI
Exam 20: Accounting for Pensions and Postretirement Benefits

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Seigel Co. maintains a defined-benefit pension plan for its employees. At each balance sheet date, Yeager should report a pension asset / liability equal to the

Free
(Multiple Choice)
4.9/5  (96)
(96) Correct Answer: Verified
D
The Pension Asset / Liability account balance equals the difference between the projected benefit obligation and the fair value of pension plan assets.
Free
(True/False)
4.9/5 (75)
(75) Correct Answer:Verified
VerifiedTrue
Use the following information for questions 80 through 84.
The following information relates to the pension plan for the employees of Turner Co.: 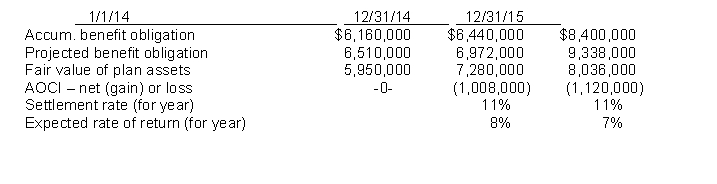 Turner estimates that the average remaining service life is 16 years. Turner's contribution was $882,000 in 2015 and benefits paid were $658,000.
-The actual return on plan assets in 2015 is
Turner estimates that the average remaining service life is 16 years. Turner's contribution was $882,000 in 2015 and benefits paid were $658,000.
-The actual return on plan assets in 2015 isFree
(Multiple Choice)
4.8/5 (90)
(90) Correct Answer:Verified
VerifiedB
On January 1, 2015, McGee Co. had the following balances: Projected benefit obligation \ 7,400,000 Fair value of plan assets 7,400,000 Other data related to the pension plan for 2015: Service cost 315,000 Contributions to the plan 459,000 Benefits paid 450,000 Actual return on plan assets 444,000 Settlement rate 9\% Expected rate of return 6\%
Instructions
(a) Determine the projected benefit obligation at December 31, 2015. There are no net gains or losses.
(b) Determine the fair value of plan assets at December 31, 2015.
(c) Calculate pension expense for 2015.(d) Prepare the journal entry to record pension expense and the contributions for 2015.
(Essay)
4.9/5 (76)
(76) Which of the following items should be included in pension expense calculated by an employer who sponsors a defined-benefit pension plan for its employees? 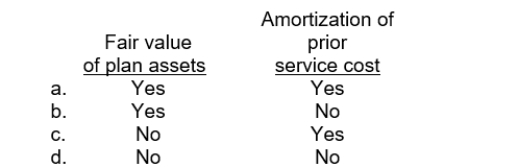
(Short Answer)
4.9/5 (75)
(75) The accumulated benefit obligation bases the deferred compensation amount on both vested and nonvested service using future salary levels.
(True/False)
4.9/5 (85)
(85) Presented below is information related to the pension plan of Zimmer Inc. for the year 2015.
1. The service cost related to pension expense is $240,000 using the projected benefits approach.
2. The projected benefit obligation and the accumulated benefit obligation at the beginning of the year are $320,000 and $280,000, respectively. The expected return on plan assets is 9% and the settlement rate is 10%.
3. The accumulated OCI - prior service cost at the beginning of the year is $140,000. The company has a workforce of 200 employees, all who are expected to receive benefits under the plan. The total number of service-years is 1,000 and the service-years attributable to 2015 is 200. The company has decided to use the years-of-service method of amortization for these costs.
4. At the beginning of the period, fair value of pension plan assets, $280,000. The company had an Accumulated OCI (loss) at the beginning of the period of $90,000. Any amortization of unrecognized net loss is recognized on a straight-line basis over the average remaining service-life of the employees."
5. The contribution made to the pension fund in 2015 was $229,000.
Instructions
(a) Determine the pension expense to be reported on the income statement for 2015. (Round all computations to nearest dollar.)
(b) Prepare the journal entry(ies) to record pension expense for 2015."
(Essay)
4.8/5 (72)
(72) Miles Co. had the following selected balances at December 31, 2015: Projected benefit obligation \ 4,650,000 Accumulated benefit obligation 4,550,000 Fair value of plan assets 4,340,000 Accumulated OCl (PSC) 170,000
InstructionsCalculate the pension asset / liability to be recorded at December 31, 2015.
(Essay)
5.0/5 (79)
(79) Presented below is pension information related to Waters Company as of December 31, 2015: Accumulated benefit obligation \ 3,000,000 Projected benefit obligation 3,500,000 Plan assets (at fair value) 3,750,000 Accumulated (/) 100,000 The amount to be reported as Pension Asset / Liability as of December 31, 2015 is
(Multiple Choice)
4.8/5 (89)
(89) According to the FASB, recognition of a liability is required when the projected benefit obligation exceeds the fair value of plan assets. Conversely, when the fair value of plan assets exceeds the projected benefit obligation, the Board
(Multiple Choice)
4.9/5 (83)
(83) Which of the following is recognized in the accounts and in the financial statements?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following disclosures of pension plan information would not normally be required?
(Multiple Choice)
4.8/5 (79)
(79) Gibbs Company has 200 employees who are expected to receive benefits under the company's defined-benefit pension plan. The total number of service-years of these employees is 2,000. The actuary for the company's pension plan calculated the following net gains and losses: 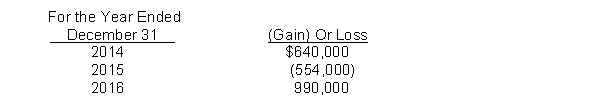 Prior to 2014, there was no unrecognized net gain or loss.Information about the company's projected benefit obligation and market-related (and fair) value of plan assets follows:
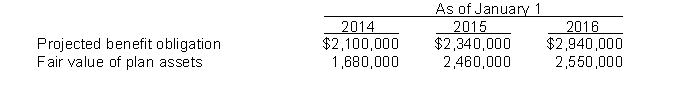 InstructionsBased on the above information about Gibbs Company, prepare a schedule which reflects the amount of net gain or loss to be amortized by the company as a component of pension expense for the years 2014, 2015, and 2016. The company amortizes net gains or losses using the straight-line method over the average service life of participating employees.
Prior to 2014, there was no unrecognized net gain or loss.Information about the company's projected benefit obligation and market-related (and fair) value of plan assets follows:
InstructionsBased on the above information about Gibbs Company, prepare a schedule which reflects the amount of net gain or loss to be amortized by the company as a component of pension expense for the years 2014, 2015, and 2016. The company amortizes net gains or losses using the straight-line method over the average service life of participating employees. (Essay)
4.8/5 (89)
(89) A corporation has a defined-benefit plan. A pension liability will result at the end of the year if the
(Multiple Choice)
4.7/5 (90)
(90) Use the following information for questions 93 and 94.
On January 1, 2015, Parks Co. has the following balances:  The settlement rate is 10%. Other data related to the pension plan for 2015 are: Service cost \ 240,000 Amortization of prior service costs 54,000 Contributions 270,000 Benefits paid 250,000 Actual return on plan assets 264,000 Amortization of net gain 18,000
-The balance of the projected benefit obligation at December 31, 2015 is
The settlement rate is 10%. Other data related to the pension plan for 2015 are: Service cost \ 240,000 Amortization of prior service costs 54,000 Contributions 270,000 Benefits paid 250,000 Actual return on plan assets 264,000 Amortization of net gain 18,000
-The balance of the projected benefit obligation at December 31, 2015 is (Multiple Choice)
4.8/5 (76)
(76) Midland Company follows U.S. GAAP for its external financial reporting whereas Bailey Company follows IFRS for its external financial reporting. The remaining service lives of employees at both firms is estimated to be 10 years. The following information is available for each company at December 31, 2015 related to their respective defined-benefit pension plans. 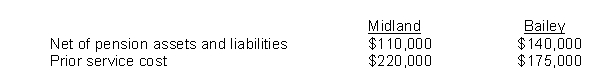 What is the amount of Pension Asset/Liability recognized by each company in its balance sheet at December 31, 2015?
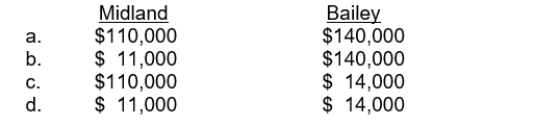
What is the amount of Pension Asset/Liability recognized by each company in its balance sheet at December 31, 2015? (Short Answer)
4.9/5 (65)
(65) Differing measures of the pension obligation can be based on
(Multiple Choice)
4.8/5 (76)
(76) The following information is related to the Stone Co. postretirement benefits plan for 2015: Service cost \ 163,000 Discount rate 10\% EPBO, January 1, 2015 820,000 APBO, January 1, 2015 660,000 Actual return on plan assets in 2015 22,400 Expected return on plan assets in 2015 29,000 Contributions (funding) 224,000
Instructions
(a) Compute the amount of postretirement expense for 2015. (Show computations.)(b) Prepare the journal entry to record postretirement expense and Stone's contributions for 2015.
(Essay)
4.9/5 (74)
(74) Which of the following statements about the expected postretirement benefit obligation (EPBO) is not correct?
(Multiple Choice)
4.8/5 (79)
(79) The difference between the expected return and the actual return is referred to as the unexpected gain or loss.
(True/False)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)