



 Chat with AI
Exam 16: Dilutive Securities and Earnings Per Share

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Use the following information for questions 75 through 77.
On January 1, 2014, Korsak, Inc. established a stock appreciation rights plan for its executives. It entitled them to receive cash at any time during the next four years for the difference between the market price of its common stock and a pre-established price of $20 on 100,000 SARs. Current market prices of the stock are as follows: 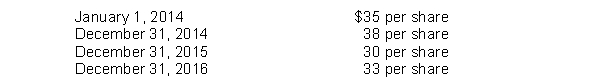 Compensation expense relating to the plan is to be recorded over a four-year period beginning January 1, 2014.
-On December 31, 2016, 25,000 SARs are exercised by executives. What amount of compensation expense should Korsak recognize for the year ended December 31, 2016?
Compensation expense relating to the plan is to be recorded over a four-year period beginning January 1, 2014.
-On December 31, 2016, 25,000 SARs are exercised by executives. What amount of compensation expense should Korsak recognize for the year ended December 31, 2016?
Free
(Multiple Choice)
4.9/5  (96)
(96) Correct Answer: Verified
A
In computations of weighted average of shares outstanding, when a stock dividend or stock split occurs, the additional shares are
Free
(Multiple Choice)
4.7/5 (68)
(68) Correct Answer:Verified
VerifiedD
The distribution of stock rights to existing common stockholders will increase paid-in capital at the 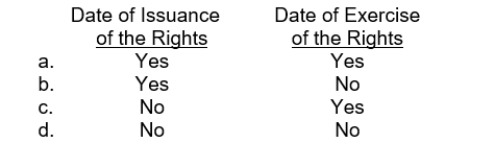
(Short Answer)
4.9/5 (82)
(82) Use the following information for questions 12 and 13
Florence Inc. issued 8,000, 5-year convertible bonds of $2,000 each for $4,000,000 at the beginning of 2012. The bonds have a stated rate of interest of 9% and interest is payable annually. Each bond can be convertible into 100 shares with a par value of $10. The market rate of similar nonconvertible debt is 10%.
-Determine the fair value of equity component using the "with-and-without" method.
(Multiple Choice)
4.9/5 (76)
(76) Use the following information for questions 55 and 56.
On May 1, 2014, Payne Co. issued $900,000 of 7% bonds at 103, which are due on April 30, 2024. Twenty detachable stock warrants entitling the holder to purchase for $40 one share of Payne's common stock, $15 par value, were attached to each $1,000 bond. The bonds without the warrants would sell at 96. On May 1, 2014, the fair value of Payne's common stock was $35 per share and of the warrants was $2.
-On May 1, 2014, Payne should record the bonds with a
(Multiple Choice)
5.0/5 (71)
(71) Foyle, Inc., had 680,000 shares of common stock issued and outstanding at December 31, 2014. On July 1, 2015, an additional 40,000 shares of common stock were issued for cash. Foyle also had unexercised stock options to purchase 32,000 shares of common stock at $15 per share outstanding at the beginning and end of 2015. The average market price of Foyle's common stock was $20 during 2015. What is the number of shares that should be used in computing diluted earnings per share for the year endedDecember 31, 2015?
(Multiple Choice)
4.9/5 (86)
(86) Weiser Corp. on January 1, 2012, granted stock options for 40,000 shares of its $10 par value common stock to its key employees. The market price of the common stock on that date was $23 per share and the option price was $20. The Black-Scholes option pricing model determines total compensation expense to be $420,000. The options are exercisable beginning January 1, 2015, provided those key employees are still in Weiser's employ at the time the options are exercised. The options expire on January 1, 2016.On January 1, 2015, when the market price of the stock was $29 per share, all 40,000 options were exercised. The amount of compensation expense Weiser should record for 2015 under the fair value method is
(Multiple Choice)
4.8/5 (76)
(76) On December 1, 2014, Lester Company issued at 103, five hundred of its 9%, $1,000 bonds. Attached to each bond was one detachable stock warrant entitling the holder to purchase 10 shares of Lester's common stock. On December 1, 2014, the market value of the bonds, without the stock warrants, was 95, and the market value of each stock purchase warrant was $50. The amount of the proceeds from the issuance that should be accounted for as the initial carrying value of the bonds payable would be
(Multiple Choice)
4.8/5 (86)
(86) If an employee fails to exercise a stock option before its expiration date, the company should decrease compensation expense.
(True/False)
4.9/5 (76)
(76) (Essay)Define the following:(a) The computation of earnings per common share(b) Complex capital structure(c) Basic earnings per share(d) Diluted earnings per share
(Essay)
4.9/5 (72)
(72) Prepare the necessary entries from 1/1/14-2/1/16 for the following events using the fair value method. If no entry is needed, write "No Entry Necessary."1. On 1/1/14, the stockholders adopted a stock option plan for top executives whereby each might receive rights to purchase up to 18,000 shares of common stock at $40 per share. The par value is $10 per share.2. On 2/1/14, options were granted to each of five executives to purchase 18,000 shares. The options were non-transferable and the executive had to remain an employee of the company to exercise the option. The options expire on 2/1/16. It is assumed that the options were for services performed equally in 2014 and 2015. The Black-Scholes option pricing model determines total compensation expense to be $1,900,000.3. At 2/1/16, four executives exercised their options. The fifth executive chose not to exercise his options, which therefore were forfeited.
(Essay)
4.8/5 (79)
(79) Under IFRS, employee share-purchase plans must be recorded as an expense in the year it was issued by a company.
(True/False)
4.8/5 (85)
(85) Compensation expense resulting from a compensatory stock option plan is generally
(Multiple Choice)
4.9/5 (69)
(69) On December 31, 2014, Kessler Company granted some of its executives options to purchase 45,000 shares of the company's $10 par common stock at an option price of $50 per share. The options become exercisable on January 1, 2015, and represent compensation for executives' services over a three-year period beginning January 1, 2015. The Black-Scholes option pricing model determines total compensation expense to be $270,000. At December 31, 2015, none of the executives had exercised their options. What is the impact on Kessler's net income for the year ended December 31, 2015 as a result of this transaction under the fair value method?
(Multiple Choice)
4.7/5 (77)
(77) Which of the following is not a characteristic of a noncompensatory stock purchase plan?
(Multiple Choice)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)