



 Chat with AI
Exam 16: Dilutive Securities and Earnings Per Share

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Dilutive convertible securities must be used in the computation of
(Multiple Choice)
4.9/5  (74)
(74) When computing diluted earnings per share, convertible bonds are
(Multiple Choice)
4.9/5 (88)
(88) In order to retain certain key executives, Smiley Corporation granted them incentive stock options on December 31, 2013. 120,000 options were granted at an option price of $35per share. Market prices of the stock were as follows: 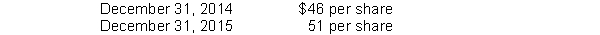 The options were granted as compensation for executives' services to be rendered over a two-year period beginning January 1, 2014. The Black-Scholes option pricing model determines total compensation expense to be $1,200,000. What amount of compensation expense should Smiley recognize as a result of this plan for the year ended December 31, 2014 under the fair value method?
 (Multiple Choice)
4.8/5 (91)
(91) At December 31, 2015 and 2014, Miley Corp. had 180,000 shares of common stock and 10,000 shares of 6%, $100 par value cumulative preferred stock outstanding. No dividends were declared on either the preferred or common stock in 2015 or 2014. Net income for 2015 was $375,000. For 2015, earnings per common share amounted to
(Multiple Choice)
4.8/5 (74)
(74) For stock appreciation rights, the measurement date for computing compensation is the date
(Multiple Choice)
4.8/5 (78)
(78) In 2014, Eklund, Inc., issued for $103 per share, 70,000 shares of $100 par value convertible preferred stock. One share of preferred stock can be converted into three shares of Eklund's $25 par value common stock at the option of the preferred stockholder. In August 2015, all of the preferred stock was converted into common stock. The market value of the common stock at the date of the conversion was $30 per share. What total amount should be credited to additional paid-in capital from common stock as a result of the conversion of the preferred stock into common stock?
(Multiple Choice)
4.9/5 (83)
(83) A company should allocate the proceeds from the sale of debt with detachable stock warrants between the two securities based on their market values.
(True/False)
4.8/5 (78)
(78) On January 1, 2015, Gridley Corporation had 250,000 shares of its $2 par value common stock outstanding. On March 1, Gridley sold an additional 500,000 shares on the open market at $20 per share. Gridley issued a 20% stock dividend on May 1. On August 1, Gridley purchased 280,000 shares and immediately retired the stock. On November 1, 400,000 shares were sold for $25 per share. What is the weighted-average number of shares outstanding for 2015?
(Multiple Choice)
4.8/5 (75)
(75) Fultz Company had 300,000 shares of common stock issued and outstanding at December 31, 2014. During 2015, no additional common stock was issued. On January 1, 2015, Fultz issued 400,000 shares of nonconvertible preferred stock. During 2015, Fultz declared and paid $150,000 cash dividends on the common stock and $125,000 on the nonconvertible preferred stock. Net income for the year ended December 31, 2015, was $800,000. What should be Fultz's 2015 earnings per common share, rounded to the nearest penny?
(Multiple Choice)
4.8/5 (80)
(80) The market value method is used to account for the exercise of convertible preferred stock.
(True/False)
4.8/5 (74)
(74) On January 1, 2014, Sharp Corp. granted an employee an option to purchase 12,000 shares of Sharp's $5 par value common stock at $20 per share. The Black-Scholes option pricing model determines total compensation expense to be $280,000. The option became exercisable on December 31, 2015, after the employee completed two years of service. The market prices of Sharp's stock were as follows:  For 2015, should recognize compensation expense under the fair value method of
 (Multiple Choice)
4.9/5 (86)
(86) In a contingent issue agreement, the contingent shares are considered outstanding for computing diluted EPS when the earnings or market price level is met by the end of the year.
(True/False)
4.8/5 (80)
(80) Use the following information for questions 46 through 48.
Chang Corporation issued $4,000,000 of 9%, ten-year convertible bonds on July 1, 2014 at 96.1 plus accrued interest. The bonds were dated April 1, 2014 with interest payable April 1 and October 1. Bond discount is amortized semiannually on a straight-line basis. On April 1, 2015, $800,000 of these bonds were converted into 500 shares of $20 par value common stock. Accrued interest was paid in cash at the time of conversion.
-What was the effective interest rate on the bonds when they were issued?
(Multiple Choice)
5.0/5 (77)
(77) On January 2, 2014, Perez Co. issued at par $10,000 of 8% bonds convertible in total into 1,000 shares of Perez's common stock. No bonds were converted during 2014. Throughout 2014, Perez had 1,000 shares of common stock outstanding. Perez's 2014 net income was $6,000, and its income tax rate is 30%. No potentially dilutive securities other than the convertible bonds were outstanding during 2014. Perez's diluted earnings per share for 2014 would be (rounded to the nearest penny)
(Multiple Choice)
5.0/5 (78)
(78) Under IFRS, convertible bonds are "bifurcated" -separated into the equity component (the value of the conversion option) of the bond issue and the debt component.
(True/False)
4.8/5 (79)
(79) With respect to the computation of earnings per share, which of the following would be most indicative of a simple capital structure?
(Multiple Choice)
4.8/5 (75)
(75) If a stock dividend occurs after year-end, but before issuing the financial statements, a company must restate the weighted-average number of shares outstanding for the year.
(True/False)
4.8/5 (79)
(79) Corporations issue convertible debt for two main reasons. One is the desire to raise equity capital that, assuming conversion, will arise when the original debt is converted. The other is
(Multiple Choice)
4.8/5 (86)
(86) Use the following information for questions 124 and 125.
Information concerning the capital structure of Piper Corporation is as follows: 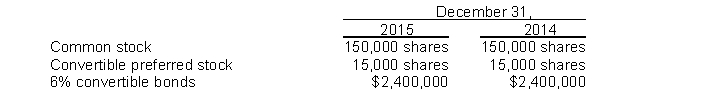 During 2015, Piper paid dividends of $0.60 per share on its common stock and $1.50 per share on its preferred stock. The preferred stock is convertible into 30,000 shares of common stock. The 6% convertible bonds are convertible into 75,000 shares of common stock. The net income for the year ended December 31, 2015, was $300,000. Assume that the income tax rate was 30%.
-What should be the diluted earnings per share for the year ended December 31, 2015, rounded to the nearest penny?
During 2015, Piper paid dividends of $0.60 per share on its common stock and $1.50 per share on its preferred stock. The preferred stock is convertible into 30,000 shares of common stock. The 6% convertible bonds are convertible into 75,000 shares of common stock. The net income for the year ended December 31, 2015, was $300,000. Assume that the income tax rate was 30%.
-What should be the diluted earnings per share for the year ended December 31, 2015, rounded to the nearest penny? (Multiple Choice)
5.0/5 (62)
(62) Use the following information for questions 46 through 48.
Chang Corporation issued $4,000,000 of 9%, ten-year convertible bonds on July 1, 2014 at 96.1 plus accrued interest. The bonds were dated April 1, 2014 with interest payable April 1 and October 1. Bond discount is amortized semiannually on a straight-line basis. On April 1, 2015, $800,000 of these bonds were converted into 500 shares of $20 par value common stock. Accrued interest was paid in cash at the time of conversion.
-If "interest payable" were credited when the bonds were issued, what should be the amount of the debit to "interest expense" on October 1, 2014?
(Multiple Choice)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)