



 Chat with AI
Exam 20: Accounting for Pensions and Postretirement Benefits

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


The following pension plan information is for Farr Company at December 31, 2015. Projected benefit obligation \ 8,500,000 Accumulated benefit obligation 7,500,000 Plan assets (at fair value) 6,150,000 Accumulated OCl (PSC) 540,000 Pension expense for 2015 3,000,000 Contribution for 2015 2,400,000 The amount to be reported as the liability for pensions on the December 31, 2015 balance sheet is
(Multiple Choice)
4.9/5  (87)
(87) Presented below is pension information related to Woods, Inc. for the year 2015: Service cost \ 82,000 Interest on projected benefit obligation 54,000 Interest on vested benefits 24,000 Amortization of prior service cost due to increase in benefits 12,000 Expected return on plan assets 18,000 The amount of pension expense to be reported for 2015 is
(Multiple Choice)
4.8/5 (90)
(90) Qualified pension plans permit deductibility of the employer's contributions to the pension fund.
(True/False)
4.9/5 (88)
(88) The following information pertains to Hopson Co.'s pension plan: Actuarial estimate of projected benefit obligation at 1/1/15 \ 72,000 Assumed discount rate 10\% Service costs for 2015 \ 28,000 Pension benefits paid during 2015 \ 15,000 If no change in actuarial estimates occurred during 2015, Hopson's projected benefit obligation at December 31, 2015 was
(Multiple Choice)
5.0/5 (69)
(69) Midland Company follows U.S. GAAP for its external financial reporting whereas Bailey Company follows IFRS for its external financial reporting. The amount contributed by Midland for its defined contribution plan for 2015 amounted to $55,000 and the amount contributed by Bailey for its defined contribution plan for 2015 amounted to $76,000. The remaining service lives of employees at both firms is estimated to be 10 years. What is the amount of expense related to pension costs recognized by each company in its income statement for the year ended December 31, 2015? 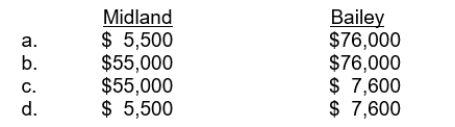
(Short Answer)
4.9/5 (91)
(91) Use the following information for questions 68 through 70.
The following information for Cooper Enterprises is given below: 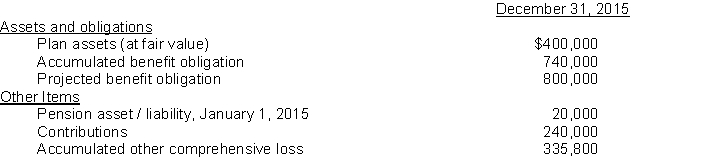 There were no actuarial gains or losses at January 1, 2015. The average remaining service life of employees is 10 years.
-The amortization of Other Comprehensive Loss for 2016 is:
There were no actuarial gains or losses at January 1, 2015. The average remaining service life of employees is 10 years.
-The amortization of Other Comprehensive Loss for 2016 is: (Multiple Choice)
4.9/5 (83)
(83) Prior service cost is amortized into income over the expected service lives of employees under both U.S. GAAP and IFRS.
(True/False)
4.8/5 (74)
(74) Which of the following is true with regard to pension accounting under U.S. GAAP and IFRS?
(Multiple Choice)
4.7/5 (81)
(81) Briefly explain the following terms:(a) Service cost(b) Interest cost(c) Prior service cost(d) Vested benefits
(Essay)
4.8/5 (77)
(77) The actuarial gains or losses that result from changes in the projected benefit obligation are called 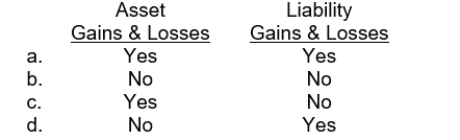
(Short Answer)
4.8/5 (75)
(75) Companies should recognize the entire increase in projected benefit obligation due to a plan initiation or amendment as pension expense in the year of amendment.
(True/False)
4.9/5 (88)
(88) When a company amends its defined benefit plan, and recognizes prior service, the projected benefit obligation is increased to recognize this additional liability.
(True/False)
4.9/5 (92)
(92) Companies must disclose a reconciliation of how the projected benefit obligation and the fair value of plan assets changed during the year either in their financial statements or in the notes.
(True/False)
4.9/5 (71)
(71) Use the following information for questions 80 through 84.
The following information relates to the pension plan for the employees of Turner Co.: 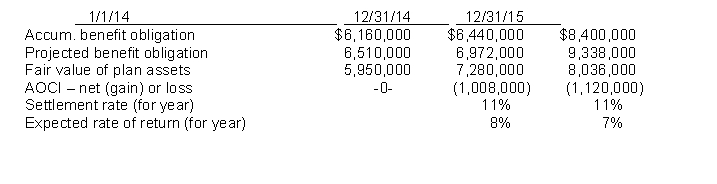 Turner estimates that the average remaining service life is 16 years. Turner's contribution was $882,000 in 2015 and benefits paid were $658,000.
-The interest cost for 2015 is
Turner estimates that the average remaining service life is 16 years. Turner's contribution was $882,000 in 2015 and benefits paid were $658,000.
-The interest cost for 2015 is (Multiple Choice)
4.8/5 (74)
(74) Presented below is pension information for Green Company for the year 2015: Expected return on plan assets \ 24,000 Interest on vested benefits 15,000 Service cost 50,000 Interest on projected benefit obligation 21,000 Amortization of prior service cost due to increase in benefits 18,000 The amount of pension expense to be reported for 2015 is
(Multiple Choice)
4.8/5 (73)
(73) Use the following information for questions 74 through 76.
The following data are for the pension plan for the employees of Lockett Company. 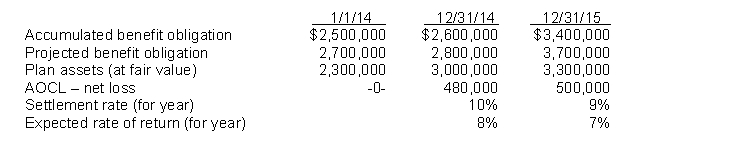 Lockett's contribution was $420,000 in 2015 and benefits paid were $375,000. Lockett
estimates that the average remaining service life is 15 years.
-The actual return on plan assets in 2015 was
Lockett's contribution was $420,000 in 2015 and benefits paid were $375,000. Lockett
estimates that the average remaining service life is 15 years.
-The actual return on plan assets in 2015 was (Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)