



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Farmer Inc. began business on January 1, 2014. Its pretax financial income for the first 2 years was as follows: 2014 \ 240,000 2015 560,000 The following items caused the only differences between pretax financial income and taxable income.1. In 2014, the company collected $360,000 of rent; of this amount, $120,000 was earned in 2014; the other $240,000 will be earned equally over the 2015-2016 period. The full $360,000 was included in taxable income in 2014.2. The company pays $10,000 a year for life insurance on officers."3. In 2015, the company terminated a top executive and agreed to $90,000 of severance pay. The amount will be paid $30,000 per year for 2015-2017. The 2015 payment was made. The $90,000 was expensed in 2015. For tax purposes, the severance pay is deductible as it is paid.The enacted tax rates existing at December 31, 2014 are: 2014 30\% 2016 40\% 2015 35\% 2017 40\%
Instructions
(a) Determine taxable income for 2014 and 2015.
(b) Determine the deferred income taxes at the end of 2014, and prepare the journal entry to record income taxes for 2014.
(c) Prepare a schedule of future taxable and (deductible) amounts at the end of 2015.(d) Prepare a schedule of the deferred tax (asset) and liability at the end of 2015.(e) Compute the net deferred tax expense (benefit) for 2015.(f) Prepare the journal entry to record income taxes for 2015.(g) Show how the deferred income taxes should be reported on the balance sheet at December 31, 2015."
(Essay)
4.8/5  (80)
(80) Use the following information for questions 79 and 80.
Rowen, Inc. had pre-tax accounting income of $1,800,000 and a tax rate of 40% in 2015, its first year of operations. During 2015 the company had the following transactions: 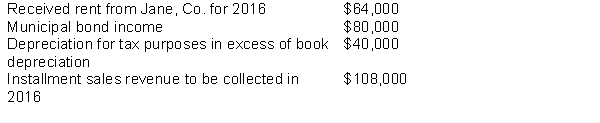 -At the end of 2015, which of the following deferred tax accounts and balances is reported on Rowen, Inc.'s balance sheet?
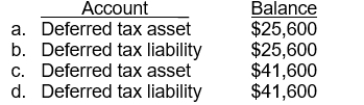
-At the end of 2015, which of the following deferred tax accounts and balances is reported on Rowen, Inc.'s balance sheet? (Short Answer)
4.8/5 (73)
(73) Under IFRS, all potential liabilities associated with uncertain tax positions are recognized.
(True/False)
4.8/5 (62)
(62) A company records an unrealized loss on short-term securities. This would result in what type of difference and in what type of deferred income tax? 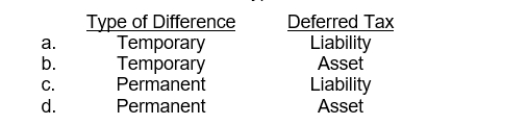
(Short Answer)
4.9/5 (77)
(77) A deferred tax liability represents the increase in taxes payable in future years as a result of taxable temporary differences existing at the end of the current year.
(True/False)
4.9/5 (81)
(81) Larsen Corporation reported $100,000 in revenues in its 2014 financial statements, of which $33,000 will not be included in the tax return until 2015. The enacted tax rate is 40% for 2014 and 35% for 2015. What amount should Larsen report for deferred income tax liability in its balance sheet at December 31, 2014?
(Multiple Choice)
4.7/5 (90)
(90) Indicate and explain whether each of the following independent situations should be treated as a temporary difference or a permanent difference.(a) For accounting purposes, a company reports revenue from installment sales on the accrual basis. For income tax purposes, it reports the revenues by the installment-sales method, deferring recognition of gross profit until cash is collected.(b) Pretax accounting income and taxable income differ because 80% of dividends received from U.S. corporations was deducted from taxable income, while 100% of the dividends received was reported for financial statement purposes.(c) Estimated warranty costs (covering a three-year warranty) are expensed for accounting purposes at the time of sale but deducted for income tax purposes when paid.
(Essay)
4.9/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)