



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Which of the following temporary differences results in a deferred tax asset in the year the temporary difference originates?
I.Accrual for product warranty liability.
II.Subscriptions received in advance
III.Prepaid insurance expense.
(Multiple Choice)
4.9/5  (76)
(76) For calendar year 2014, Kane Corp. reported depreciation of $1,200,000 in its income statement. On its 2014 income tax return, Kane reported depreciation of $1,800,000. Kane's income statement also included $225,000 accrued warranty expense that will be deducted for tax purposes when paid. Kane's enacted tax rates are 30% for 2014 and 2015, and 24% for 2016 and 2017. The depreciation difference and warranty expense will reverse over the next three years as follows: 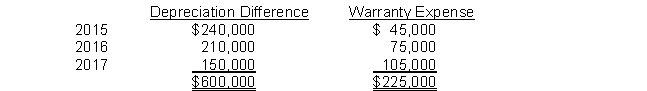 These were Kane's only temporary differences. In Kane's 2014 income statement, the deferred portion of its provision for income taxes should be
 (Multiple Choice)
4.7/5 (72)
(72) at the end of 2015, its first year of operations, prepared a reconciliation between pretax financial income and taxable income as follows: 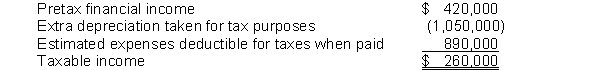 Use of the depreciable assets will result in taxable amounts of $350,000 in each of the next three years. The estimated litigation expenses of $890,000 will be deductible in 2018 when settlement is expected.
Instructions
(a) Prepare a schedule of future taxable and deductible amounts.
(b) Prepare the journal entry to record income tax expense, deferred taxes, and income taxes payable for 2015, assuming a tax rate of 40% for all years.
Use of the depreciable assets will result in taxable amounts of $350,000 in each of the next three years. The estimated litigation expenses of $890,000 will be deductible in 2018 when settlement is expected.
Instructions
(a) Prepare a schedule of future taxable and deductible amounts.
(b) Prepare the journal entry to record income tax expense, deferred taxes, and income taxes payable for 2015, assuming a tax rate of 40% for all years. (Essay)
4.8/5 (85)
(85) With regard to uncertain tax positions, the FASB requires that companies recognize a tax benefit when
(Multiple Choice)
4.9/5 (89)
(89) (a) Describe a deferred tax asset.(b) When should a deferred tax asset be reduced by a valuation allowance?
(Essay)
4.9/5 (73)
(73) Accounting for income taxes can result in the reporting of deferred taxes as any of the following except
(Multiple Choice)
4.8/5 (82)
(82) There are four types of temporary differences. For each type: (1) indicate the cause of the difference, (2) give an example, and (3) indicate whether it will create a taxable or deductible amount in the future.
(Essay)
4.9/5 (69)
(69) Ferguson Company has the following cumulative taxable temporary differences:  The tax rate enacted for 2015 is 40%, while the tax rate enacted for future years is 30%. Taxable income for 2015 is $4,800,000 and there are no permanent differences. Ferguson's pretax financial income for 2015 is
 (Multiple Choice)
4.9/5 (76)
(76) Which of the following is not considered a permanent difference?
(Multiple Choice)
4.9/5 (84)
(84) Recognition of tax benefits in the loss year due to a loss carryforward requires
(Multiple Choice)
4.8/5 (83)
(83) When a change in the tax rate is enacted into law, its effect on existing deferred income tax accounts should be
(Multiple Choice)
4.9/5 (87)
(87) Deductible amounts cause taxable income to be greater than pretax financial income in the future as a result of existing temporary differences.
(True/False)
4.8/5 (79)
(79) Use the following information for questions 55 through 57.
Mathis Co. at the end of 2014, its first year of operations, prepared a reconciliation between pretax financial income and taxable income as follows: 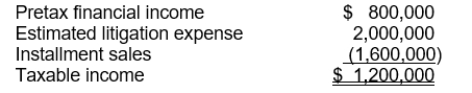 The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The income tax expense is
The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The income tax expense is (Multiple Choice)
4.8/5 (75)
(75) Use the following information for questions 70 through 72.
Lyons Company deducts insurance expense of $126,000 for tax purposes in 2014, but the expense is not yet recognized for accounting purposes. In 2015, 2016, and 2017, no insurance expense will be deducted for tax purposes, but $42,000 of insurance expense will be reported for accounting purposes in each of these years. Lyons Company has a tax rate of 40% and income taxes payable of $108,000 at the end of 2014. There were no deferred taxes at the beginning of 2014.
-What is the amount of income tax expense for 2014?
(Multiple Choice)
4.9/5 (73)
(73) The tax effect of a loss carryforward represents future tax savings and results in the recognition of a deferred tax asset.
(True/False)
4.9/5 (84)
(84) Stuart Corporation's taxable income differed from its accounting income computed for this past year. An item that would create a permanent difference in accounting and taxable incomes for Stuart would be
(Multiple Choice)
4.7/5 (93)
(93) Horner Corporation has a deferred tax asset at December 31, 2015 of $160,000 due to the recognition of potential tax benefits of an operating loss carryforward. The enacted tax rates are as follows: 40% for 2012-2014; 35% for 2015; and 30% for 2016 and thereafter. Assuming that management expects that only 50% of the related benefits will actually be realized, a valuation account should be established in the amount of:
(Multiple Choice)
5.0/5 (69)
(69) Use the following information for questions 76-78.
At the beginning of 2015; Elephant, Inc. had a deferred tax asset of $10,000 and a deferred tax liability of $15,000. Pre-tax accounting income for 2015 was $750,000 and the enacted tax rate is 40%. The following items are included in Elephant's pre-tax income: 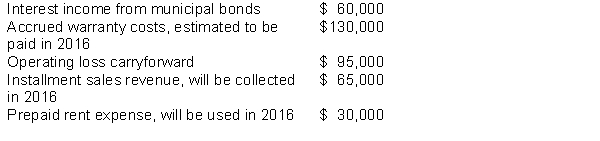 -The ending balance in Elephant, Inc's deferred tax liability at December 31, 2015 is
 (Multiple Choice)
4.7/5 (90)
(90) Munoz Corp.'s books showed pretax financial income of $2,700,000 for the year ended December 31, 2015. In the computation of federal income taxes, the following data were considered: 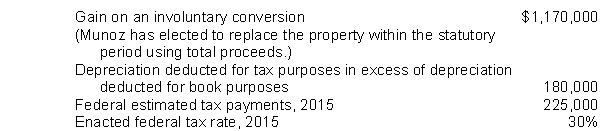 What amount should Munoz report as its current federal income tax liability on its December 31, 2015 balance sheet?
 (Multiple Choice)
4.8/5 (69)
(69) Companies must consider presently enacted changes in the tax rate that become effective in future years when determining the tax rate to apply to existing temporary differences.
(True/False)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)