



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Murphy Company purchased equipment for $300,000 on January 2, 2014, its first day of operations. For book purposes, the equipment will be depreciated using the straight-line method over three years with no salvage value. Pretax financial income and taxable income are as follows: 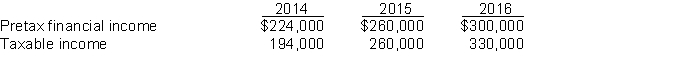 The temporary difference between pretax financial income and taxable income is due to the use of accelerated depreciation for tax purposes.
Instructions
(a) Prepare the journal entries to record income taxes for all three years (expense, deferrals, and liabilities) assuming that the enacted tax rate applicable to all three years is 30%.
(b) Prepare the journal entries to record income taxes for all three years (expense, deferrals, and liabilities) assuming that the enacted tax rate as of 2014 is 30% but that in the middle of 2015, Congress raises the income tax rate to 35% retroactive to the beginning of 2015.
The temporary difference between pretax financial income and taxable income is due to the use of accelerated depreciation for tax purposes.
Instructions
(a) Prepare the journal entries to record income taxes for all three years (expense, deferrals, and liabilities) assuming that the enacted tax rate applicable to all three years is 30%.
(b) Prepare the journal entries to record income taxes for all three years (expense, deferrals, and liabilities) assuming that the enacted tax rate as of 2014 is 30% but that in the middle of 2015, Congress raises the income tax rate to 35% retroactive to the beginning of 2015. (Essay)
4.9/5  (86)
(86) Under U.S. GAAP, the rate used to compute deferred taxes is either the enacted tax rate, or a substantially enacted tax rate (virtually certain).
(True/False)
4.9/5 (83)
(83) Cross Company reported the following results for the year ended December 31, 2014, its first year of operations: 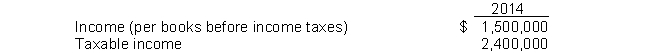 The disparity between book income and taxable income is attributable to a temporary difference which will reverse in 2015. What should Cross record as a net deferred tax asset or liability for the year ended December 31, 2014, assuming that the enacted tax rates in effect are 40% in 2014 and 35% in 2015?
 (Multiple Choice)
4.7/5 (84)
(84) Use the following information for questions 70 through 72.
Lyons Company deducts insurance expense of $126,000 for tax purposes in 2014, but the expense is not yet recognized for accounting purposes. In 2015, 2016, and 2017, no insurance expense will be deducted for tax purposes, but $42,000 of insurance expense will be reported for accounting purposes in each of these years. Lyons Company has a tax rate of 40% and income taxes payable of $108,000 at the end of 2014. There were no deferred taxes at the beginning of 2014.
-Assuming that income taxes payable for 2015 is $144,000, the income tax expense for 2015 would be what amount?
(Multiple Choice)
4.9/5 (70)
(70) Under the loss carryback approach, companies must apply a current year loss to the most recent year first and then to an earlier year.
(True/False)
4.8/5 (86)
(86) Use the following information for questions 55 through 57.
Mathis Co. at the end of 2014, its first year of operations, prepared a reconciliation between pretax financial income and taxable income as follows: 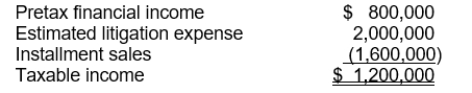 The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The deferred tax liability-current to be recognized is
The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The deferred tax liability-current to be recognized is (Multiple Choice)
4.8/5 (95)
(95) Use the following information for questions 89 and 90.
Wilcox Corporation reported the following results for its first three years of operation: 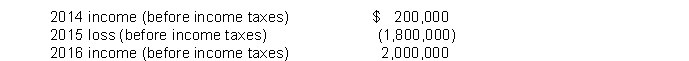 There were no permanent or temporary differences during these three years. Assume a corporate tax rate of 30% for 2014 and 2015, and 40% for 2016.
-Assuming that Wilcox elects to use the carryforward provision and not the carryback provision, what income (loss) is reported in 2015?
There were no permanent or temporary differences during these three years. Assume a corporate tax rate of 30% for 2014 and 2015, and 40% for 2016.
-Assuming that Wilcox elects to use the carryforward provision and not the carryback provision, what income (loss) is reported in 2015? (Multiple Choice)
5.0/5 (72)
(72) In 2014, Krause Company accrued, for financial statement reporting, estimated losses on disposal of unused plant facilities of $2,400,000. The facilities were sold in March 2015 and a $2,400,000 loss was recognized for tax purposes. Also in 2014, Krause paid $100,000 in premiums for a two-year life insurance policy in which the company was the beneficiary. Assuming that the enacted tax rate is 30% in both 2014 and 2015, and that Krause paid $780,000 in income taxes in 2014, the amount reported as net deferred income taxes on Krause's balance sheet at December 31, 2014, should be a
(Multiple Choice)
4.7/5 (80)
(80) The following information is available for Kessler Company after its first year of operations: 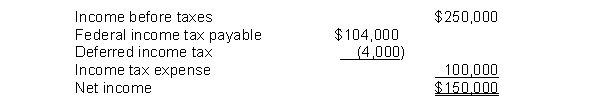 Kessler estimates its annual warranty expense as a percentage of sales. The amount charged to warranty expense on its books was $85,000. Assuming a 40% income tax rate, what amount was actually paid this year for warranty claims?
 (Multiple Choice)
4.8/5 (75)
(75) Rodd Co. reports a taxable and pretax financial loss of $800,000 for 2015. Rodd's taxable and pretax financial income and tax rates for the last two years were:  The amount that Rodd should report as an income tax refund receivable in 2015, assuming that it uses the carryback provisions and that the tax rate is 40% in 2015, is
 (Multiple Choice)
4.7/5 (74)
(74) A company should add a decrease in a deferred tax liability to income taxes payable in computing income tax expense.
(True/False)
4.7/5 (76)
(76) Foltz Corp.'s 2014 income statement had pretax financial income of $250,000 in its first year of operations. Foltz uses an accelerated cost recovery method on its tax return and straight-line depreciation for financial reporting. The differences between the book and tax deductions for depreciation over the five-year life of the assets acquired in 2014, and the enacted tax rates for 2014 to 2018 are as follows: 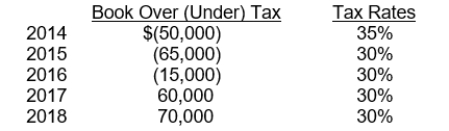 There are no other temporary differences. In Foltz's December 31, 2014 balance sheet, the noncurrent deferred income tax liability and the income taxes currently payable should be
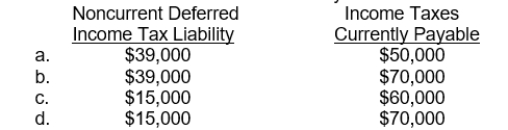
There are no other temporary differences. In Foltz's December 31, 2014 balance sheet, the noncurrent deferred income tax liability and the income taxes currently payable should be (Short Answer)
4.8/5 (97)
(97) Use the following information for questions 79 and 80.
Rowen, Inc. had pre-tax accounting income of $1,800,000 and a tax rate of 40% in 2015, its first year of operations. During 2015 the company had the following transactions: 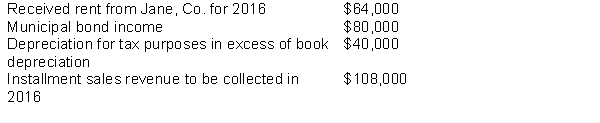 -For 2015, what is the amount of income taxes payable for Rowen, Inc?
 (Multiple Choice)
4.9/5 (83)
(83) Computation of taxable income.The records for Bosch Co. show this data for 2015:
Gross profit on installment sales recorded on the books was $420,000. Gross profit from collections of installment receivables was $280,000.
Life insurance on officers was $3,800.
Machinery was acquired in January for $300,000. Straight-line depreciation over a ten-year life (no salvage value) is used. For tax purposes, MACRS depreciation is used and Bosch may deduct 14% for 2015.
Interest received on tax exempt Iowa State bonds was $9,000.
The estimated warranty liability related to 2015 sales was $21,600. Repair costs under warranties during 2015 were $13,600. The remainder will be incurred in 2016.
Pretax financial income is $600,000. The tax rate is 30%.
Instructions
(a) Prepare a schedule starting with pretax financial income and compute taxable income.
(b) Prepare the journal entry to record income taxes for 2015.
(Essay)
4.9/5 (82)
(82) Use the following information for questions 55 through 57.
Mathis Co. at the end of 2014, its first year of operations, prepared a reconciliation between pretax financial income and taxable income as follows: The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The deferred tax asset to be recognized is
The estimated litigation expense of $2,000,000 will be deductible in 2016 when it is expected to be paid. The gross profit from the installment sales will be realized in the amount of $800,000 in each of the next two years. The estimated liability for litigation is classified as noncurrent and the installment accounts receivable are classified as $800,000 current and $800,000 noncurrent. The income tax rate is 30% for all years.
-The deferred tax asset to be recognized is (Multiple Choice)
5.0/5 (90)
(90) Taxable temporary differences will result in taxable amounts in future years when the related assets are recovered.
(True/False)
4.7/5 (73)
(73) at the end of 2015, its first year of operations, prepared a reconciliation between pretax financial income and taxable income as follows: 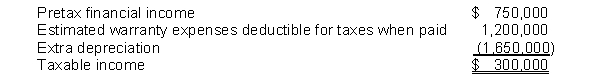 Estimated warranty expense of $800,000 will be deductible in 2016, $300,000 in 2017, and $100,000 in 2018. The use of the depreciable assets will result in taxable amounts of $550,000 in each of the next three years.
Instructions
(a) Prepare a table of future taxable and deductible amounts.
(b) Prepare the journal entry to record income tax expense, deferred income taxes, and income taxes payable for 2015, assuming an income tax rate of 40% for all years.
Estimated warranty expense of $800,000 will be deductible in 2016, $300,000 in 2017, and $100,000 in 2018. The use of the depreciable assets will result in taxable amounts of $550,000 in each of the next three years.
Instructions
(a) Prepare a table of future taxable and deductible amounts.
(b) Prepare the journal entry to record income tax expense, deferred income taxes, and income taxes payable for 2015, assuming an income tax rate of 40% for all years. (Essay)
4.8/5 (85)
(85) Examples of taxable temporary differences are subscriptions received in advance and advance rental receipts.
(True/False)
4.9/5 (89)
(89) On January 1, 2015, Piper Corp. purchased 40% of the voting common stock of Betz, Inc. and appropriately accounts for its investment by the equity method. During 2015, Betz reported earnings of $720,000 and paid dividends of $240,000. Piper assumes that all of Betz's undistributed earnings will be distributed as dividends in future periods when the enacted tax rate will be 30%. Ignore the dividend-received deduction. Piper's current enacted income tax rate is 25%. The increase in Piper's deferred income tax liability for this temporary difference is
(Multiple Choice)
5.0/5 (97)
(97) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)