



 Chat with AI
Exam 19: Accounting for Income Taxes

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Recognizing a valuation allowance for a deferred tax asset requires that a company
(Multiple Choice)
4.8/5  (73)
(73) Which of the following is false regarding accounting for deferred taxes under IFRS?
(Multiple Choice)
4.9/5 (76)
(76) Deferred tax expense is the increase in the deferred tax liability balance from the beginning to the end of the accounting period.
(True/False)
4.8/5 (81)
(81) Permanent differences do not give rise to future taxable or deductible amounts.
(True/False)
4.9/5 (90)
(90) Use the following information for questions 52 and 53.
At the beginning of 2015, Pitman Co. purchased an asset for $1,200,000 with an estimated useful life of 5 years and an estimated salvage value of $100,000. For financial reporting purposes the asset is being depreciated using the straight-line method; for tax purposes the double-declining-balance method is being used. Pitman Co.'s tax rate is 40% for 2015 and all future years.
-At the end of 2015, what are the book basis and the tax basis of the asset? 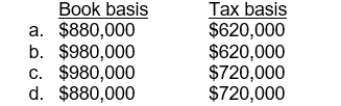
(Short Answer)
4.9/5 (92)
(92) Use the following information for questions 73 and 74.
Kraft Company made the following journal entry in late 2014 for rent on property it leases to Danford Corporation. 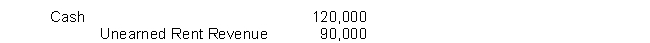 The payment represents rent for the years 2015 and 2016, the period covered by the lease. Kraft Company is a cash basis taxpayer. Kraft has income tax payable of $184,000 at the end of 2014, and its tax rate is 35%.
-Assuming the income taxes payable at the end of 2015 is $204,000, what amount of income tax expense would Kraft Company record for 2015?
The payment represents rent for the years 2015 and 2016, the period covered by the lease. Kraft Company is a cash basis taxpayer. Kraft has income tax payable of $184,000 at the end of 2014, and its tax rate is 35%.
-Assuming the income taxes payable at the end of 2015 is $204,000, what amount of income tax expense would Kraft Company record for 2015? (Multiple Choice)
4.8/5 (58)
(58) A deferred tax liability is classified on the balance sheet as either a current or a noncurrent liability. The current amount of a deferred tax liability should generally be
(Multiple Choice)
4.7/5 (76)
(76) All of the following are procedures for the computation of deferred income taxes except to
(Multiple Choice)
4.7/5 (86)
(86) A reconciliation of Gentry Company's pretax accounting income with its taxable income for 2014, its first year of operations, is as follows: 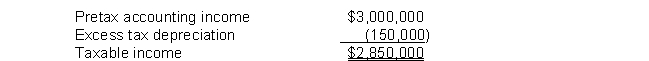 The excess tax depreciation will result in equal net taxable amounts in each of the next three years. Enacted tax rates are 40% in 2014, 35% in 2015 and 2016, and 30% in 2017. The total deferred tax liability to be reported on Gentry's balance sheet at December 31, 2014, is
 (Multiple Choice)
4.8/5 (71)
(71) A major distinction between temporary and permanent differences is
(Multiple Choice)
4.9/5 (93)
(93) Use the following information for questions 66 and 67.
Mitchell Corporation prepared the following reconciliation for its first year of operations: 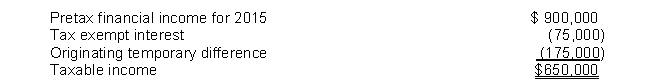 The temporary difference will reverse evenly over the next two years at an enacted tax rate of 40%. The enacted tax rate for 2015 is 35%.
-What amount should be reported in its 2015 income statement as the deferred portion of income tax expense?
The temporary difference will reverse evenly over the next two years at an enacted tax rate of 40%. The enacted tax rate for 2015 is 35%.
-What amount should be reported in its 2015 income statement as the deferred portion of income tax expense? (Multiple Choice)
4.9/5 (79)
(79) With regard to recognition of deferred tax assets, IFRS requires 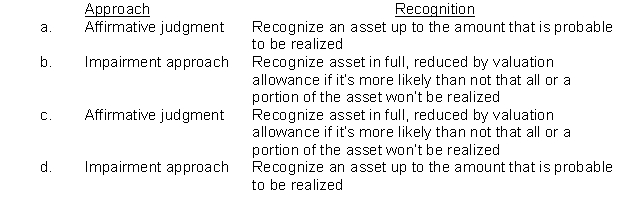
(Short Answer)
4.8/5 (79)
(79) A possible source of taxable income that may be available to realize a tax benefit for loss carryforwards is future reversals of existing taxable temporary differences.
(True/False)
4.7/5 (82)
(82) Palmer Co. had a deferred tax liability balance due to a temporary difference at the beginning of 2014 related to $900,000 of excess depreciation. In December of 2014, a new income tax act is signed into law that lowers the corporate rate from 40% to 35%, effective January 1, 2016. If taxable amounts related to the temporary difference are scheduled to be reversed by $450,000 for both 2015 and 2016, Palmer should increase or decrease deferred tax liability by what amount?
(Multiple Choice)
4.9/5 (79)
(79) Use the following information for questions 93 and 94.
Operating income and tax rates for C.J. Company's first three years of operations were as
follows: 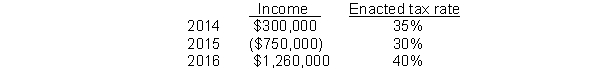 -Assuming that C.J. Company opts only to carryforward its 2015 NOL, what is the amount of deferred tax asset or liability that C.J. Company would report on its December 31, 2015 balance sheet?
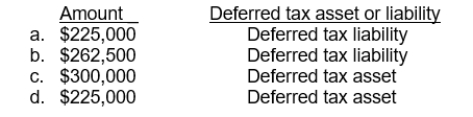
-Assuming that C.J. Company opts only to carryforward its 2015 NOL, what is the amount of deferred tax asset or liability that C.J. Company would report on its December 31, 2015 balance sheet? (Short Answer)
4.8/5 (78)
(78) Match the approach, IFRS or U.S. GAAP, with the location where tax effects are reported: 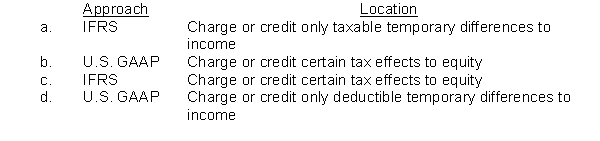
(Short Answer)
4.7/5 (73)
(73) A company reduces a deferred tax asset by a valuation allowance if it is probable that it will not realize some portion of the deferred tax asset.
(True/False)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)