



 Chat with AI
Exam 13: Perfect Competition

Exam 1: Economics and Economic Reasoning121 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization111 Questions
Exam 3: Economic Institutions144 Questions
Exam 4: Supply and Demand151 Questions
Exam 5: Using Supply and Demand136 Questions
Exam 6: Describing Supply and Demand: Elasticities176 Questions
Exam 7: Taxation and Government Intervention169 Questions
Exam 8: Market Failure Versus Government Failure160 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization107 Questions
Exam 10: International Trade Policy82 Questions
Exam 11: Production and Cost Analysis I160 Questions
Exam 12: Production and Cost Analysis II129 Questions
Exam 13: Perfect Competition137 Questions
Exam 14: Monopoly and Monopolistic Competition231 Questions
Exam 15: Oligopoly and Antitrust Policy111 Questions
Exam 16: Real-World Competition and Technology86 Questions
Exam 17: Work and the Labor Market130 Questions
Exam 18: Who Gets What the Distribution of Income100 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand134 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics76 Questions
Exam 21: Thinking Like a Modern Economist67 Questions
Exam 22: Behavioral Economics and Modern Economic Policy87 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond111 Questions
Select questions type


In a perfectly competitive market, the demand curve faced by an individual firm is:

Free
(Multiple Choice)
4.7/5  (82)
(82) Correct Answer: Verified
C
In a perfectly competitive market, economic forces are controlled by government policy makers.
Free
(True/False)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedFalse
Based on the information shown, a perfectly competitive profit-maximizing firm would produce: Quantity Total Cost Tatal Revenue 10 \ 25 50 20 60 100 30 105 150 40 160 200
Free
(Multiple Choice)
4.8/5 (73)
(73) Correct Answer:Verified
VerifiedC
The existence of positive economic profits induces firms to:
(Multiple Choice)
4.8/5 (65)
(65) Assume the smart watch industry is a perfectly competitive industry that uses a specialized input. If this industry experiences an increase in demand, we might expect that in the long run:
(Multiple Choice)
4.9/5 (86)
(86) Refer to the graph shown. If the market price is P2, the firm will produce: 
(Multiple Choice)
4.9/5 (79)
(79) Refer to the graph shown. If the firm is producing 250 units of output, profit is equal to: 
(Multiple Choice)
4.8/5 (81)
(81) Refer to the graph shown. If the firm increases output from 30 to 40, total revenue will increase: 
(Multiple Choice)
4.7/5 (74)
(74) Refer to the graph shown. If market price is currently $3.00 per unit, this perfectly competitive firm will maximize profit by producing: 
(Multiple Choice)
4.8/5 (82)
(82) Refer to the graph shown. The marginal cost of producing the 60th unit is: 
(Multiple Choice)
4.9/5 (68)
(68) Refer to the graph shown, which depicts a perfectly competitive firm. When maximizing profit, the firm represented will earn per-unit profit roughly equal to: 
(Multiple Choice)
4.9/5 (87)
(87) A perfectly competitive firm will be profitable if price at the profit-maximizing quantity is above:
(Multiple Choice)
4.8/5 (70)
(70) Refer to the graphs shown, which depict a perfectly competitive market and firm. If market demand decreases from D0 to D1, the firm will: 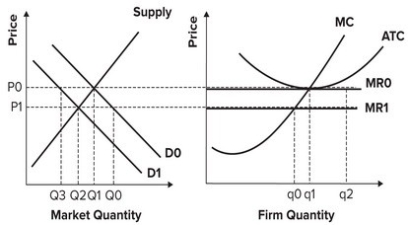
(Multiple Choice)
4.9/5 (81)
(81) Refer to the graph shown. Assuming that the industry operates under conditions of perfect competition and that the cost curves do not shift, the price of construction in a long-run competitive equilibrium will be: 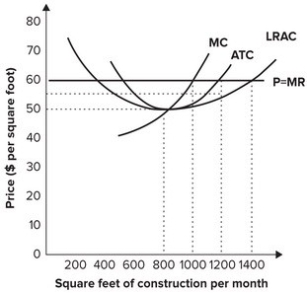
(Multiple Choice)
4.9/5 (70)
(70) If a perfectly competitive firm finds that price is less than average variable cost, it should:
(Multiple Choice)
4.9/5 (85)
(85) Refer to the graph shown. If the firm is producing 525 units of output, profit is equal to: 
(Multiple Choice)
4.9/5 (80)
(80) Refer to the graph shown. Assuming that the industry operates under conditions of perfect competition and that the firms seek to maximize profits, this firm will: 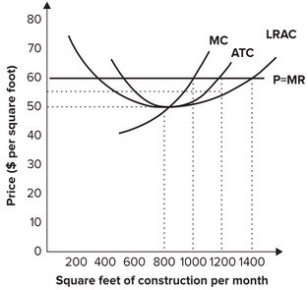
(Multiple Choice)
4.8/5 (77)
(77) Long-run competitive equilibrium in an industry implies that no firm:
(Multiple Choice)
4.9/5 (76)
(76) Refer to the graph shown, which depicts a perfectly competitive firm. If the price of the product is $8 and the firm maximizes profit: 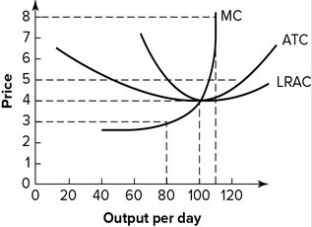
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)