



 Chat with AI
Exam 13: Perfect Competition

Exam 1: Economics and Economic Reasoning37 Questions
Exam 2: The Production Possibility Model, Trade and Globalization22 Questions
Exam 3: Economic Institutions19 Questions
Exam 4: Supply and Demand31 Questions
Exam 5: Using Supply and Demand27 Questions
Exam 6: Describing Supply and Demand: Elasticities40 Questions
Exam 7: Taxation and Government Intervention32 Questions
Exam 8: Market Failure Versus Government Failure38 Questions
Exam 9: International Trade Policy, Comparative Advantage, and Outsourcing13 Questions
Exam 10: International Trade Policy24 Questions
Exam 11: Production and Cost Analysis I34 Questions
Exam 12: Production and Cost Analysis II23 Questions
Exam 13: Perfect Competition35 Questions
Exam 14: Monopoly47 Questions
Exam 15: Monopolistic Competition and Oligopoly33 Questions
Exam 16: Real-World Competition and Technology22 Questions
Exam 17: Work and the Labor Market38 Questions
Exam 18: Who Gets What the Distribution of Income34 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand36 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics27 Questions
Exam 21: Thinking Like a Modern Economist30 Questions
Exam 22: Behavioral Economic Policy39 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond23 Questions
Select questions type


Some firms, particularly but not exclusively Japanese firms, have historically considered their workers to be lifetime employees. Let's call these firms Type A firms. How would this management attitude affect Type A firms' production decisions during a period of slack demand and falling prices relative to other (Type
B) firms?
(Essay)
4.7/5  (77)
(77) Describe how a market supply curve relates to a firm's supply curve. How does the short-run market supply curve differ from the long run market supply curve?
(Essay)
4.8/5 (84)
(84) Explain how the long-run market supply curve for a perfectly competitive industry depends upon factor prices. How would this apply to the milk producing industry?
(Essay)
4.8/5 (74)
(74) Consider the following table of numbers, which represents demand and cost conditions for a competitive firm.
(a) Fill in the missing values.
(b) What level of output should the firm produce? Explain. Total P=MR Q TFC AFC TVC AVC TC ATC MC TR Profit 600 0 - 0 - 570 - 600 1 570 240 600 2 430 600 3 670 600 4 960 600 5 1,350 600 6 1,840 600 7 2,430 600 8 3,120 600 9 3,910 600 10 4,800
(Essay)
4.8/5 (73)
(73) In determining the supply curve of a perfectly competitive firm, what cost information do you need? Why do you need that information? Explain.
(Essay)
4.8/5 (85)
(85) Consider the following table of numbers, which represents demand and cost conditions for a competitive firm. What output level should the firm produce? Explain. Quantity Price = MR Produced MC 600 0 600 1 240 600 2 190 600 3 240 600 4 290 600 5 390 600 6 490 600 7 590 600 8 690 600 9 790 600 10 890 NOTE: Marginal values represent values between levels of output. For example, the marginal cost between 0 units and 1 unit is $240.
(Essay)
4.9/5 (83)
(83) Perfectly competitive firms are price takers. However, in the real world, it is rare that the customer goes into any business establishment and tells the seller what price he is willing to pay. Since buyers don't dictate price, where does price come from in perfectly competitive markets?
(Essay)
4.8/5 (92)
(92) Study the graph below and answer the following questions. 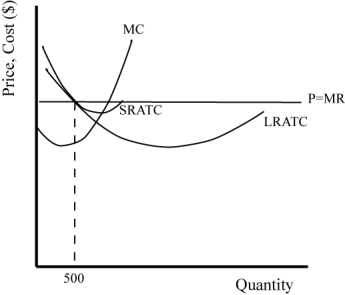 (a) Is this firm making profit by producing 500 units in the short run? Why or why not?
(b) What will happen in the long run in this industry?
(c) Will the firm survive in this industry?
(a) Is this firm making profit by producing 500 units in the short run? Why or why not?
(b) What will happen in the long run in this industry?
(c) Will the firm survive in this industry? (Essay)
4.9/5 (77)
(77) Consider the following table of numbers, which represents demand and cost conditions for a competitive firm. The price of the product this firm produces is $50. Q TFC MC TVC TC TR MR Total Profit 0 30 0 1 20 2 30 3 40 4 50 5 60 6 70 (a) Fill in the missing values.
(b) What level of output should the firm produces? Why?
(c) What do you predict will happen to the number of firms in the industry? Why?
(d) What do you predict will happen to supply and the market price?
(e) At which price must the firm shut down?
(Essay)
4.9/5 (89)
(89) Retail stores generally set a fixed price and let people buy all they want at that price. Does that mean that the supply curve of those goods is perfectly elastic?
(Essay)
4.9/5 (90)
(90) Consider the following diagram of a representative competitive firm: 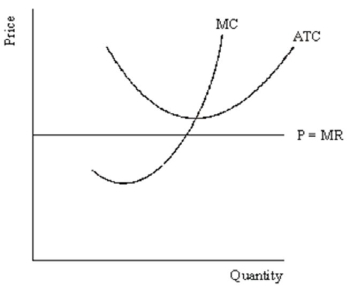 Is this a long-run equilibrium situation? If yes, explain why it is. If no, explain what will happen to transform it into a long-run equilibrium situation.
 (Essay)
4.8/5 (89)
(89) Demonstrate graphically and explain verbally the case of a constant-cost industry in a perfectly competitive market. Draw both a firm and a market diagram. HINT: The long-run market supply curve in your diagram should be perfectly elastic (i.e., horizontal).
(Essay)
4.8/5 (77)
(77) Using a supply and demand and a typical firm diagram, illustrate the impact of a flood on the market for contractors once the flood has receded. NOTE: Assume the market was perfectly competitive and in a long-run equilibrium position before the flood. Also assume that construction is a constant-cost industry.
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)