



 Chat with AI
Exam 14: Monopoly


The law of demand states that the greater the quantity of a good purchased, the lower its price will have to be, other things held constant. Explain why monopoly firms see this law in action but perfectly competitive firms do not.

 (88)
 Verified
A monopoly firm faces the entire market demand, which is downward sloping. Thus, as stated in the law of demand, in order for a monopolist to induce consumers to buy more of its product, it must lower the product price. In contrast to this, a perfectly competitive firm does not face the entire market demand curve. Rather, as a price taker, a competitive firm faces a horizontal demand curve; indicating that the firm can sell as much or as little as it wants at the prevailing market price. This is so because each competitive firm is, by definition, a small part of the entire market, so that any production changes it undertakes do not have any impact on the market supply (and so do not have any impact on the market equilibrium price).
In what ways is monopolistic competition different from perfect competition? In what ways are they alike?
(79) VerifiedIn monopolistic competition, products are differentiated, while in perfect competition, products are homogeneous (identical). Product differentiation creates some monopoly power so that with monopolistic competition, marginal revenue is less than price while in perfect competition they are equal. If price and marginal revenue are not the same, then price and marginal cost will not be equal in long-run equilibrium in monopolistic competition as they are in perfect competition. Likewise, output will not be produced at minimum average total cost in monopolistic competition, though it will be so in perfect competition. Product differentiation also provides incentives and opportunities for a variety of forms of non-price competition, such as advertising, packaging, promotions, and product differentiation itself. In perfect competition, all firms take price and the nature of the product as a given.
Both perfect and monopolistic competition have easy entry conditions, and consequently, both perfect and monopolistic competition result in firms making zero economic profits in long-run equilibrium. The existence of so many firms in both pure competition and monopolistic competition results in independent behavior by all firms.
Demonstrate graphically and explain verbally the case of a monopolistically competitive firm earning a positive economic profit. Is this firm in a short run or a long-run equilibrium? In the short run, how does this case differ from the monopoly market outcome?
(66) VerifiedThe monopolistically competitive firm determines its profit maximizing output level by producing where MR = MC (QM in the diagram). The firm determines its price by reading it off of the demand curve above QM (price is PM in the diagram). The firm is earning a positive economic profit as shown by the filled in rectangle in the diagram. 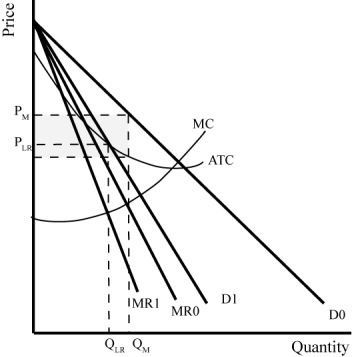 This represents a short-run equilibrium; in the long run there can be no positive economic profit for the firm since with easy entry in the long run other firms will enter in and compete away any short run positive economic profit. Therefore, the firm in long-run equilibrium will produce at QLR with a price of PLR, as shown in the diagram above. In the short run, there is no difference between the equilibrium of a monopolist and a monopolistic competitor.
Define monopoly. What is the primary reason for the existence of a monopoly? Describe three types of barriers to entry.
(95) Compare how P, ATC, MC, and MR are related to each other in the long-run equilibrium of a perfectly competitive firm and a monopolistically competitive firm. What is the key difference between them?
(84) Why will a monopolistic firm maximize total profit if it produces at the output level where marginal revenue equals marginal cost?
(84) What are the two keys that enable a monopolist to successfully price discriminate?
(78) Compare how P, ATC, MC, and MR are related to each other in the long-run equilibrium setting for a perfectly competitive firm and a monopolistically competitive firm.
(85) Briefly discuss three possible barriers to entry for an industry and assess whether these barriers are good or bad for consumers or society as a whole.
(87) Consider the following diagram:  Demonstrate graphically and explain verbally why moving away from producing output level Q0 will result in a decrease in profit for this monopolist.
 (73) Demonstrate graphically and explain verbally an example where a monopolist is better-off shutting down.
(78) Give three real world examples of price discrimination practices that some companies follow.
(76) What are the four distinguishing characteristics of monopolistic competition? How does monopolistic competition differ from oligopoly?
(64) How are a monopolist's price, output, and profit determined graphically?
(83) You own four firms that produce different products. The following table summarizes the conditions in each firm. After calculating the missing numbers for each firm, choose a decision for each firm from among the following four decisions, and explain how you reached each particular decision.
(a) continue producing the same output level
(b) shut down
(c) increase output
(d) decrease output Firm P MR TR Q TC MC ATC AVC A 11 8 20 200 5 9 B 3 1 100 1.5 2.5 2 C 4 2 200 2 7 5 D 8 5 10 70 5 6
(73) In long-run equilibrium in both perfect competition and monopolistic competition there is zero economic profit and yet the two cases are not identical. What is the key difference between them?
(86) Demonstrate graphically and explain verbally the case of a monopolist earning zero economic profit.
(74) Demonstrate graphically and explain verbally an example of a monopolist earning a positive economic profit.
(75) What is the key difference between a perfectly competitive firm and a monopolist with respect to the relationship between price and marginal revenue?
(84) Graphically show the transition from short-run to long-run equilibrium for a monopolistic competitor. Begin by drawing a graph of short-run equilibrium. In the graph, have the firm make an economic profit at its profit-maximizing level of output. Identify its short-run profit, and then show and describe how profits will disappear in long-run equilibrium.
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)