



 Chat with AI
Exam 13: Perfect Competition


A perfectly competitive market is a market in which economic forces operate unimpeded. The six conditions necessary to have a perfectly competitive market are: (1.) Both buyers and sellers are price takers. (2.) The number of firms is large. (3.) There are no barriers to entry. (4.) Firms' products are identical. (5.) There is complete information. And (6.) selling firms are profit maximizing entrepreneurial firms. Discuss any three of these conditions.

 (77)
 Verified
(Any three of the following)
1. In a perfectly competitive industry both buyers and sellers are price takers. Price takers are firms or individuals who take the price determined by the market equilibrium as given. In a perfectly competitive market, market supply and demand determine the price; both firms and consumers take the price as given.
2. A large number of firms in this context means that there are so many firms that any one firm's output compared to market output is imperceptible, and what one firm does has no influence on what other firms do.
3. There are no barriers to entry. Barriers to entry may be social, political or economic impediments that prevent firms from entering a market. In a perfectly competitive industry, there could be no patents, and the minimum efficient scale should allow a large number of firms to produce at the lowest average cost.
4. Each firm's output is indistinguishable from any other firm's output. Corn sold on national grain markets would be an example. The price of all bushels would be the same. Pepsi and Coke are examples of products that are not identical. They may sell at different prices in the market and the market for colas and therefore cannot be regarded as perfectly competitive.
5. In a perfectly competitive market, firms and consumers know all there is to know about the market. This would include prices, products and available technology. Thus no firm or consumer would have a competitive edge over another.
6. For perfect competition to exist, firms must seek maximum profit and only profit, and the people who make the firm's decisions must receive profit and only profit.
Why will perfectly competitive firms make zero profits in the long run? How are normal profits related to economic profits?
(71) Verified(a) In the short run, the number of firms is fixed and the firm can either make a profit or a loss. In the long run however, firms will enter markets where other firms are earning short run profits. They will keep on entering until prices fall to the point where all economic profits are competed away and firms earn nothing but normal profits. In the long run, firms also will exit from markets where firms are making short run losses. They will keep on exiting until prices rise to a level where all economic losses are eliminated and the remaining firms earn normal profits.
(b) Normal profit means that the resources provided by the owners of the firm are earning their opportunity cost (the amount the owners of the business would receive in the next-best alternative use of their resources). Economic profit occurs when revenue exceeds all costs, including the opportunity cost of resources provided by the owners (normal profits). When firms earn economic profits, it means that the owners are earning more than their opportunity costs.
The American Widget Corporation (AWC) is a profit-maximizing and perfectly competitive firm that is currently experiencing a loss. However, the market price of widgets is expected to increase in the near future. The company's vice-president, Alan R. ("Big Tuna") Burns, has recommended against increasing output in response to a higher price for widgets. His argument is that the marginal cost of the additional units of output will increase, and these higher costs will worsen AWC's losses. Evaluate this argument using an appropriate picture.
(81) VerifiedThe argument is incorrect. Initially price is P0 and output is Q0 as shown in the diagram below. The firm incurs a loss of (C1 - P0) × (Q0). If the price increases to P1, profits will be maximized at output level Q1, where the marginal revenue curve intersects the marginal cost curve. "Big Tuna" is right that marginal cost is higher at Q1, but the firm would not be maximizing profit at the lower output Q0. At Q0, MR > MC and the firm can make more (decrease its losses) by increasing output until it reaches Q1. 
In determining the supply curve of a perfectly competitive firm, what cost information do you need? Explain.
(90) Using the following diagram, demonstrate graphically and explain verbally why any movement away from output level Q0 would decrease the firm's profit. 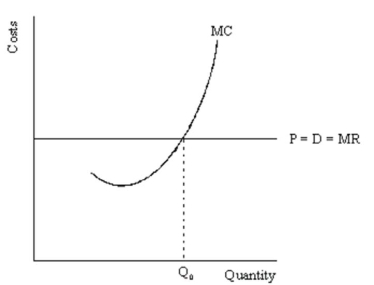
(71) Explain how the long-run market supply curve for a perfectly competitive industry depends upon factor prices.
(80) Define a perfectly competitive market, and list the six conditions necessary for a market to be perfectly competitive.
(83) Explain, using an example if necessary to be clear, why the minimum point on the average variable cost curve is the shutdown point. In other words, why is a competitive firm's supply curve that portion of the marginal cost curve that lies above the minimum average variable cost?
(90) Using the following diagram, demonstrate that producing at the level of output associated with maximum per unit profit (minimum of the ATC curve) does not maximize total profit. 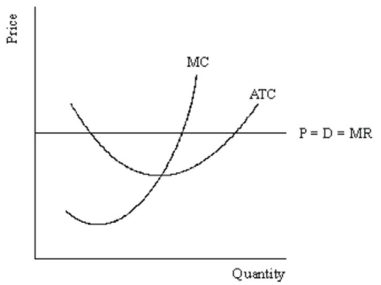
(82) Demonstrate graphically and explain verbally where the level of output should be when a perfectly competitive firm is earning a positive economic profit. Be sure to label the profit maximizing level of output and shade in the area that represents profit.
(75) Demonstrate graphically and explain verbally how a demand curve facing a perfectly competitive firm relates to the market demand curve.
(81) Demonstrate graphically and explain verbally a perfectly competitive firms' long run equilibrium situation (be sure to show the long-run average total cost curve, short-run average total cost curve, marginal curve, and marginal revenue curve).
(83) Demonstrate graphically and explain verbally how a perfectly competitive firm's MC curve is its supply curve.
(75) How would an economist determine graphically the output and profit of a perfect competitor?
(84) Consider the following diagram: 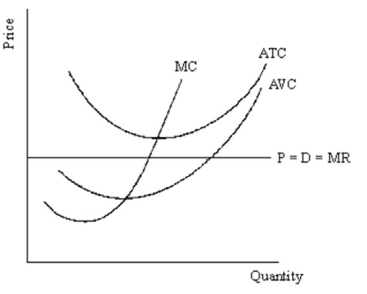 Would a perfectly competitive firm facing these conditions stay in business in the short run? Demonstrate your answer by comparing the loss if it stayed open to the loss if it closed.
 (86) Which of the necessary conditions for perfect competition are least likely to be satisfied in the real world? Explain your selections.
(75) Using the following diagram, demonstrate graphically and explain verbally why Q0 is not a profit maximizing output level. 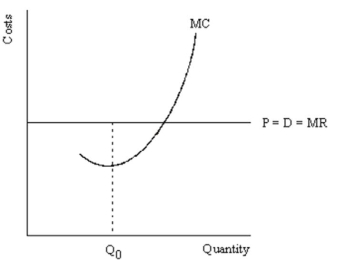
(61) Firms know that when they enter a profitable industry, profits will eventually be eliminated by competition. Why would a firm want to enter such an industry?
(85) You are running a business in a perfectly competitive market. Your product sells for $5 and your marginal costs rise as output rises. What should you do in the two situations described below? What general rule do the above examples suggest about how a firm should determine the level of output to produce so as to maximize profit?
(a) The additional cost of producing another unit of output is $4. What should you do? What will this do to your total profit?
(b) The additional cost incurred from your last unit of output produced is $6. What should you do? What will this do to your total profit?
(c) What general rule do the above examples suggest about how a firm should determine the level of output to produce so as to maximize profit?
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)