



 Chat with AI
Exam 2: The Key Principles of Economics

Exam 1: Introduction: What Is Economics144 Questions
Exam 2: The Key Principles of Economics195 Questions
Exam 3: Exchange and Markets135 Questions
Exam 4: Demand, Supply, and Market Equilibrium279 Questions
Exam 5: Measuring a Nations Production and Income161 Questions
Exam 6: Unemployment and Inflation206 Questions
Exam 7: The Economy at Full Employment165 Questions
Exam 8: Why Do Economies Grow203 Questions
Exam 9: Aggregate Demand and Aggregate Supply189 Questions
Exam 10: Fiscal Policy166 Questions
Exam 11: The Income-Expenditure Model265 Questions
Exam 12: Investment and Financial Markets179 Questions
Exam 13: Money and the Banking System184 Questions
Exam 14: The Federal Reserve and Monetary Policy203 Questions
Exam 15: Modern Macroeconomics: From the Short Run to the Long Run176 Questions
Exam 16: The Dynamics of Inflation and Unemployment186 Questions
Exam 17: Macroeconomic Policy Debates143 Questions
Exam 18: International Trade and Public Policy226 Questions
Exam 19: The World of International Finance189 Questions
Select questions type


 -Refer to Table 2.4. The marginal product of the 3rd tank of fertilizer is:
 (Multiple Choice)
4.8/5  (89)
(89) What is the opportunity cost of investing $10,000 of your own money in a business you wish to start?
(Essay)
5.0/5 (75)
(75) According to the marginal principle, a rational individual should undertake an economic activity as long as the:
(Multiple Choice)
4.8/5 (92)
(92) Recall Application 5, "The Declining Real Minimum Wage," to answer the following questions:
-According to the application, if the weekly income from 1974 to 2007 increased from $80 to $234, but the number of standard baskets of goods that the weekly income decreased from 1.70 to 1.16 in 2007, then we can conclude that:
(Multiple Choice)
4.8/5 (77)
(77) If the price level falls faster than the wage rate, then the real wage decreases.
(True/False)
4.8/5 (69)
(69) The principle that states that the cost of something is equal to what is sacrificed to get it is known as the:
(Multiple Choice)
4.9/5 (80)
(80) The marginal output of labor is the amount of output that can be produced if one more unit of labor is added.
(True/False)
4.7/5 (79)
(79) Economists argue that individuals should continue to consume until total benefit equals total cost.
(True/False)
4.9/5 (89)
(89) 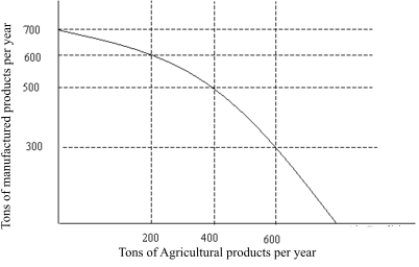 Figure 2.1
-The production possibilities curve in Figure 2.1 illustrates the notion of:
Figure 2.1
-The production possibilities curve in Figure 2.1 illustrates the notion of: (Multiple Choice)
4.8/5 (61)
(61)  Figure 2.1
-On the production possibilities curve in Figure 2.1 as agricultural production increases by 200 tons per year from 200 tons to 400 tons and then to 600 tons, the opportunity cost in terms of tons of manufacturing goods:
Figure 2.1
-On the production possibilities curve in Figure 2.1 as agricultural production increases by 200 tons per year from 200 tons to 400 tons and then to 600 tons, the opportunity cost in terms of tons of manufacturing goods: (Multiple Choice)
4.9/5 (73)
(73) Suppose that your tuition to attend college is $10,000 per year and you spend $4,000 per year on room and board. If you were working full time instead of attending college, you could earn $20,000 per year. What is your opportunity cost of attending college for one year?
(Multiple Choice)
4.8/5 (82)
(82) Nancy and Melissa both have broken light fixtures in their living rooms. Nancy opts to hire an electrician, while Melissa spends two hours replacing the fixture herself. Which of the following is a possible explanation of this behavior?
(Multiple Choice)
4.8/5 (96)
(96) Suppose prices increase by 3% per year. What nominal percentage return on your savings account would you require to get a 3% real return?
(Multiple Choice)
4.7/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)