



 Chat with AI
Exam 17: Growth and Productivity: Long-Run Possibilities

Exam 1: Economics: the Core Issues152 Questions
Exam 2: The Useconomy: a Global View146 Questions
Exam 3: Supply and Demand164 Questions
Exam 4: The Role of Government153 Questions
Exam 5: National Income Accounting152 Questions
Exam 6: Unemployment147 Questions
Exam 7: Inflation152 Questions
Exam 8: The Business Cycle153 Questions
Exam 9: Aggregate Demand149 Questions
Exam 10: Self-Adjustment or Instability140 Questions
Exam 11: Fiscal Policy151 Questions
Exam 12: Deficits and Debt151 Questions
Exam 13: Money and Banks146 Questions
Exam 14: The Federal Reserve System146 Questions
Exam 15: Monetary Policy149 Questions
Exam 16: Supply-Side Policy: Short-Run Options147 Questions
Exam 17: Growth and Productivity: Long-Run Possibilities143 Questions
Exam 18: Theory Versus Reality146 Questions
Exam 19: Consumer Choice136 Questions
Exam 20: Elasticity141 Questions
Exam 21: The Costs of Production151 Questions
Exam 22: The Competitive Firm148 Questions
Exam 23: Competitive Markets150 Questions
Exam 24: Monopoly147 Questions
Exam 25: Oligopoly145 Questions
Exam 26: Monopolistic Competition144 Questions
Exam 27: Natural Monopolies: Deregulation144 Questions
Exam 28: Environmental Protection144 Questions
Exam 29: The Farm Problem132 Questions
Exam 30: The Labor Market137 Questions
Exam 31: Labor Unions144 Questions
Exam 32: Financial Markets146 Questions
Exam 33: Taxes: Equity Versus Efficiency146 Questions
Exam 34: Transfer Payments: Welfare and Social Security146 Questions
Exam 35: International Trade149 Questions
Exam 36: International Finance142 Questions
Exam 37: Global Poverty141 Questions
Select questions type


Approximately how long would it take for real GDP to double if it grew at a constant annual rate of 2 percent?

Free
(Multiple Choice)
4.9/5  (76)
(76) Correct Answer: Verified
B
The most common measure of productivity is output per
Free
(Multiple Choice)
4.7/5 (86)
(86) Correct Answer:Verified
VerifiedC
If real GDP rises from $700 billion to $704 billion,the economic growth rate is
Free
(Multiple Choice)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedB
In order to shift the current production possibilities curve outward,an economy
(Multiple Choice)
4.9/5 (93)
(93) Table 17.1 Year Real GDP Population 1 \ 575 billion 22 million 2 \ 580 billion 24 million 3 \ 605 billion 25 million 4 \ 606 billion 27 million
Refer to Table 17.1.From year 3 to year 4,real GDP per capita
(Multiple Choice)
4.9/5 (75)
(75) Growth in real GDP per capita is achieved when population grows more rapidly than output.
(True/False)
4.8/5 (76)
(76) The idea that the U.S.economy would continue to experience rapid gains in productivity and GDP growth was interrupted in 2001.
(True/False)
5.0/5 (88)
(88) Table 17.1 Year Real GDP Population 1 \ 575 billion 22 million 2 \ 580 billion 24 million 3 \ 605 billion 25 million 4 \ 606 billion 27 million
Refer to Table 17.1.GDP per capita in year 1 was
(Multiple Choice)
4.8/5 (82)
(82) Which of the following would not increase labor productivity,ceteris paribus?
(Multiple Choice)
4.9/5 (65)
(65) In recent decades,a primary source of growth in U.S.output has been
(Multiple Choice)
4.9/5 (85)
(85) In the short run,movement toward a fixed production possibilities curve comes from
(Multiple Choice)
4.8/5 (68)
(68) Assume the real U.S.GDP in 1997 was $7,269 billion and the U.S.population was 268 million,and the real U.S.GDP in 1998 was $7,552 billion and the U.S.population was 270 million.From 1997 to 1998,the per capita real GDP
(Multiple Choice)
4.9/5 (76)
(76) Corporations in the United States spend a lot of money to familiarize management with global markets.This should
(Multiple Choice)
4.8/5 (67)
(67) 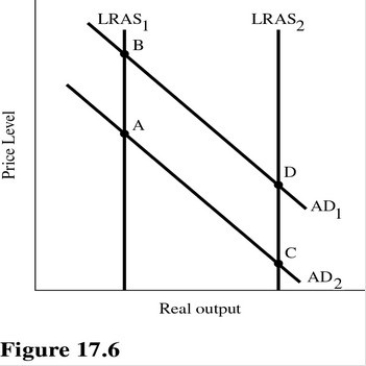 A shift from LRAS1 to LRAS2 in Figure 17.6 indicates that
Which of the following could impede productivity improvements?
(Multiple Choice)
4.7/5 (95)
(95) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)