



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem439 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity449 Questions
Exam 6: Government Actions in Markets410 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices464 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs494 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly606 Questions
Exam 14: Monopolistic Competition320 Questions
Exam 15: Oligopoly280 Questions
Exam 16: Public Choices and Public Goods356 Questions
Exam 17: Externalities and the Environment284 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality354 Questions
Exam 20: Uncertainty and Information233 Questions
Exam 21: Extension A: Review11 Questions
Exam 22: Extension B: Review25 Questions
Exam 23: Extension C: Review14 Questions
Exam 24: Extension D: Review38 Questions
Exam 25: Extension E: Review11 Questions
Exam 26: Extension F: Review18 Questions
Select questions type


 -In the above figure, if the firm increases its output from Q2 to Q3, it will
 (Multiple Choice)
4.9/5  (85)
(85) If the market price faced by a perfectly competitive firm increases, in the short run how does the firm respond?
(Essay)
5.0/5 (73)
(73) The owners will shut down a perfectly competitive firm if the price of its good falls below its minimum
(Multiple Choice)
4.8/5 (83)
(83) In the short run, an increase in demand for a good that is sold in a perfectly competitive market
(Multiple Choice)
4.7/5 (81)
(81)  -Consider the perfectly competitive firm in the above figure. At the profit maximizing level of output, the firm is
 (Multiple Choice)
5.0/5 (77)
(77) A perfectly competitive firm's economic profit is maximized by producing the amount of output such that
(Multiple Choice)
4.9/5 (84)
(84) If the price exceeds the average variable cost, by producing the level of output such that marginal revenue equals marginal cost, the firm ensures that it will
(Multiple Choice)
4.8/5 (74)
(74) 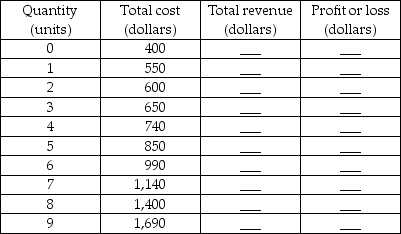 -The above table shows the total cost schedule for a perfectly competitive firm. The market price is $250 per unit. Complete the table.
 (Essay)
4.8/5 (78)
(78) 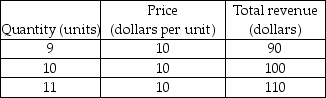 -Based on the table above, what is the marginal revenue of the tenth unit of output?
 (Multiple Choice)
4.8/5 (83)
(83) The market for maple syrup is perfectly competitive. Suppose that the market is in long-run equilibrium when the market demand for maple syrup increases. In the long run, firms will ________ the market and the market ________ will ________.
(Multiple Choice)
4.8/5 (84)
(84) In the long run, perfectly competitive firms cannot earn an economic profit.
(True/False)
4.8/5 (71)
(71) Today, firms in a perfectly competitive market are making an economic profit. In the long run, firms will ________ the market until all firms in the market are ________.
(Multiple Choice)
4.7/5 (77)
(77)  -The figure above shows the costs for a grower in the perfectly competitive turnip market. If the price is $1,000 for a ton of turnips, the firm is
 (Multiple Choice)
4.7/5 (86)
(86) When a firm is considered to be a "price taker" that means that the firm
(Multiple Choice)
4.8/5 (85)
(85) 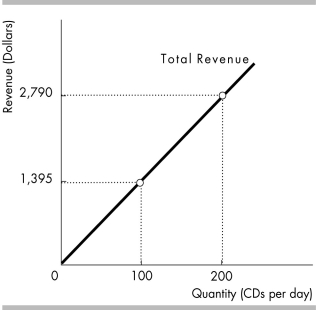 -The above figure shows the total revenue curve for Dizzy Discs. The demand curve for CDs sold by Dizzy Discs
 (Multiple Choice)
4.7/5 (84)
(84) 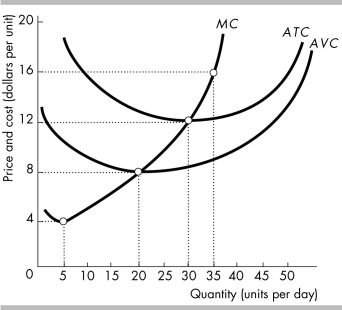 -The above figure shows the cost curves for a perfectly competitive firm. If all firms in the market have the same cost curves and the price equals $16 per unit,
 (Multiple Choice)
4.7/5 (86)
(86) In a perfectly competitive industry, the demand for a single firm's product is perfectly elastic
(Multiple Choice)
4.7/5 (77)
(77)  -The table above shows the total cost incurred by Sue's Coat Shop, a perfectly competitive firm. If the market price of a coat is $285, Sue's will maximize economic profit by selling ________ coats a day.
 (Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)