



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem439 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity449 Questions
Exam 6: Government Actions in Markets410 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices464 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs494 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly606 Questions
Exam 14: Monopolistic Competition320 Questions
Exam 15: Oligopoly280 Questions
Exam 16: Public Choices and Public Goods356 Questions
Exam 17: Externalities and the Environment284 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality354 Questions
Exam 20: Uncertainty and Information233 Questions
Exam 21: Extension A: Review11 Questions
Exam 22: Extension B: Review25 Questions
Exam 23: Extension C: Review14 Questions
Exam 24: Extension D: Review38 Questions
Exam 25: Extension E: Review11 Questions
Exam 26: Extension F: Review18 Questions
Select questions type


The market for fish is perfectly competitive. So, the price elasticity of demand for fish from a single fishing boat
(Multiple Choice)
4.8/5  (90)
(90) In the long-run equilibrium, perfectly competitive firms produce the level of output such that
(Multiple Choice)
4.9/5 (82)
(82)  -Fast Copy is a perfectly competitive firm. The figure above shows Fast Copy's cost curves. If the market price is 2 cents per page, what is Fast Copy's economic profit?
 (Multiple Choice)
4.9/5 (82)
(82)  -The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the new short-run equilibrium, the farm produces ________ bushels of corn and sells corn at ________ per bushel.
 (Multiple Choice)
4.8/5 (77)
(77) Explain the process that drives the economic profit to zero in the long run for a perfectly competitive firm.
(Essay)
4.7/5 (97)
(97) 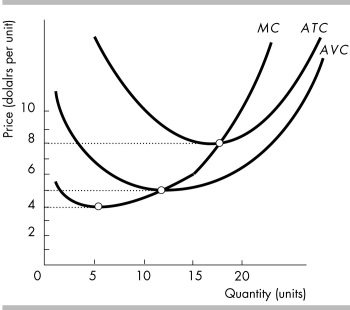 -In the above figure, at a price of $8, a perfectly competitive firm produces ________ and it ________.
 (Multiple Choice)
4.9/5 (79)
(79) Charlie's Chimps is a perfectly competitive firm that produces cuddly chimps for children. The market price of a chimp is $10, and Charlie's produces 100 chimps at a marginal cost of $9 a chimp. Charlie's ________.
(Multiple Choice)
4.9/5 (73)
(73) In a perfectly competitive market, a permanent increase in demand initially brings a higher price, economic
(Multiple Choice)
4.7/5 (67)
(67) If the donut industry is perfectly competitive and is in long-run equilibrium, then the price of a donut
(Multiple Choice)
4.8/5 (68)
(68)  -In the above figure, at any price between $8 per unit to $12 per unit, how many units will a profit-maximizing perfectly competitive firm produce?
 (Multiple Choice)
4.8/5 (67)
(67) 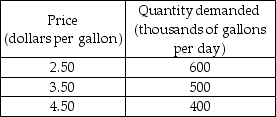 -The market for milk is perfectly competitive. There are 1,000 farms in the industry and the relationship between a typical farm's output and total costs is the same as in Problem 2. The market demand schedule for milk is shown in the table above.
a) What is a typical farm's supply schedule and what is the market supply schedule?
b) What is the market price? What quantity of milk is sold?
c) What is the output produced by each farm? What type of profit or loss is made by each farm?
d) Do farms enter or exit the market?
-The market for milk is perfectly competitive. There are 1,000 farms in the industry and the relationship between a typical farm's output and total costs is the same as in Problem 2. The market demand schedule for milk is shown in the table above.
a) What is a typical farm's supply schedule and what is the market supply schedule?
b) What is the market price? What quantity of milk is sold?
c) What is the output produced by each farm? What type of profit or loss is made by each farm?
d) Do farms enter or exit the market? (Essay)
4.9/5 (76)
(76) In the long run, if firms in a perfectly competitive market are incurring economic losses, then
(Multiple Choice)
4.7/5 (82)
(82) In the long run, perfectly competitive firms make zero economic profit (their owners earn a normal profit) because
(Multiple Choice)
5.0/5 (81)
(81) The demand for a product produced in a perfectly competitive market permanently increases. In the short run, the price
(Multiple Choice)
4.9/5 (74)
(74) If the price received by a perfectly competitive firm is less than its average variable cost, what will the firm do in the short run? Why?
(Essay)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)