



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem439 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity449 Questions
Exam 6: Government Actions in Markets410 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices464 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs494 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly606 Questions
Exam 14: Monopolistic Competition320 Questions
Exam 15: Oligopoly280 Questions
Exam 16: Public Choices and Public Goods356 Questions
Exam 17: Externalities and the Environment284 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality354 Questions
Exam 20: Uncertainty and Information233 Questions
Exam 21: Extension A: Review11 Questions
Exam 22: Extension B: Review25 Questions
Exam 23: Extension C: Review14 Questions
Exam 24: Extension D: Review38 Questions
Exam 25: Extension E: Review11 Questions
Exam 26: Extension F: Review18 Questions
Select questions type


In a perfectly competitive market, an increase in market demand
(Multiple Choice)
4.7/5  (74)
(74) Suppose firms in a perfectly competitive industry are making economic profits. As a result, I. new firms enter the industry.
II) the market price falls.
III) the economic profits of the existing firms decrease.
(Multiple Choice)
4.9/5 (87)
(87) Entry of new firms into a perfectly competitive market lowers the profits of the existing firms.
(True/False)
5.0/5 (83)
(83) 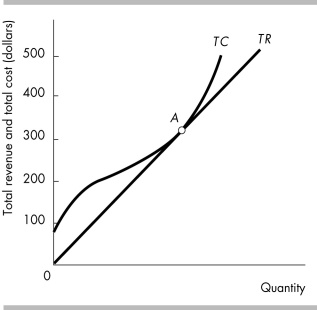 -In the figure above, a firm is operating at point A on the graph. At point A, the firm's average cost curve
 (Multiple Choice)
4.8/5 (91)
(91)  -The figure above shows depicts the marginal revenue and costs of a perfectly competitive firm. The price the firm charges is
 (Multiple Choice)
4.7/5 (80)
(80) A worldwide hops (a flowers used in brewing) shortage will make stouts, ales and other specialty microbrews more pricy in 2008. Gayle Goshie, a hops farmer, blames overproduction for hops' previously cheap place on the agricultural market. The glut pushed many hop farmers out business, which gradually helped hop prices recover. Suppose farming hops is a perfectly competitive market. Why would some hop farmers go out of business?
(Multiple Choice)
5.0/5 (81)
(81) 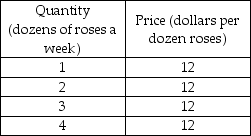 -Pete is a perfectly competitive rose grower. The above table gives quantities and the price for which Pete can sell his roses.
a) What is Pete's total revenue if he sells 1 dozen roses? 2 dozen roses? 3 dozen roses? 4 dozen roses?
b) What is the marginal revenue of the 2nd dozen roses sold? Of the 3rd dozen? Of the 4th dozen?
-Pete is a perfectly competitive rose grower. The above table gives quantities and the price for which Pete can sell his roses.
a) What is Pete's total revenue if he sells 1 dozen roses? 2 dozen roses? 3 dozen roses? 4 dozen roses?
b) What is the marginal revenue of the 2nd dozen roses sold? Of the 3rd dozen? Of the 4th dozen? (Essay)
4.9/5 (70)
(70) 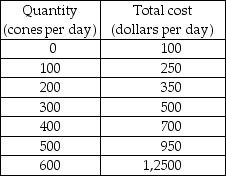 -Cory's is one of many ice cream stands in town. Cory's costs are shown in the table above.
a) If the market price of ice cream is $1.75 per cone, what is Cory's profit-maximizing quantity of cones?
b) If the market price of ice cream is $2.25 per cone, what is Cory's profit-maximizing quantity of coins?
c) If the market price of ice cream is $2.75 per cone, what is Cory's profit-maximizing quantity of coins?
d) Can you determine any points on Cory's supply curve?
-Cory's is one of many ice cream stands in town. Cory's costs are shown in the table above.
a) If the market price of ice cream is $1.75 per cone, what is Cory's profit-maximizing quantity of cones?
b) If the market price of ice cream is $2.25 per cone, what is Cory's profit-maximizing quantity of coins?
c) If the market price of ice cream is $2.75 per cone, what is Cory's profit-maximizing quantity of coins?
d) Can you determine any points on Cory's supply curve? (Essay)
5.0/5 (84)
(84) In perfect competition, the elasticity of demand for the product of a single firm is
(Multiple Choice)
4.9/5 (82)
(82) 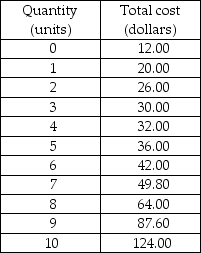 -Acme is a perfectly competitive firm. It has the total cost schedule given in the above table. Acme's product sells for $8.00 per unit. What amount of output is the most profitable and what is Acme's economic profit or economic loss?
 (Essay)
4.9/5 (77)
(77) A perfectly competitive firm produces so that its marginal cost equals the price.
(True/False)
4.8/5 (72)
(72) In the long run, perfectly competitive firms make zero economic profit, that is, their owners make a normal profit.
(True/False)
4.9/5 (76)
(76) The section of the marginal cost curve that lies above the average variable cost curve is
(Multiple Choice)
5.0/5 (89)
(89)  -The figure above shows a perfectly competitive firm. The firm will shut down in the short run if total fixed costs
 (Multiple Choice)
4.8/5 (72)
(72) 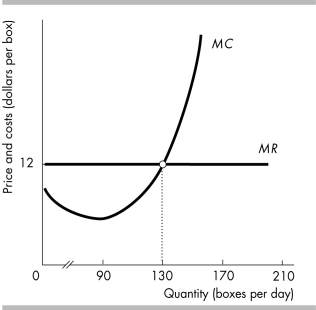 -Carol's Candies is producing 150 boxes of candy a day. Carol's marginal revenue and marginal cost curves are shown in the figure above. To increase her profit, Carol should
 (Multiple Choice)
4.7/5 (81)
(81) In a perfectly competitive market, many firms sell an identical product.
(True/False)
4.8/5 (78)
(78)  -The table above gives the total revenue and total cost for a perfectly competitive firm producing chocolate chip cookies. If the firm increases its output from 2 pounds of cookies to 3 pounds, the marginal revenue is ________ per pound of cookies.
 (Multiple Choice)
4.9/5 (72)
(72) 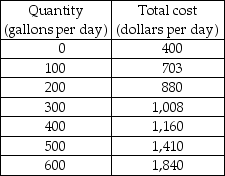 -Petunia's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Petunia's average variable, average total, and marginal cost curves.
b) Use your graphs to find Petunia's profit-maximizing output.
c) If Petunia maximizes her profit, how much profit does she make?
d) What is Petunia's shutdown point? What is her economic profit at the shut-down point?
e) Should Petunia shut down? Will farms with costs the same as Petunia's enter or exit the milk market? Explain.
-Petunia's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Petunia's average variable, average total, and marginal cost curves.
b) Use your graphs to find Petunia's profit-maximizing output.
c) If Petunia maximizes her profit, how much profit does she make?
d) What is Petunia's shutdown point? What is her economic profit at the shut-down point?
e) Should Petunia shut down? Will farms with costs the same as Petunia's enter or exit the milk market? Explain. (Essay)
4.8/5 (69)
(69) The short-run supply curve for a perfectly competitive firm is its marginal cost curve
(Multiple Choice)
4.8/5 (75)
(75) A perfectly competitive firm maximizes its profits by producing the amount of output such that
(Multiple Choice)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)