



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics479 Questions
Exam 2: The Economic Problem439 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity533 Questions
Exam 5: Efficiency and Equity449 Questions
Exam 6: Government Actions in Markets410 Questions
Exam 7: Global Markets in Action200 Questions
Exam 8: Utility and Demand364 Questions
Exam 9: Possibilities, Preferences, and Choices464 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs494 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly606 Questions
Exam 14: Monopolistic Competition320 Questions
Exam 15: Oligopoly280 Questions
Exam 16: Public Choices and Public Goods356 Questions
Exam 17: Externalities and the Environment284 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality354 Questions
Exam 20: Uncertainty and Information233 Questions
Exam 21: Extension A: Review11 Questions
Exam 22: Extension B: Review25 Questions
Exam 23: Extension C: Review14 Questions
Exam 24: Extension D: Review38 Questions
Exam 25: Extension E: Review11 Questions
Exam 26: Extension F: Review18 Questions
Select questions type


If a perfectly competitive market is in long-run equilibrium and there is a permanent decrease in demand, then
(Multiple Choice)
4.8/5  (86)
(86) The return that the entrepreneur can obtain in the best alternative business is called the
(Multiple Choice)
4.9/5 (77)
(77) As long as it does not shut down, a profit-maximizing perfectly competitive firm will
(Multiple Choice)
4.7/5 (88)
(88)  -The figure above portrays a total revenue curve for a perfectly competitive firm. The price of the product in this industry
 (Multiple Choice)
4.9/5 (78)
(78) In a perfectly competitive market in the short run, as the market demand increases, the firms ________ their output and their economic profit ________.
(Multiple Choice)
4.7/5 (78)
(78) 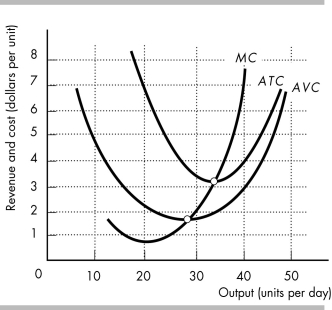 -The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a) how much will the firm produce?
b) how much is the firm's average total, average variable, and marginal costs?
c) how much is the firm's total, total variable, and total fixed costs?
d) how much is the firm's total revenue and economic profit?
e) what will happen in this market in the long run?
-The above figure shows the cost curves of a profit-maximizing perfectly competitive firm. If the price equals $7,
a) how much will the firm produce?
b) how much is the firm's average total, average variable, and marginal costs?
c) how much is the firm's total, total variable, and total fixed costs?
d) how much is the firm's total revenue and economic profit?
e) what will happen in this market in the long run? (Essay)
4.9/5 (75)
(75) In the long run, perfectly competitive firms make zero economic profit. This result is due mainly to the point that a perfectly competitive market has
(Multiple Choice)
4.8/5 (78)
(78) A worldwide hops (a flowers used in brewing) shortage will make stouts, ales and other specialty microbrews more pricy in 2008. A triple whammy of bad weather in Europe, an increase in the price of barley and a decrease in hops production in the U.S. has led to a price increase of 20 percent for the most widely grown varieties, to 80 percent for specialty hops. What is the effect of this hops shortage on a microbrewery's cost curves?
(Multiple Choice)
4.8/5 (68)
(68) In the short run, a perfectly competitive firm's economic profits
(Multiple Choice)
4.9/5 (71)
(71) Bob's Lawn Care Services is a perfectly competitive firm that currently mows 22 lawns a week. Bob's marginal cost exceeds the price he charges. Bob can increase his profit if he
(Multiple Choice)
4.9/5 (77)
(77) 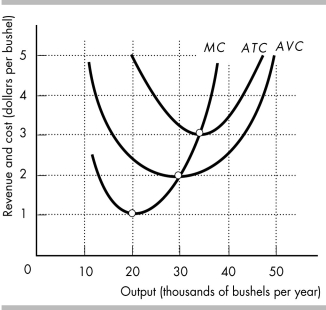 -The above diagram shows the cost curves for a perfectly competitive wheat farmer. At what price does the wheat farmer shut down?
 (Essay)
4.8/5 (83)
(83) In the long run, a perfectly competitive firm will exit a market when
(Multiple Choice)
4.9/5 (62)
(62)  -In the above figure, if the price is $10, a profit-maximizing perfectly competitive firm will
 (Multiple Choice)
4.9/5 (75)
(75) "A perfectly competitive firm is called a price maker because all the firms together must make the market price." Is the previous statement correct or incorrect? Briefly explain your answer.
(Essay)
4.8/5 (82)
(82)  -In the above figure, by increasing its output from Q1 to Q2, the firm
 (Multiple Choice)
4.8/5 (92)
(92) For a perfectly competitive firm, no matter how much the firm produces, price always equals
(Multiple Choice)
4.9/5 (93)
(93) The USDA maintains ethanol has an impact on food prices. "Higher ethanol production definitely and directly raises the price of corn," said USDA economist Ephraim Leibtag. In the long run in the corn market, what is true if the production of ethanol increases?
(Multiple Choice)
5.0/5 (86)
(86) Homer's Holesome Donuts has determined that its profit-maximizing quantity is 10,000 donuts per year. Homer's earns $12,000 in revenue from the sale of those donuts. Homer's has two costs. First he pays $16,000 in annual rental payments for its five-year lease on its store. Second Homer incurs an additional cost of $5,000 for ingredients. Homer's fixed cost is equal to
(Multiple Choice)
5.0/5 (90)
(90) All along the beach in San Diego, California are shops which rent boogie boards for $3 per hour. Tourists perceive that all rental boogie boards are identical and there are no restrictions on entry and exit in the boogie board market. Suppose Surf's Up is a boogie board rental shop. To maximize profits, Surf's Up would produce a quantity where:
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)