



 Chat with AI
Exam 7: A Closer Look at Overhead Costs

Exam 1: Management Accounting: Information for Creating Value and Managing Resources67 Questions
Exam 2: Management Accounting: Cost Terms and Concepts87 Questions
Exam 3: Cost Behaviour, Cost Drivers and Cost Estimation93 Questions
Exam 4: Product Costing Systems88 Questions
Exam 5: Process Costing and Operation Costing87 Questions
Exam 6: Service Costing91 Questions
Exam 7: A Closer Look at Overhead Costs99 Questions
Exam 8: Activity-Based Costing91 Questions
Exam 9: Budgeting Systems92 Questions
Exam 10: Standard Costs for Control: Direct Material and Direct Labour105 Questions
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead109 Questions
Exam 12: Managing and Reporting Performance102 Questions
Exam 13: Financial Performance Measures and Incentive Schemes93 Questions
Exam 14: Strategic Performance Measurement Systems80 Questions
Exam 15: Managing Suppliers and Customers90 Questions
Exam 16: Managing Costs and Quality92 Questions
Exam 17: Sustainability and Management Accounting76 Questions
Exam 18: Cost Volume Profit Analysis111 Questions
Exam 19: Information for Decisions: Relevant Costs and Benefits116 Questions
Exam 20: Pricing and Product Mix Decisions113 Questions
Exam 21: Information for Capital Expenditure Decisions125 Questions
Select questions type


The estimation of the quantity of a cost driver is called the denominator volume.
(True/False)
4.8/5  (73)
(73) Gallison Company's net profit under absorption costing was $15 000 higher than under variable costing. During the year, the company produced 20 000 units for total variable production costs of $80 000. If fixed manufacturing overhead was $40 000, how many units were sold?
(Multiple Choice)
4.8/5 (79)
(79) It is not necessary to take into account seasonal, cyclical and trend factors when estimating the normal level of capacity.
(True/False)
4.9/5 (59)
(59) Discuss the three main reasons for allocating indirect costs to responsibility centres.
(Essay)
4.8/5 (70)
(70) The Browning Company manufactures a single product; the standard costs per unit being variable manufacturing $8, fixed manufacturing $6. Selling and administrative costs are $2 per unit sold. The selling price is $20 per unit. Actual and budgeted fixed overhead is $900 000 for the year. Information about Browning's production activity for the year is: 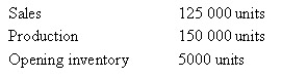 Assuming all information is provided above, the difference in profit between absorption and variable costing would be expected to be:
 (Multiple Choice)
4.9/5 (85)
(85) Variable costing is more useful than absorption costing for:
i. special order decisions
ii. short-term pricing of products
iii. long-term pricing of products
(Multiple Choice)
4.8/5 (60)
(60) The Browning Company manufactures a single product; the standard costs per unit being variable manufacturing $8, fixed manufacturing $6. Selling and administrative costs are $2 per unit sold. The selling price is $20 per unit. Actual and budgeted fixed overhead is $900,000 for the year. Information about Browning's production activity for the year is: 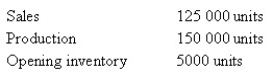 What is the profit under variable costing?
 (Multiple Choice)
4.8/5 (72)
(72) The following information about Monfort Manufacturing is available: 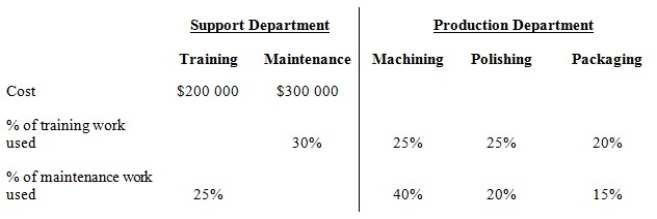 Using the direct method, the cost allocated from both of the support departments to Machining Department is:
 (Multiple Choice)
4.9/5 (86)
(86) Prior to allocating overheads to a product, it is necessary to allocate the costs of all support departments to the production departments.
(True/False)
4.7/5 (86)
(86) The production section of a firm is serviced by personnel and computing as follows: 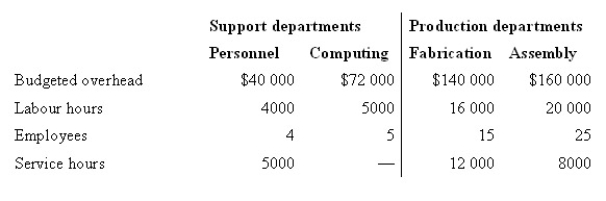 Personnel costs are allocated on the number of employees and computing costs on service hours. Overhead rates are based on labour hours. If the direct method is used to allocate support department costs, what is the overhead rate for the Assembly Department?
 (Multiple Choice)
4.8/5 (75)
(75) When a company is choosing between different types of volume based cost drivers, which of the following factors suggest the use of outputs as a cost driver?
i. The company has only one product.
ii. The company is labour intensive.
iii. The company uses large quantities of direct materials.
(Multiple Choice)
4.9/5 (76)
(76) The income of a company for a year on a variable costing basis is $85 000 and on an absorption costing basis is $73 000. Fixed costs per unit were the same in both the prior and current year ($1.20 per unit). What was the change in inventory over the year?
(Multiple Choice)
4.8/5 (75)
(75) The following information relates to the Moonie Park Manufacturing Company for the year 2012. 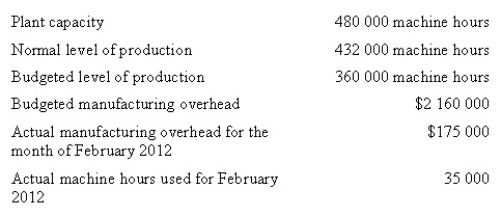 What would be the amount of underapplied or overapplied overhead at the end of the month if overhead rates were calculated based on practical capacity, normal capacity and budgeted capacity respectively.
 (Multiple Choice)
4.8/5 (88)
(88) Consider the following statements regarding cost allocation.
i. Allocation of budgeted costs is preferred to actual cost as this minimises the possibility that the actions of one user department will affect the costs allocated to another user department.
ii. Allocation of standard budgeted rates is preferred, so the user department does not have to bear the inefficiencies of support departments.
iii. Knowing the standard rates in advance allows the user departments to plan their activities with greater certainty.
Which statement/s is/are true?
(Multiple Choice)
5.0/5 (65)
(65) When estimating the costs of a cost object, direct costs are allocated and indirect costs are traced to the object.
(True/False)
4.8/5 (82)
(82) Appleford Ltd is a furniture manufacturer. It has a small range of products. Its manufacturing processes are characterised by a high level of automation. Appleford Ltd decides to choose a volume-based cost driver for its indirect manufacturing costs. Which of the following cost drivers is most appropriate?
(Multiple Choice)
4.9/5 (88)
(88) The support department cost allocation method that completely ignores reciprocal services between support departments is called the:
(Multiple Choice)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)