



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand697 Questions
Exam 5: Elasticity and Its Application594 Questions
Exam 6: Supply, Demand, and Government Policies645 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: the Costs of Taxation513 Questions
Exam 9: Application: International Trade492 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System549 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition580 Questions
Exam 17: Oligopoly488 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty455 Questions
Exam 21: The Theory of Consumer Choice431 Questions
Exam 22: Frontiers of Microeconomics440 Questions
Exam 23: Measuring a Nations Income520 Questions
Exam 24: Measuring the Cost of Living529 Questions
Exam 25: Production and Growth505 Questions
Exam 26: Saving, Investment, and the Financial System564 Questions
Exam 27: The Basic Tools of Finance500 Questions
Exam 28: Unemployment678 Questions
Exam 29: The Monetary System515 Questions
Exam 30: Money Growth and Inflation481 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 32: A Macroeconomic Theory of the Open Economy475 Questions
Exam 33: Aggregate Demand and Aggregate Supply562 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand508 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment491 Questions
Exam 36: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


When the price of a good is lower than the equilibrium price,
(Multiple Choice)
4.9/5  (78)
(78) Buyers are able to buy all they want to buy and sellers are able to sell all they want to sell at
(Multiple Choice)
4.9/5 (86)
(86) An increase in the number of college scholarships issued by private foundations would
(Multiple Choice)
4.9/5 (87)
(87) Table 4-14
The table below shows the quantities demanded of milk per month by four families at various prices. 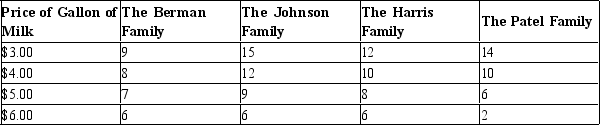 -Refer to Table 4-14. If the four families listed are the only demanders in this market and the price of a gallon of milk is $4.00, what is the market quantity demanded?
 (Short Answer)
4.9/5 (74)
(74) Table 4-6  -Refer to Table 4-6. If these are the only four sellers in the market, then the market quantity supplied at a price of $4 is
 (Multiple Choice)
4.8/5 (83)
(83) In a perfectly competitive market, the goods offered for sale are all exactly the same.
(True/False)
4.8/5 (78)
(78) Figure 4-25
The graph below pertains to the supply of paper to colleges and universities.  -Refer to Figure 4-25. All else equal, sellers expecting the price of paper to decrease next month when many college students leave campuses for the summer would cause a current move from
 (Multiple Choice)
4.8/5 (88)
(88) When quantity demanded exceeds quantity supplied at the current market price, the market has a shortage, and market price will likely rise in the future to eliminate the shortage.
(True/False)
4.9/5 (93)
(93) Figure 4-27
Panel (a) Panel (b) 
 Panel (c) Panel (d)

 -Refer to Figure 4-27. Which of the four panels illustrates an increase in quantity demanded?
Panel (c) Panel (d)
-Refer to Figure 4-27. Which of the four panels illustrates an increase in quantity demanded? (Multiple Choice)
4.9/5 (74)
(74) Table 4-15
The following table shows the number of cases of water each seller is willing to sell at the prices listed.  -Refer to Table 4-15. Assuming these are the only four suppliers in this market, the function for market supply can be written as QS=
 (Short Answer)
4.9/5 (94)
(94) When the market price is below the equilibrium price, suppliers are unable to sell all they want to sell.
(True/False)
4.8/5 (98)
(98) Figure 4-22  -Refer to Figure 4-22. What is the equilibrium price in this market?
 (Multiple Choice)
4.7/5 (88)
(88) Which of the following events would unambiguously cause an increase in the equilibrium price of cotton shirts?
(Multiple Choice)
4.7/5 (87)
(87) When quantity demanded decreases at every possible price, the demand curve has
(Multiple Choice)
4.7/5 (69)
(69) When quantity demanded has increased at every price, it might be because
(Multiple Choice)
4.9/5 (80)
(80) Figure 4-5  -Refer to Figure 4-5. Which of the following would cause the demand curve to shift from Demand C to Demand A in the market for DVDs?
 (Multiple Choice)
4.7/5 (78)
(78) The law of demand states that, other things equal, when the price of a good rises, the quantity demanded of the good falls, and when the price falls, the quantity demanded rises.
(True/False)
5.0/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)