



 Chat with AI
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


In a world where the CAPM holds, which one of the following is not a true statement regarding the capital market line?
(Multiple Choice)
4.9/5  (78)
(78) If the beta of the market index is 1 and the standard deviation of the market index increases from 12% to 18%, what is the new beta of the market index?
(Multiple Choice)
4.9/5 (76)
(76) One of the main problems with the arbitrage pricing theory is ________.
(Multiple Choice)
4.8/5 (89)
(89) In a study conducted by Jagannathan and Wang, it was found that the performance of beta in explaining security returns could be considerably enhanced by:
I. Including the unsystematic risk of a stock
II. Including human capital in the market portfolio
III. Allowing for changes in beta over time
(Multiple Choice)
4.9/5 (77)
(77) Research has revealed that regardless of what the current estimate of a firm's beta is, beta will tend to move closer to ________ over time.
(Multiple Choice)
4.9/5 (86)
(86) Which of the following variables do Fama and French claim do a better job explaining stock returns than beta?
I. Book-to-market ratio
II. Unexpected change in industrial production
III. Firm size
(Multiple Choice)
4.9/5 (91)
(91) According to the CAPM, what is the market risk premium given an expected return on a security of 13.6%, a stock beta of 1.2, and a risk-free interest rate of 4%?
(Multiple Choice)
4.9/5 (79)
(79) You invest $600 in security A with a beta of 1.5 and $400 in security B with a beta of .90. The beta of this portfolio is ________.
(Multiple Choice)
4.7/5 (82)
(82) In a simple CAPM world which of the following statements is (are) correct?
I. All investors will choose to hold the market portfolio, which includes all risky assets in the world.
II. Investors' complete portfolio will vary depending on their risk aversion.
III. The return per unit of risk will be identical for all individual assets.
IV. The market portfolio will be on the efficient frontier, and it will be the optimal risky portfolio.
(Multiple Choice)
4.7/5 (79)
(79) In a single-factor market model the beta of a stock ________.
(Multiple Choice)
4.9/5 (84)
(84) 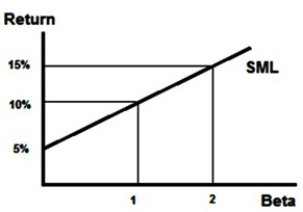 What is the expected return for a portfolio with a beta of .5?
 (Multiple Choice)
4.8/5 (89)
(89) According to the CAPM, which of the following is not a true statement regarding the market portfolio.
(Multiple Choice)
4.9/5 (78)
(78) Building a zero-investment portfolio will always involve ________.
(Multiple Choice)
4.8/5 (75)
(75) There are two independent economic factors, M1 and M2. The risk-free rate is 5%, and all stocks have independent firm-specific components with a standard deviation of 25%. Portfolios A and B are well diversified. Given the data below, which equation provides the correct pricing model?
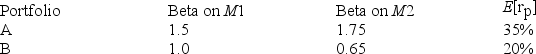
(Multiple Choice)
4.9/5 (92)
(92) According to the CAPM, investors are compensated for all but which of the following?
(Multiple Choice)
4.9/5 (90)
(90) The expected return on the market portfolio is 15%. The risk-free rate is 8%. The expected return on SDA Corp. common stock is 16%. The beta of SDA Corp. common stock is 1.25. Within the context of the capital asset pricing model, ________.
(Multiple Choice)
4.7/5 (69)
(69) Investors require a risk premium as compensation for bearing ________.
(Multiple Choice)
4.9/5 (91)
(91) According to capital asset pricing theory, the key determinant of portfolio returns is ________.
(Multiple Choice)
4.9/5 (79)
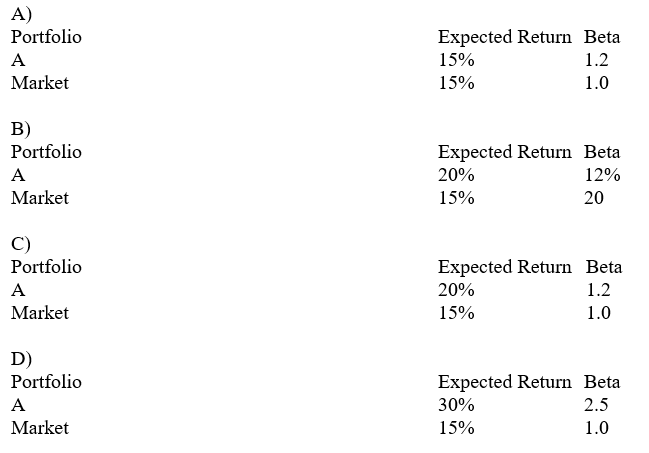
(79) If the simple CAPM is valid and all portfolios are priced correctly, which of the situations below is possible? Consider each situation independently, and assume the risk-free rate is 5%.
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)