



 Chat with AI
Exam 19: International Diversification

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


The manager of Quantitative International Fund uses EAFE as a benchmark. Last year's performance for the fund and the benchmark were as follows:
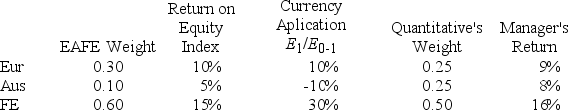 Calculate Quantitative's currency selection return contribution.
Free
(Multiple Choice)
4.8/5  (83)
(83) Correct Answer: Verified
B
Assume there is a fixed exchange rate between the Canadian and U.S. dollar. The expected return and standard deviation of return on the U.S. stock market are 18% and 15%, respectively. The expected return and standard deviation on the Canadian stock market are 13% and 20%, respectively. The covariance of returns between the U.S. and Canadian stock markets is 1.5%.
If you invested 50% of your money in the Canadian stock market and 50% in the U.S. stock market, the expected return on your portfolio would be
Free
(Multiple Choice)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedD
"ADRs" stands for ________, and "WEBS" stands for ________.
Free
(Multiple Choice)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedD
You are a U.S. investor who purchased British securities for 2,000 pounds, one year ago when the British pound cost $1.50. No dividends were paid on the British securities in the past year. Your total return based on U.S. dollars was ________ if the value of the securities is now 2,400 pounds and the pound is worth $1.60.
(Multiple Choice)
4.8/5 (78)
(78) The performance of an internationally-diversified portfolio may be affected by
(Multiple Choice)
4.9/5 (81)
(81) The manager of Quantitative International Fund uses EAFE as a benchmark. Last year's performance for the fund and the benchmark were as follows:
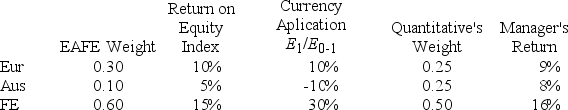 Calculate Quantitative's country selection return contribution.
 (Multiple Choice)
4.8/5 (69)
(69) Suppose the 1-year risk-free rate of return in the U.S. is 2% and the 1-year risk-free rate of return in Mexico is 8%. The current exchange rate is 1 peso = U.S. $.051. A 1-year future exchange rate of ________ for the peso would make a U.S. investor indifferent between investing in the U.S. security and investing in the Mexican security.
(Multiple Choice)
4.8/5 (84)
(84) The manager of Quantitative International Fund uses EAFE as a benchmark. Last year's performance for the fund and the benchmark were as follows:
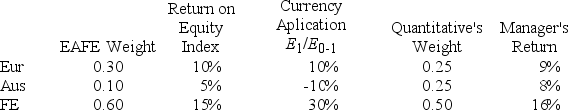 Calculate Quantitative's stock selection return contribution.
 (Multiple Choice)
4.9/5 (73)
(73) Assume there is a fixed exchange rate between the Yen and U.S. dollar. The expected return and standard deviation of return on the U.S. stock market are 21% and 15%, respectively. The expected return and standard deviation on the Japanese stock market are 13% and 12%, respectively. The covariance of returns between the U.S. and Japanese stock market is 2.5%.
If you invested 60% of your money in the Japanese stock market and 40% in the U.S. stock market, the expected return on your portfolio would be
(Multiple Choice)
4.7/5 (84)
(84) When an investor adds international stocks to his or her U.S. stock portfolio,
(Multiple Choice)
4.7/5 (79)
(79) The present exchange rate is C$ = U.S. $0.78. The 1-year future rate is C$ = U.S. $0.76. The yield on a 1-year U.S. bill is 4%. A yield of ________ on a 1-year Canadian bill will make an investor indifferent between investing in the U.S. bill and the Canadian bill.
(Multiple Choice)
4.7/5 (69)
(69) The ________ index is a widely used index of non-U.S. stocks.
(Multiple Choice)
4.9/5 (73)
(73) The straightforward generalization of the simple CAPM to international stocks is problematic because
(Multiple Choice)
4.9/5 (79)
(79) Using local currency returns, the S&P 500 has the highest correlation with
(Multiple Choice)
4.7/5 (91)
(91) Assume there is a fixed exchange rate between the Canadian and U.S. dollar. The expected return and standard deviation of return on the U.S. stock market are 18% and 15%, respectively. The expected return and standard deviation on the Canadian stock market are 13% and 20%, respectively. The covariance of returns between the U.S. and Canadian stock markets is 1.5%.
If you invested 50% of your money in the Canadian stock market and 50% in the U.S. stock market, the expected return on your portfolio would be
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)