



 Chat with AI
Exam 15: Options Markets

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


The potential loss for a writer of a naked call option on a stock is ________.

Free
(Multiple Choice)
5.0/5  (85)
(85) Correct Answer: Verified
D
You purchase one MBI July 120 call contract (equaling 100 shares) for a premium of $5. You hold the option until the expiration date, when MBI stock sells for $123 per share. You will realize a ________ on the investment.
Free
(Multiple Choice)
4.8/5 (77)
(77) Correct Answer:Verified
VerifiedB
A "bet" option is also called a ________ option.
Free
(Multiple Choice)
4.8/5 (76)
(76) Correct Answer:Verified
VerifiedC
What strategy could be considered insurance for an investment in a portfolio of stocks?
(Multiple Choice)
4.8/5 (72)
(72) You write a put option on a stock. The profit at contract maturity of the option position is ________, where X equals the option's strike price, ST is the stock price at contract expiration, and P0 is the original premium of the put option.
(Multiple Choice)
4.8/5 (80)
(80) You invest in the stock of Valleyview Corp. and purchase a put option on Valleyview Corp. This strategy is called a ________.
(Multiple Choice)
4.8/5 (77)
(77) Which of the following strategies makes a profit if the stock price stays stable?
(Multiple Choice)
4.9/5 (71)
(71) The May 17, 2015, price quotation for a Boring call option with a strike price of $50 due to expire in November is $20.80, while the stock price of Boring is $69.80. The premium on one Boring November 50 call contract is ________.
(Multiple Choice)
4.7/5 (81)
(81) Which strategy benefits from upside price movement and has some protection should the price of the security fall?
(Multiple Choice)
4.9/5 (89)
(89) You purchase one MBI March 120 put contract for a put premium of $10. The maximum profit that you could gain from this strategy is ________.
(Multiple Choice)
4.9/5 (76)
(76) If the gross profit is positive and the net profit is negative, you will ________.
(Multiple Choice)
4.9/5 (83)
(83) ______ option can only be exercised on the expiration date.
(Multiple Choice)
4.9/5 (80)
(80) You purchase one MBI July 120 put contract (equaling 100 shares) for a premium of $3. You hold the option until the expiration date, when MBI stock sells for $123 per share. You will realize a ________ on the investment.
(Multiple Choice)
4.9/5 (75)
(75) ________ is the most risky transaction to undertake in the stock-index option markets if the stock market is expected to fall substantially after the transaction is completed.
(Multiple Choice)
4.8/5 (72)
(72) You are cautiously bullish on the common stock of the Wildwood Corporation over the next several months. The current price of the stock is $50 per share. You want to establish a bullish money spread to help limit the cost of your option position. You find the following option quotes:
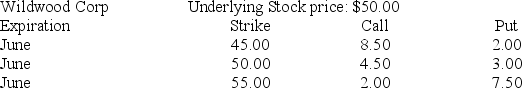 To establish a bull money spread with puts, you would ________.
 (Multiple Choice)
4.9/5 (80)
(80) A put option on Dr. Pepper Snapple Group, Inc., has an exercise price of $45. The current stock price is $41. The put option is ________.
(Multiple Choice)
4.8/5 (86)
(86) You sell one MBI July 90 call contract for a premium of $4 and two puts for a premium of $3 each. You hold the position until the expiration date, when MBI stock sells for $95 per share. You will realize a ________ on this strip.
(Multiple Choice)
4.7/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)