



 Chat with AI
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


Security X has an expected rate of return of 13% and a beta of 1.15. The risk-free rate is 5%, and the market expected rate of return is 15%. According to the capital asset pricing model, security X is ________.

Free
(Multiple Choice)
4.7/5  (76)
(76) Correct Answer: Verified
B
Consider the multifactor APT with two factors. Portfolio A has a beta of .5 on factor 1 and a beta of 1.25 on factor 2. The risk premiums on the factor 1 and 2 portfolios are 1% and 7%, respectively. The risk-free rate of return is 7%. The expected return on portfolio A is ________ if no arbitrage opportunities exist.
Free
(Multiple Choice)
4.8/5 (82)
(82) Correct Answer:Verified
VerifiedC
If all investors become more risk averse, the SML will ________ and stock prices will ________.
Free
(Multiple Choice)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedC
The risk-free rate is 4%. The expected market rate of return is 11%. If you expect stock X with a beta of .8 to offer a rate of return of 12%, then you should ________.
(Multiple Choice)
4.8/5 (82)
(82) 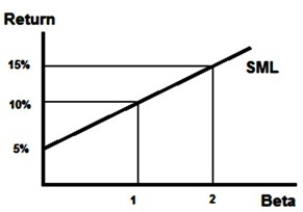 What is the expected return on the market?
Standard deviation of portfolio returns is a measure of ________.
(Multiple Choice)
4.9/5 (64)
(64) A stock has a beta of 1.3. The systematic risk of this stock is ________ the stock market as a whole.
(Multiple Choice)
4.7/5 (83)
(83) According to the capital asset pricing model, fairly priced securities have ________.
(Multiple Choice)
4.8/5 (79)
(79) In the context of the capital asset pricing model, the systematic measure of risk is captured by ________.
(Multiple Choice)
4.7/5 (73)
(73) Assume that both X and Y are well-diversified portfolios and the risk-free rate is 8%. Portfolio X has an expected return of 14% and a beta of 1. Portfolio Y has an expected return of 9.5% and a beta of .25. In this situation, you would conclude that portfolios X and Y ________.
(Multiple Choice)
4.9/5 (81)
(81) The variance of the return on the market portfolio is .04 and the expected return on the market portfolio is 20%. If the risk-free rate of return is 10%, the market degree of risk aversion, A, is ________.
(Multiple Choice)
4.8/5 (85)
(85) Security A has an expected rate of return of 12% and a beta of 1.1. The market expected rate of return is 8%, and the risk-free rate is 5%. The alpha of the stock is ________.
(Multiple Choice)
4.9/5 (81)
(81) Two investment advisers are comparing performance. Adviser A averaged a 20% return with a portfolio beta of 1.5, and adviser B averaged a 15% return with a portfolio beta of 1.2. If the T-bill rate was 5% and the market return during the period was 13%, which adviser was the better stock picker?
(Multiple Choice)
4.8/5 (76)
(76) Consider two stocks, A and B. Stock A has an expected return of 10% and a beta of 1.2. Stock B has an expected return of 14% and a beta of 1.8. The expected market rate of return is 9% and the risk-free rate is 5%. Security ________ would be considered the better buy because ________.
(Multiple Choice)
4.7/5 (82)
(82) You consider buying a share of stock at a price of $25. The stock is expected to pay a dividend of $1.50 next year, and your advisory service tells you that you can expect to sell the stock in 1 year for $28. The stock's beta is 1.1, rf is 6%, and E[rm] = 16%. What is the stock's abnormal return?
(Multiple Choice)
5.0/5 (90)
(90) According to the capital asset pricing model, in equilibrium ________.
(Multiple Choice)
4.9/5 (98)
(98) Consider the capital asset pricing model. The market degree of risk aversion, A, is 3. The risk premium is 2.25%. If the risk-free rate of return is 4%, the expected return on the market portfolio is ________.
(Multiple Choice)
4.8/5 (94)
(94) Which of the following are assumptions of the simple CAPM model?
I. Individual trades of investors do not affect a stock's price.
II. All investors plan for one identical holding period.
III. All investors analyze securities in the same way and share the same economic view of the world.
IV. All investors have the same level of risk aversion.
(Multiple Choice)
4.8/5 (80)
(80) The expected return of the risky-asset portfolio with minimum variance is ________.
(Multiple Choice)
4.9/5 (99)
(99) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)