



 Chat with AI
Exam 17: Futures Markets and Risk Management

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


The most actively traded interest rate futures contract is for ________.

Free
(Multiple Choice)
4.8/5  (63)
(63) Correct Answer: Verified
D
The ________ is among the world's largest derivatives exchanges and operates a fully electronic trading and clearing platform.
Free
(Multiple Choice)
4.9/5 (91)
(91) Correct Answer:Verified
VerifiedD
On Monday morning you sell one June T-bond futures contract at $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700, and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer the following questions.
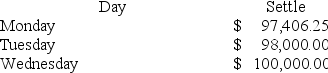 After Monday's close the balance on your margin account will be ________.
Free
(Multiple Choice)
4.9/5 (77)
(77) Correct Answer:Verified
VerifiedC
A stock index spot price is $1,287. The zero coupon interest rate is 3.8%. What is the potential arbitrage profit if the 6-month futures contract on the index is priced at $1,350?
(Multiple Choice)
4.9/5 (53)
(53) A 1-year gold futures contract is selling for $1,645. Spot gold prices are $1,592 and the 1-year risk-free rate is 3%.
Based on the above data, which of the following set of transactions will yield positive riskless arbitrage profits?
(Multiple Choice)
4.8/5 (81)
(81) Which one of the following exploits differences between actual future prices and their theoretically correct parity values?
(Multiple Choice)
4.8/5 (72)
(72) The swap market is a huge component of the derivatives market, with around ________ in interest rate and exchange rate swap agreements outstanding.
(Multiple Choice)
4.9/5 (64)
(64) On January 1, you sold one April S&P 500 Index futures contract at a futures price of 1,300. If the April futures price is 1,250 on February 1, your profit would be ________ if you close your position. (The contract multiplier is 250.)
(Multiple Choice)
4.9/5 (81)
(81) The fact that the exchange is the counterparty to every futures contract issued is important because it eliminates ________ risk.
(Multiple Choice)
4.8/5 (77)
(77) The open interest on silver futures at a particular time is the number of ________.
(Multiple Choice)
4.9/5 (72)
(72) On May 21, 2012, you could have purchased a futures contract from Intrade for a price of $5.70 that would pay you $10 if Barack Obama won the 2012 presidential election. This tells you ________.
(Multiple Choice)
4.8/5 (77)
(77) A short hedge is a simultaneous ________ position in the spot market and a ________ position in the futures market.
(Multiple Choice)
4.8/5 (83)
(83) The spot price of a futures contract is different than the price for which an investor can buy the underlying commodity for immediate delivery. This represents an opportunity for ________.
(Multiple Choice)
4.9/5 (66)
(66) A long hedge is a simultaneous ________ position in the spot market and a ________ position in the futures market.
(Multiple Choice)
4.8/5 (87)
(87) In the context of a futures contract, the basis is defined as ________.
(Multiple Choice)
4.8/5 (81)
(81) A hypothetical futures contract on a nondividend-paying stock with a current spot price of $100 has a maturity of 1 year. If the T-bill rate is 5%, what should the futures price be?
(Multiple Choice)
4.8/5 (74)
(74) You purchase an interest rate futures contract that has an initial margin requirement of 15% and a futures price of $115,098. The contract has a $100,000 underlying par value bond. If the futures price falls to $108,000, you will experience a ________ loss on your money invested.
(Multiple Choice)
4.8/5 (81)
(81) Initial margin is usually set in the region of ________ of the total value of a futures contract.
(Multiple Choice)
5.0/5 (83)
(83) A farmer sells futures contracts at a price of $2.75 per bushel. The spot price of corn is $2.55 at contract expiration. The farmer harvested 12,500 bushels of corn and sold futures contracts on 10,000 bushels of corn.
What are the farmer's proceeds from the sale of corn?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)