



 Chat with AI
Exam 17: Futures Markets and Risk Management

Exam 1: Investments: Background and Issues79 Questions
Exam 2: Asset Classes and Financial Instruments85 Questions
Exam 3: Securities Markets94 Questions
Exam 4: Mutual Funds and Other Investment Companies90 Questions
Exam 5: Risk, Return, and the Historical Record89 Questions
Exam 6: Efficient Diversification89 Questions
Exam 7: Capital Asset Pricing and Arbitrage Pricing Theory89 Questions
Exam 8: The Efficient Market Hypothesis92 Questions
Exam 9: Behavioral Finance and Technical Analysis89 Questions
Exam 10: Bond Prices and Yields96 Questions
Exam 11: Managing Bond Portfolios90 Questions
Exam 12: Macroeconomic and Industry Analysis93 Questions
Exam 13: Equity Valuation94 Questions
Exam 14: Financial Statement Analysis88 Questions
Exam 15: Options Markets91 Questions
Exam 16: Option Valuation90 Questions
Exam 17: Futures Markets and Risk Management92 Questions
Exam 18: Evaluating Investment Performance78 Questions
Exam 19: International Diversification50 Questions
Exam 20: Hedge Funds65 Questions
Exam 21: Taxes, Inflation, and Investment Strategy74 Questions
Exam 22: Investors and the Investment Process86 Questions
Select questions type


The current level of the S&P 500 is 1,250. The dividend yield on the S&P 500 is 3%. The risk-free interest rate is 6%. The futures price quote for a contract on the S&P 500 due to expire 6 months from now should be ________.
(Multiple Choice)
4.8/5  (62)
(62) On Monday morning you sell one June T-bond futures contract at $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700, and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer the following questions.
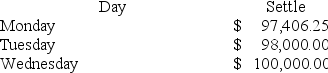 At the close of day on Tuesday your cumulative rate of return on your investment is ________.
 (Multiple Choice)
4.8/5 (70)
(70) A hypothetical futures contract on a nondividend-paying stock with a current spot price of $100 has a maturity of 4 years. If the T-bill rate is 7%, what should the futures price be?
(Multiple Choice)
4.8/5 (76)
(76) In the futures market the short position's loss is ________ the long position's gain.
(Multiple Choice)
4.8/5 (68)
(68) Approximately ________ of futures contracts result in actual delivery.
(Multiple Choice)
4.7/5 (82)
(82) Today's futures markets are dominated by trading in ________ contracts.
(Multiple Choice)
4.7/5 (72)
(72) An investor would want to ________ to hedge a long position in Treasury bonds.
(Multiple Choice)
4.7/5 (78)
(78) A speculator will often prefer to buy a futures contract rather than the underlying asset because:
I. Gains in futures contracts can be larger due to leverage.
II. Transaction costs in futures are typically lower than those in spot markets.
III. Futures markets are often more liquid than the markets of the underlying commodities.
(Multiple Choice)
4.9/5 (79)
(79) A bank has made long-term fixed-rate mortgages and has financed them with short-term deposits. To hedge out its interest rate risk, the bank could ________.
(Multiple Choice)
4.9/5 (76)
(76) You are currently long in a futures contract. You instruct a broker to enter the short side of a futures contract to close your position. This is called ________.
(Multiple Choice)
4.8/5 (75)
(75) ________ are likely to close their positions before the expiration date, while ________ are likely to make or take delivery.
(Multiple Choice)
5.0/5 (88)
(88) From the perspective of determining profit and loss, the long futures position most closely resembles a levered investment in a ________.
(Multiple Choice)
5.0/5 (92)
(92) On Monday morning you sell one June T-bond futures contract at $97,843.75. The contract's face value is $100,000. The initial margin requirement is $2,700, and the maintenance margin requirement is $2,000 per contract. Use the following price data to answer the following questions.
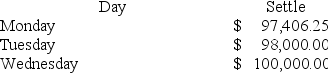 The cumulative rate of return on your investment after Wednesday is a ________.
 (Multiple Choice)
4.8/5 (76)
(76) The only money exchanged by both the long and short at the creation of a futures contract is called the ________.
(Multiple Choice)
4.8/5 (83)
(83) Investors who take short positions in futures contract agree to ________ delivery of the commodity on the delivery date, and those who take long positions agree to ________ delivery of the commodity.
(Multiple Choice)
4.9/5 (82)
(82) Which of the following provides the profit to a short position at contract maturity?
(Multiple Choice)
4.8/5 (79)
(79) A company that mines bauxite, an aluminum ore, decides to short aluminum futures. This is an example of ________ to limit its risk.
(Multiple Choice)
4.9/5 (92)
(92) Which of the following provides the profit to a long position at contract maturity?
(Multiple Choice)
4.8/5 (83)
(83) The CME weather futures contract is an example of ________.
(Multiple Choice)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)