



 Chat with AI
Exam 14: Accounts Payable and Other Liabilities

Exam 1: The Role of the Public Accountant in the American Economy45 Questions
Exam 2: Professional Standards62 Questions
Exam 3: Professional Ethics62 Questions
Exam 4: Legal Liability of Cpas56 Questions
Exam 5: Audit Evidence and Documentation82 Questions
Exam 6: Planning the Audit; Linking Audit Procedures to Risk78 Questions
Exam 7: Internal Control92 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment63 Questions
Exam 9: Audit Sampling83 Questions
Exam 10: Cash and Financial Investments61 Questions
Exam 11: Accounts Receivable, Notes Receivable, and Revenue64 Questions
Exam 12: Inventories and Cost of Goods Sold59 Questions
Exam 13: Property, Plant, and Equipment: Depreciation and Depletion39 Questions
Exam 14: Accounts Payable and Other Liabilities50 Questions
Exam 15: Debt and Equity Capital40 Questions
Exam 16: Auditing Operations and Completing the Audit69 Questions
Exam 17: Auditors Report62 Questions
Exam 18: Integrated Audits of Public Companies43 Questions
Exam 19: Additional Assurance Services: Historical Financial Information60 Questions
Exam 20: Additional Assurance Services: Other Information51 Questions
Exam 21: Internal, Operational, and Compliance Auditing48 Questions
Select questions type


Assume that the auditors are concerned about disbursement transactions that have been recorded for improper amounts. Which procedure(s) would possibly identify these transactions? Item Trace fom source documents to journals Vouch from joumal to source documents A. No No B. No Yes C. Yes No D. Yes Yes
(Multiple Choice)
4.9/5  (83)
(83) Which of the following assertions is of principle concern to the auditors in the examination of accounts payable?
(Multiple Choice)
4.7/5 (90)
(90) When an auditor finds a debit to accounts payable, which of the following accounts is most likely to be credited?
(Multiple Choice)
4.8/5 (81)
(81) Which statement is correct with respect to accounts payable confirmations?
(Multiple Choice)
4.7/5 (80)
(80) Auditors generally consider the evidence regarding accounts payable in the client's possession as more reliable than that for accounts receivable.
(True/False)
4.7/5 (66)
(66) Accounts payable generally present the auditors with difficult valuation problems.
(True/False)
5.0/5 (92)
(92) The confirmation of existing accounts payable does not prove the completeness of recorded accounts payable.
(True/False)
4.8/5 (81)
(81) Overstatement of financial results can involve failure to record a transaction.
(True/False)
4.8/5 (80)
(80) A major concern of the auditors is obtaining evidence about the completeness of recorded accounts payable.
a. Describe the reason that the auditors are concerned with the completeness of accounts payable.
b. Describe three ways in which the auditors establish the completeness of accounts payable.
(Essay)
4.9/5 (82)
(82) The primary objective of the auditors' examination of accounts payable is to determine whether payments are made on a timely basis.
(True/False)
4.7/5 (79)
(79) Based on the company and its environment, including its internal control, the auditors assessed the risk of material misstatements to the financial statements, whether due to error or fraud, and designed the nature, timing, and extent of further audit procedures to be performed.
As a result of conducting the above risk assessment procedures, the audit plan for year 2 includes the following changes from the audit plan for year 1. The company has a calendar year-end and operates only on weekdays.
In conducting the audit procedures for the search for unrecorded liabilities, the materiality/scope for this area was assessed by the auditors at $6,000. Adjustments are only recorded for items equal to, or exceeding materiality. The last day of fieldwork is estimated to be February 1, year 3.
For the items reflected in the following check register, which are not recorded in the accounts payable subsidiary ledger at December 31, year 2, determine if each potential liability is recorded in the proper accounting period and also determine the amount that should be journalized, if any. If no action is required, you must enter $0.
For each of the check numbers in the table below, double-click on each of the associated shaded cells and select from the lists provided if any action or adjustment is required, as well as the dollar value of the required adjustment. Each selection may be used once, more than once, or not at all.
Check Register 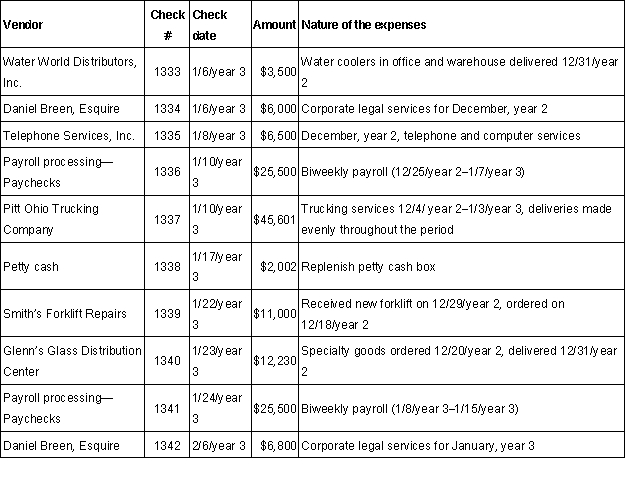 Check\# Adjustment Needed? Amount 1333 1334 1335 1336 1337 1338 1339 1340 1341 1342 Selection list for adjustment needed No\nobreakspaceaction\nobreakspacerequired Adjustment Selection list for amount \ 0 \ 4,413 \ 7,650 \ 12,750 \ 2,002 \ 6,000 \ 9,900 \ 25,500 \ 2,970 \ 6,500 \ 11,000 \ 41,188 \ 3,500 \ 6,800 \ 12,230 \ 45,601
 (Essay)
4.9/5 (83)
(83) It is more important to maintain effective internal control over accounts payable as it is to maintain effective internal control over accounts receivable.
(True/False)
4.8/5 (65)
(65) The auditors may decide to confirm accounts payable on an audit engagement.
a. Describe two reasons why the confirmation of accounts payable is not a presumptively mandatory auditing procedure.
b. Describe the audit circumstances in which the auditors are likely to decide to confirm accounts payable.
c. Describe the types of accounts payable the auditors are likely to select for confirmation.
(Essay)
4.8/5 (68)
(68) With properly designed internal control, the same employee should not be permitted to:
(Multiple Choice)
4.8/5 (68)
(68) Which of the following manipulations would understate accounts payable on the financial statements?
(Multiple Choice)
4.9/5 (80)
(80) Auditors should be aware that a voucher system may result in which of the following at year-end:
(Multiple Choice)
4.8/5 (80)
(80) Which of the following procedures is least likely to be completed before the balance sheet date?
(Multiple Choice)
4.7/5 (81)
(81) Auditors may choose not to confirm accounts payable because:
(Multiple Choice)
4.9/5 (87)
(87) Information regarding the proper cutoff of accounts payable is generally obtained in conjunction with the audit of inventories.
(True/False)
4.8/5 (75)
(75) A likely analytical procedure to test the accuracy of purchase discounts would be to compute the ratio of cash discounts earned to:
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)