



 Chat with AI
Exam 12: Inventories and Cost of Goods Sold

Exam 1: The Role of the Public Accountant in the American Economy45 Questions
Exam 2: Professional Standards62 Questions
Exam 3: Professional Ethics62 Questions
Exam 4: Legal Liability of Cpas56 Questions
Exam 5: Audit Evidence and Documentation82 Questions
Exam 6: Planning the Audit; Linking Audit Procedures to Risk78 Questions
Exam 7: Internal Control92 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment63 Questions
Exam 9: Audit Sampling83 Questions
Exam 10: Cash and Financial Investments61 Questions
Exam 11: Accounts Receivable, Notes Receivable, and Revenue64 Questions
Exam 12: Inventories and Cost of Goods Sold59 Questions
Exam 13: Property, Plant, and Equipment: Depreciation and Depletion39 Questions
Exam 14: Accounts Payable and Other Liabilities50 Questions
Exam 15: Debt and Equity Capital40 Questions
Exam 16: Auditing Operations and Completing the Audit69 Questions
Exam 17: Auditors Report62 Questions
Exam 18: Integrated Audits of Public Companies43 Questions
Exam 19: Additional Assurance Services: Historical Financial Information60 Questions
Exam 20: Additional Assurance Services: Other Information51 Questions
Exam 21: Internal, Operational, and Compliance Auditing48 Questions
Select questions type


Which of the following is not a procedure that typically is used by the auditors in their examination of a client's goods held in the custody of a public warehouse?

Free
(Multiple Choice)
4.8/5  (73)
(73) Correct Answer: Verified
D
Purchase cutoff procedures should be designed to test whether all inventory:
Free
(Multiple Choice)
4.9/5 (70)
(70) Correct Answer:Verified
VerifiedA
Which of the following best describes the reason that the auditors record their inventory test counts in the working papers?
Free
(Multiple Choice)
4.9/5 (85)
(85) Correct Answer:Verified
VerifiedB
Observation of a client's inventory is a presumptively mandatory audit procedure.
a. What part should the auditors play in planning the physical inventory?
b. Describe the procedures performed by the auditors during their observation of a client's physical inventory.
c. Why do the auditors document their inventory test counts in their working papers?
(Essay)
4.8/5 (87)
(87) Which of the following audit procedures most likely would provide assurance that a manufacturing entity's inventory valuation is proper?
(Multiple Choice)
4.9/5 (91)
(91) After accounting for a sequence of inventory tags, an auditor traces a sample of tags to the physical inventory listing to obtain evidence that all items:
(Multiple Choice)
4.8/5 (74)
(74) In auditing a client's inventory, the auditors must be concerned with the detection of goods that are both damaged and obsolete.
a. Why are the auditors concerned with detecting damaged and obsolete goods?
b. How do the auditors test for damaged goods in the client's inventory?
c. How do the auditors test for obsolete goods in the client's inventory?
(Essay)
4.9/5 (80)
(80) A client uses a periodic inventory system. Would one expect a credit to which of the following accounts at the point of sale? Sales Inventory A. Yes Yes B. Yes No C. No Yes D. No No
(Multiple Choice)
5.0/5 (88)
(88) To assure that all purchases are authorized before payment is made, accounting department personnel should match the vendor's invoice to:
(Multiple Choice)
4.9/5 (72)
(72) Assume that you have completed your procedures on the audit of Glick Corporation and have found the following audit issues. Indicate the account balance financial statement assertion that is likely to be most impacted by each of the issues, using the following key:
A.Completeness
B.Existence
C.Rights and Obligations
D.Valuation and Allocation 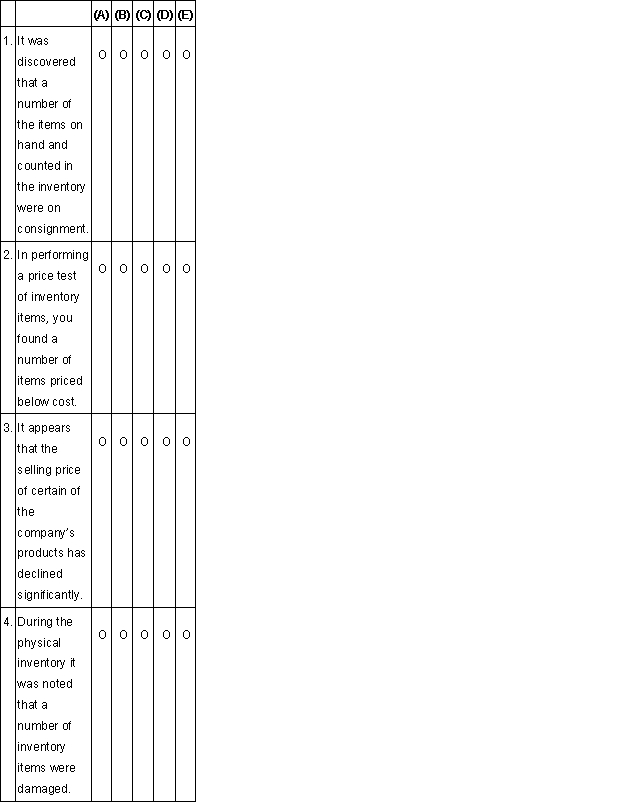
(Essay)
4.9/5 (81)
(81) The most reliable procedure for an auditor to use to test the existence of a client's inventory at an outside location would be to:
(Multiple Choice)
5.0/5 (98)
(98) The use of a "blind" purchase order is designed to prevent errors by the:
(Multiple Choice)
4.8/5 (90)
(90) The lower-of-cost-or-market test by the auditors is generally designed to assure that inventories are not valued above their net realizable values.
(True/False)
4.8/5 (80)
(80) The accuracy of perpetual inventory records may be established, in part, by comparing perpetual inventory records with:
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is an effective control that encourages receiving department personnel to count and inspect all merchandise received?
(Multiple Choice)
4.8/5 (73)
(73) The receiving department should accept only goods for which there is an approved purchase order on hand.
(True/False)
4.7/5 (87)
(87) The examination of warehouse receipts is not sufficient verification of a material amount of goods stored in public warehouses.
(True/False)
4.8/5 (82)
(82) Your audit client, Wigley, is a retail department store that does not produce any products. You are currently working on the inventory portion of the audit. In obtaining audit evidence in support of financial statement assertions, the auditor develops specific audit objectives in response to those assertions. Audit procedures are then selected to accomplish audit objectives.
For each specific inventory audit objective listed (Audit Objectives tab) select the most closely related account balance financial statement assertion and the most appropriate audit procedure. Financial statement assertions and audit procedures may be selected once, more than once, or not at all. 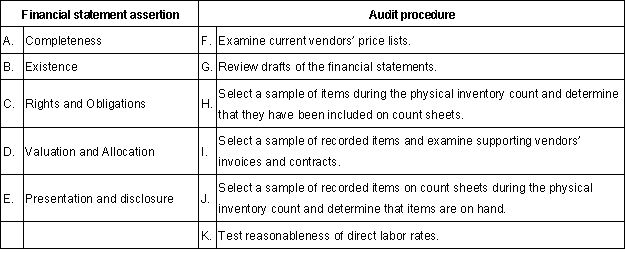 Specific audit objectives (A) (B) (C) (D) (E) (F) (G) (H) (I) (J) () 1. The entity has legal title to inventories. 0 0 0 0 0 0 0 0 0 0 0 2. Recorded inuentory quantities include all products on hand. 0 0 0 0 0 0 0 0 0 0 0 3. Inventories are reduced, when appropriate, to replacement costs or net realizable value. 0 0 0 0 0 0 0 0 0 0 0 4. Cost of imentories is properly calculated. 0 0 0 0 0 0 0 0 0 0 0 5. The major categories of inventories and their basis of valuation are adequately reported in the financial statements. 0 0 0 0 0 0 0 0 0 0 0
 (Essay)
5.0/5 (80)
(80) A client uses a perpetual inventory system. Would one expect a credit to which of the following accounts at the point of sale? Sales Inventory A. Yes Yes B. Yes No C. No Yes D. No No
(Multiple Choice)
4.9/5 (60)
(60) Which of the following is not one of the independent auditor's objectives regarding the examination of inventories?
(Multiple Choice)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)