



 Chat with AI
Exam 4: Legal Liability of Cpas

Exam 1: The Role of the Public Accountant in the American Economy45 Questions
Exam 2: Professional Standards62 Questions
Exam 3: Professional Ethics62 Questions
Exam 4: Legal Liability of Cpas56 Questions
Exam 5: Audit Evidence and Documentation82 Questions
Exam 6: Planning the Audit; Linking Audit Procedures to Risk78 Questions
Exam 7: Internal Control92 Questions
Exam 8: Consideration of Internal Control in an Information Technology Environment63 Questions
Exam 9: Audit Sampling83 Questions
Exam 10: Cash and Financial Investments61 Questions
Exam 11: Accounts Receivable, Notes Receivable, and Revenue64 Questions
Exam 12: Inventories and Cost of Goods Sold59 Questions
Exam 13: Property, Plant, and Equipment: Depreciation and Depletion39 Questions
Exam 14: Accounts Payable and Other Liabilities50 Questions
Exam 15: Debt and Equity Capital40 Questions
Exam 16: Auditing Operations and Completing the Audit69 Questions
Exam 17: Auditors Report62 Questions
Exam 18: Integrated Audits of Public Companies43 Questions
Exam 19: Additional Assurance Services: Historical Financial Information60 Questions
Exam 20: Additional Assurance Services: Other Information51 Questions
Exam 21: Internal, Operational, and Compliance Auditing48 Questions
Select questions type


Which of the following is a correct statement related to CPA legal liability under common law?

Free
(Multiple Choice)
4.9/5  (69)
(69) Correct Answer: Verified
B
Which of the following must be proven by the plaintiff in a case against a CPA under the Section 11 liability provisions of the Securities Act of 1933?
Free
(Multiple Choice)
4.8/5 (87)
(87) Correct Answer:Verified
VerifiedC
In a common law action against an accountant, lack of privity is a viable defense if the plaintiff:
Free
(Multiple Choice)
4.8/5 (75)
(75) Correct Answer:Verified
VerifiedA
Under which common law approach are auditors most likely to be held liable for ordinary negligence to a "reasonably foreseeable" third party?
(Multiple Choice)
4.9/5 (80)
(80) Most of the burden of affirmative proof is on the defendant under common law.
(True/False)
4.7/5 (77)
(77) Dexter and Co., CPAs, issued an unqualified opinion on the 20X3 financial statements of Bart Corp. Late in 20X4, Bart determined that its treasurer had embezzled over $1,000,000. Dexter was unaware of the embezzlement. Bart has decided to sue Dexter to recover the $1,000,000. Bart's suit is based upon Dexter's failure to discover the missing money while performing the audit. Which of the following is Dexter's best defense?
(Multiple Choice)
4.8/5 (81)
(81) Starr Corp. approved a plan of merger with Silo Corp. One of the determining factors in approving the merger was the strong financial statements of Silo which were audited by Cox & Co., CPAs. Starr had engaged Cox to audit Silo's financial statements. While performing the audit, Cox failed to discover certain instances of fraud which have subsequently caused Starr to suffer substantial losses. In order for Cox to be liable under common law, Starr, at a minimum, must prove that Cox:
(Multiple Choice)
4.8/5 (72)
(72) Which of the following is not correct relating to the Private Securities Litigation Reform Act of 1995?
(Multiple Choice)
4.9/5 (81)
(81) Auditors may be held liable to both their clients and third parties under common law.
a. What must a client prove to recover its losses from the auditors under common law?
b. In a court that adheres to the precedent set by the Ultramares v. Touche case, what must an ordinary third party prove to recover losses from the auditors under common law?
(Essay)
4.8/5 (78)
(78) Under the Securities Act of 1933, the burden of proof that the plaintiff sustained a loss must be proven by the:
(Multiple Choice)
4.8/5 (67)
(67) Under Section 10 of the 1934 Securities Exchange Act auditors are liable to security purchasers for:
(Multiple Choice)
4.9/5 (64)
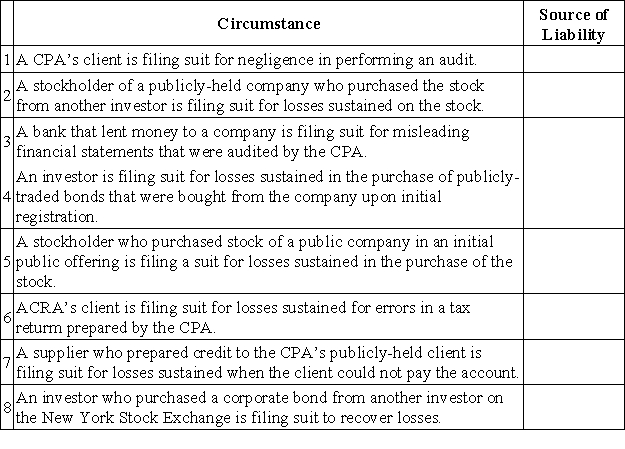
(64) A plaintiff may elect to bring a lawsuit against auditors under applicable statutes-including the Securities Act of 1933 and the Securities Exchange Act of 1934-and under common law. For each circumstance, indicate the most likely source of CPA liability by placing the appropriate letter in the third column.
A. The Securities Act of 1933
B. The Securities Exchange Act of 1934
C. Common Law
(Essay)
4.8/5 (81)
(81) An auditor knew that the purpose of her audit was to render reasonable assurance on financial statements that were to be used for the application for a loan; the auditor did not know the identity of the bank that would eventually give the loan. Under the foreseeable third party approach, the auditor is generally liable to the bank which subsequently grants the loan for:
(Multiple Choice)
4.9/5 (70)
(70) Which of the following forms of organization is most likely to protect the personal assets of any partner, or shareholder who has not been involved on an engagement resulting in litigation?
(Multiple Choice)
4.9/5 (80)
(80) Section 11 of the Securities Act of 1933, and Section 10 of the Securities Exchange Act of 1934 make a CPA potentially liable to a purchaser of registered securities. For items a through f, place a checkmark (√) under the column if the plaintiff must prove its existence: 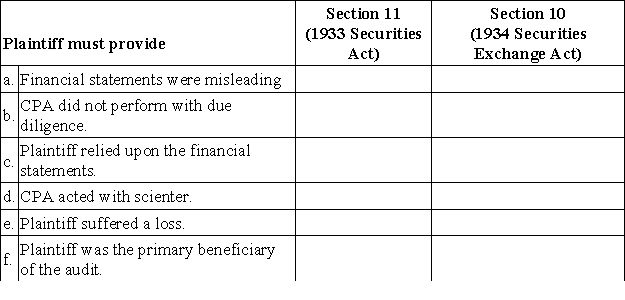
(Essay)
4.8/5 (70)
(70) Which of the following court cases highlighted the need for obtaining engagement letters for professional services?
(Multiple Choice)
4.9/5 (85)
(85) Which of the following is accurate with respect to litigation involving CPAs?
(Multiple Choice)
4.8/5 (80)
(80) The precedent set by the Hochfelder v. Ernst case is generally believed to have increased auditors' legal liability.
(True/False)
4.9/5 (67)
(67) CPAs should not be liable to any party if they perform their services with:
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)