



 Chat with AI
Exam 6: Risk and return

Exam 1: An overview of financial management and the financial environment46 Questions
Exam 2: Financial statements, cash flow, and taxes77 Questions
Exam 3: Analysis of financial statements104 Questions
Exam 4: Time value of money168 Questions
Exam 5: Bonds, bond valuation, and interest rates100 Questions
Exam 6: Risk and return146 Questions
Exam 7: Valuation of stocks and corporations80 Questions
Exam 8: Financial options and applications in corporate finance28 Questions
Exam 9: The cost of capital92 Questions
Exam 10: The basics of capital budgeting: evaluating cash flows108 Questions
Exam 11: Cash flow estimation and risk analysis78 Questions
Exam 12: Corporate valuation and financial planning41 Questions
Exam 13: Agency conflicts and corporate governance6 Questions
Exam 14: Distributions to shareholders: dividends and repurchases58 Questions
Exam 15: Capital structure decisions72 Questions
Exam 16: Supply chains and working capital management138 Questions
Exam 17: Multinational financial management49 Questions
Select questions type


The two stocks in your portfolio, X and Y, have independent returns, so the correlation between them, rXY is zero.Your portfolio consists of $50, 000 invested in Stock X and $50, 000 invested in Stock Y.Both stocks have an expected return of 15%, betas of 1.6, and standard deviations of 30%.Which of the following statements best describes the characteristics of your 2-stock portfolio?
(Multiple Choice)
4.7/5  (77)
(77) Stock A's beta is 1.7 and Stock B's beta is 0.7.Which of the following statements must be true about these securities? (Assume market equilibrium.)
(Multiple Choice)
4.9/5 (73)
(73) In historical data, we see that investments with the highest average annual returns also tend to have the highest standard deviations of annual returns.This observation supports the notion that there is a positive correlation between risk and return.Which of the following answers correctly ranks investments from highest to lowest risk (and return), where the security with the highest risk is shown first, the one with the lowest risk last?
(Multiple Choice)
4.8/5 (76)
(76) Ann has a portfolio of 20 average stocks, and Tom has a portfolio of 2 average stocks.Assuming the market is in equilibrium, which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (84)
(84) Stock A has a beta of 0.8 and Stock B has a beta of 1.2.50% of Portfolio P is invested in Stock A and 50% is invested in Stock B.If the market risk premium (rM - rRF)were to increase but the risk-free rate (rRF)remained constant, which of the following would occur?
(Multiple Choice)
4.9/5 (71)
(71) Stock A has a beta = 0.8, while Stock B has a beta = 1.6.Which of the following statements is CORRECT?
(Multiple Choice)
4.7/5 (68)
(68) Which of the following statements is CORRECT? (Assume that the risk-free rate is a constant.)
(Multiple Choice)
4.8/5 (80)
(80) It is possible for a firm to have a positive beta, even if the correlation between its returns and those of another firm is negative.
(True/False)
4.8/5 (84)
(84) Ivan Knobel holds a well-diversified portfolio that has an expected return of 11.0% and a beta of 1.20.He is in the process of buying 1, 000 shares of Syngine Corp at $10 a share and adding it to his portfolio.Syngine has an expected return of 13.0% and a beta of 1.50.The total value of Ivan's current portfolio is $90, 000.What will the expected return and beta on the portfolio be after the purchase of the Syngine stock?
(Multiple Choice)
4.8/5 (87)
(87) Stocks A, B, and C are similar in some respects: Each has an expected return of 10% and a standard deviation of 25%.Stocks A and B have returns that are independent of one another; i.e., their correlation coefficient, r, equals zero.Stocks A and C have returns that are negatively correlated with one another; i.e., r is less than 0.Portfolio AB is a portfolio with half of its money invested in Stock A and half in Stock B.Portfolio AC is a portfolio with half of its money invested in Stock A and half invested in Stock C.Which of the following statements is CORRECT?
(Multiple Choice)
4.9/5 (62)
(62) Charlie and Lucinda each have $50, 000 invested in stock portfolios.Charlie's has a beta of 1.2, an expected return of 10.8%, and a standard deviation of 25%.Lucinda's has a beta of 0.8, an expected return of 9.2%, and a standard deviation that is also 25%.The correlation coefficient, r, between Charlie's and Lucinda's portfolios is zero.If Charlie and Lucinda marry and combine their portfolios, which of the following best describes their combined $100, 000 portfolio?
(Multiple Choice)
4.9/5 (83)
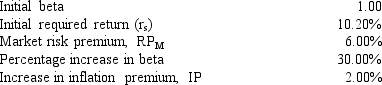
(83) Data for Atwill Corporation is shown below.Now Atwill acquires some risky assets that cause its beta to increase by 30%.In addition, expected inflation increases by 2.00%.What is the stock's new required rate of return?
(Multiple Choice)
4.7/5 (85)
(85) Consider the following information for three stocks, A, B, and C.The stocks' returns are positively but not perfectly positively correlated with one another, i.e., the correlations are all between 0 and 1.
 Portfolio AB has half of its funds invested in Stock A and half in Stock B.Portfolio ABC has one third of its funds invested in each of the three stocks.The risk-free rate is 5%, and the market is in equilibrium, so required returns equal expected returns.Which of the following statements is CORRECT?
 (Multiple Choice)
4.9/5 (64)
(64) The Y-axis intercept of the SML indicates the required return on an individual asset whenever the realized return on an average (b = 1)stock is zero.
(True/False)
4.8/5 (64)
(64) The distributions of rates of return for Companies AA and BB are given below:
 We can conclude from the above information that any rational, risk-averse investor would be better off adding Security AA to a well-diversified portfolio over Security BB.
 (True/False)
4.9/5 (82)
(82) Shirley Paul's 2-stock portfolio has a total value of $100, 000.$37, 500 is invested in Stock A with a beta of 0.75 and the remainder is invested in Stock B with a beta of 1.42.What is her portfolio's beta?
(Multiple Choice)
4.9/5 (93)
(93) We would almost always find that the beta of a diversified portfolio is less stable over time than the beta of a single security.
(True/False)
4.7/5 (78)
(78) Stock A's beta is 1.7 and Stock B's beta is 0.7.Which of the following statements must be true, assuming the CAPM is correct.
(Multiple Choice)
4.8/5 (82)
(82) Stocks A and B are quite similar: Each has an expected return of 12%, a beta of 1.2, and a standard deviation of 25%.The returns on the two stocks have a correlation of 0.6.Portfolio P has 50% in Stock A and 50% in Stock B.Which of the following statements is CORRECT?
(Multiple Choice)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)