Multiple Choice
Consider the following information for three stocks, A, B, and C.The stocks' returns are positively but not perfectly positively correlated with one another, i.e., the correlations are all between 0 and 1.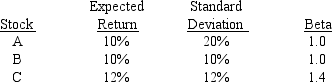
Portfolio AB has half of its funds invested in Stock A and half in Stock B.Portfolio ABC has one third of its funds invested in each of the three stocks.The risk-free rate is 5%, and the market is in equilibrium, so required returns equal expected returns.Which of the following statements is CORRECT?
A) Portfolio AB's coefficient of variation is greater than 2.0.
B) Portfolio AB's required return is greater than the required return on Stock A.
C) Portfolio ABC's expected return is 10.66667%.
D) Portfolio ABC has a standard deviation of 20%.
E) Portfolio AB has a standard deviation of 20%.
Correct Answer:

Verified
Correct Answer:
Verified
Q129: It is possible for a firm to
Q130: Ivan Knobel holds a well-diversified portfolio that
Q131: Stocks A, B, and C are similar
Q132: Charlie and Lucinda each have $50, 000
Q133: Data for Atwill Corporation is shown below.Now
Q135: The Y-axis intercept of the SML indicates
Q136: The distributions of rates of return for
Q137: Shirley Paul's 2-stock portfolio has a total
Q138: We would almost always find that the
Q139: Stock A's beta is 1.7 and Stock