



 Chat with AI
Exam 6: Risk and return

Exam 1: An overview of financial management and the financial environment46 Questions
Exam 2: Financial statements, cash flow, and taxes77 Questions
Exam 3: Analysis of financial statements104 Questions
Exam 4: Time value of money168 Questions
Exam 5: Bonds, bond valuation, and interest rates100 Questions
Exam 6: Risk and return146 Questions
Exam 7: Valuation of stocks and corporations80 Questions
Exam 8: Financial options and applications in corporate finance28 Questions
Exam 9: The cost of capital92 Questions
Exam 10: The basics of capital budgeting: evaluating cash flows108 Questions
Exam 11: Cash flow estimation and risk analysis78 Questions
Exam 12: Corporate valuation and financial planning41 Questions
Exam 13: Agency conflicts and corporate governance6 Questions
Exam 14: Distributions to shareholders: dividends and repurchases58 Questions
Exam 15: Capital structure decisions72 Questions
Exam 16: Supply chains and working capital management138 Questions
Exam 17: Multinational financial management49 Questions
Select questions type


Your friend is considering adding one additional stock to a 3-stock portfolio, to form a 4-stock portfolio.She is highly risk averse and has asked for your advice.The three stocks currently held all have b = 1.0, and they are perfectly positively correlated with the market.Potential new Stocks A and B both have expected returns of 15%, are in equilibrium, and are equally correlated with the market, with r = 0.75.However, Stock A's standard deviation of returns is 12% versus 8% for Stock B.Which stock should this investor add to his or her portfolio, or does the choice not matter?
(Multiple Choice)
5.0/5  (78)
(78) For a stock to be in equilibrium, two conditions are necessary: (1)The stock's market price must equal its intrinsic value as seen by the marginal investor and (2)the expected return as seen by the marginal investor must equal this investor's required return.
(True/False)
4.8/5 (89)
(89) Variance is a measure of the variability of returns, and since it involves squaring the deviation of each actual return from the expected return, it is always larger than its square root, its standard deviation.
(True/False)
4.8/5 (81)
(81) For markets to be in equilibrium, that is, for there to be no strong pressure for prices to depart from their current levels,
(Multiple Choice)
5.0/5 (68)
(68) Even if the correlation between the returns on two securities is +1.0, if the securities are combined in the correct proportions, the resulting 2-asset portfolio will have less risk than either security held alone.
(True/False)
4.8/5 (65)
(65) If you plotted the returns on a given stock against those of the market, and if you found that the slope of the regression line was negative, the CAPM would indicate that the required rate of return on the stock should be greater than the risk-free rate for a well-diversified investor, assuming that the observed relationship is expected to continue into the future.
(True/False)
4.9/5 (97)
(97) A stock's beta measures its diversifiable risk relative to the diversifiable risks of other firms.
(True/False)
4.8/5 (69)
(69) The $10.00 million mutual fund Henry manages has a beta of 1.05 and a 9.50% required return.The risk-free rate is 4.20%.Henry now receives another $5.00 million, which he invests in stocks with an average beta of 0.65.What is the required rate of return on the new portfolio? (Hint: You must first find the market risk premium, then find the new portfolio beta.)
(Multiple Choice)
4.8/5 (69)
(69) Portfolio AB was created by investing in a combination of Stocks A and B.Stock A has a beta of 1.2 and a standard deviation of 25%.Stock B has a beta of 1.4 and a standard deviation of 20%.Portfolio AB has a beta of 1.25 and a standard deviation of 18%.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (77)
(77) Zacher Co.'s stock has a beta of 1.40, the risk-free rate is 4.25%, and the market risk premium is 5.50%.What is the firm's required rate of return?
(Multiple Choice)
4.8/5 (79)
(79) Stock A has a beta of 0.8, Stock B has a beta of 1.0, and Stock C has a beta of 1.2.Portfolio P has 1/3 of its value invested in each stock.Each stock has a standard deviation of 25%, and their returns are independent of one another, i.e., the correlation coefficients between each pair of stocks is zero.Assuming the market is in equilibrium, which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (93)
(93) Portfolio P has $200, 000 consisting of $100, 000 invested in Stock A and $100, 000 in Stock B.Stock A has a beta of 1.2 and a standard deviation of 20%.Stock B has a beta of 0.8 and a standard deviation of 25%.Which of the following statements is CORRECT? (Assume that the stocks are in equilibrium.)
(Multiple Choice)
5.0/5 (77)
(77) Joel Foster is the portfolio manager of the SF Fund, a $3 million hedge fund that contains the following stocks.The required rate of return on the market is 11.00% and the risk-free rate is 5.00%.What rate of return should investors expect (and require)on this fund?
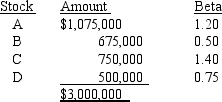
(Multiple Choice)
5.0/5 (77)
(77) We would generally find that the beta of a single security is more stable over time than the beta of a diversified portfolio.
(True/False)
4.7/5 (85)
(85) A stock with a beta equal to -1.0 has zero systematic (or market)risk.
(True/False)
4.8/5 (77)
(77) For a stock to be in equilibrium, that is, for there to be no long-term pressure for its price to depart from its current level, then
(Multiple Choice)
4.8/5 (81)
(81) Assume that the risk-free rate, rRF, increases but the market risk premium, (rM - rRF), declines, with the net effect being that the overall required return on the market, rM, remains constant.Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (82)
(82) If a stock's market price exceeds its intrinsic value as seen by the marginal investor, then the investor will sell the stock until its price has fallen down to the level of the investor's estimate of the intrinsic value.
(True/False)
4.9/5 (87)
(87) Diversification will normally reduce the riskiness of a portfolio of stocks.
(True/False)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)