



 Chat with AI
Exam 18: Corporations: Organization and Capital Structure

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


George (an 80% shareholder) has made loans to Mountainview Corporation that become worthless in the current year. George is not employed by Mountainview.
(Multiple Choice)
4.8/5  (84)
(84) Mary transfers a building (adjusted basis of $15,000 and fair market value of $90,000) to White Corporation. In return, Mary receives 80% of White Corporation's stock (worth $65,000) and an automobile (fair market value of $5,000). In addition, there is an outstanding mortgage of $20,000 (taken out 15 years ago) on the building, which White Corporation assumes. With respect to this transaction:
(Multiple Choice)
4.8/5 (85)
(85) When forming a corporation, a transferor-shareholder may choose to receive some corporate debt along with stock.
Identify some of the issues the transferor must consider when deciding whether debt should be a part of the transaction.
(Essay)
4.7/5 (73)
(73) Sofia forms Lark Corporation with a transfer of appreciated property in exchange for all of its shares. Shortly thereafter, she transfers half her shares to her son, Ted. The later transfer to Ted could cause the original transfer to be taxable.
(True/False)
4.8/5 (82)
(82) If a transaction qualifies under § 351, any recognized gain is equal to the value of the boot received.
(True/False)
4.8/5 (79)
(79) The receipt of nonqualified preferred stock in exchange for the transfer of appreciated property to a controlled corporation results in recognition of gain to the transferor.
(True/False)
4.8/5 (78)
(78) Alan, an Owl Corporation shareholder, makes a contribution to capital of equipment to Owl, basis of $40,000 and fair market value of $50,000. Owl's basis of the equipment that Alan contributes is equal to $50,000, the property's fair market value.
(True/False)
4.8/5 (74)
(74) Stock in Merlin Corporation is held equally by Jane, Eve, and Fred. Merlin seeks additional capital to buy a valuable tract of land that will cost $6,000,000. Jane, Eve, and Fred propose to loan Merlin $2,000,000 each, taking from Merlin a $2,000,000 ten-year note with interest payable annually at five points above the prime rate. Merlin Corporation has current taxable income of $7,000,000. How are the payments on the notes treated for tax purposes?
(Essay)
4.8/5 (79)
(79) What are the tax consequences if an individual investor incurs a loss on the following:
a. Stock that is not § 1244 stock.
b. Stock that is § 1244 stock.
c. Corporate bond.
d. An uncollectible loan made to a corporation.
(Essay)
4.8/5 (76)
(76) Jane transfers property (basis of $180,000 and fair market value of $500,000) to Green Corporation for 80% of its stock (worth $425,000) and a long-term note (worth $75,000), executed by Green Corporation and made payable to Jane. As a result of the transfer:
(Multiple Choice)
4.8/5 (73)
(73) When a taxpayer transfers property subject to a mortgage to a controlled corporation in an exchange qualifying under § 351, the transferor shareholder's basis in stock received in the transferee corporation is increased by the amount of the mortgage on the property.
(True/False)
4.9/5 (78)
(78) When depreciable property is transferred to a controlled corporation under § 351, any recapture potential disappears and does not carry over to the corporation.
(True/False)
4.8/5 (74)
(74) Eve transfers property (basis of $120,000 and fair market value of $400,000) to Green Corporation for 80% of its stock (worth $350,000) and a long-term note (worth $50,000), executed by Green Corporation and made payable to Eve. As a result of the transfer:
(Multiple Choice)
4.9/5 (73)
(73) Penny, Miesha, and Sabrina transfer property to Owl Corporation for 75% of its stock. Nancy, their attorney, receives 25% of the stock in Owl for legal services rendered in incorporating the business. What are the tax consequences of these transactions? How should this transaction have been handled?
(Essay)
4.8/5 (69)
(69) Nancy, Guy, and Rod form Goldfinch Corporation with the following consideration.
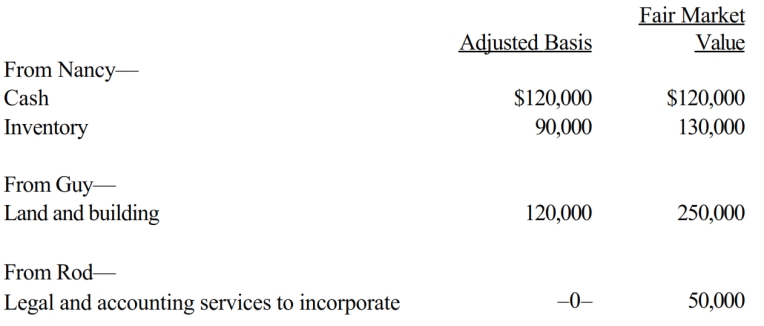 Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets $50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock?
Goldfinch issues its 500 shares of stock as follows: 250 to Nancy, 200 to Guy, and 50 to Rod. In addition, Guy gets $50,000 in cash.
a. Does Nancy, Guy, or Rod recognize gain (or income)?
b. What basis does Guy have in the Goldfinch stock?
c. What basis does Goldfinch Corporation have in the inventory? In the land and building?
d. What basis does Rod have in the Goldfinch stock? (Essay)
4.7/5 (76)
(76) Mitchell and Powell form Green Corporation. Mitchell transfers property (basis of $105,000 and fair market value of $90,000) while Powell transfers land (basis of $8,000 and fair market value of $75,000) and $15,000 of cash. Each receives 50% of Green Corporation's stock (total value of $180,000). As a result of these transfers:
(Multiple Choice)
4.9/5 (77)
(77) Dawn, a sole proprietor, was engaged in a service business and reported her income on a cash basis. Later, she incorporates her business and transfers the assets of the business to the corporation in return for all the stock in the corporation plus the corporation's assumption of the liabilities of her proprietorship. All the receivables and the unpaid trade payables are transferred to the newly formed corporation. The assets of the proprietorship had a basis of $105,000 and fair market value of $300,000. The trade accounts payable totaled $25,000. There was a note payable to the bank in the amount of $95,000 that the corporation assumes. The note was issued for the purchase of computers and other business equipment.
(Multiple Choice)
4.9/5 (85)
(85) Jane and Walt form Yellow Corporation. Jane transfers equipment worth $950,000 (basis of $200,000) and cash of $50,000 to Yellow Corporation for 50% of its stock. Walt transfers a building and land worth $1,050,000 (basis of $400,000) for 50% of Yellow's stock and $50,000 in cash.
(Multiple Choice)
4.7/5 (81)
(81) Because services are not considered property under § 351, a taxpayer must report as income the fair market value of stock received for such services.
(True/False)
4.7/5 (79)
(79) A shareholder lends money to his corporation in his capacity as an investor. If the loans become worthless, a business bad debt results.
(True/False)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)