



 Chat with AI
Exam 9: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models160 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System191 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply241 Questions
Exam 4: Market Efficiency and Market Failure226 Questions
Exam 5: The Economics of Healthcare169 Questions
Exam 6: Firms,the Stock Market,and Corporate Governance255 Questions
Exam 7: Consumer Choice and Elasticity270 Questions
Exam 8: Technology, production, and Costs277 Questions
Exam 9: Firms in Perfectly Competitive Markets351 Questions
Exam 10: Monopoly and Antitrust253 Questions
Exam 11: Monopolistic Competition and Oligopoly304 Questions
Exam 12: GDP: Measuring Total Production and Income200 Questions
Exam 13: Unemployment and Inflation207 Questions
Exam 14: Economic Growth, the Financial System and Business Cycles172 Questions
Exam 15: Aggregate Demand and Aggregate Supply Analysis120 Questions
Exam 16: Money, banks, and the Federal Reserve System139 Questions
Exam 17: Monetary Policy180 Questions
Exam 18: Fiscal Policy131 Questions
Exam 19: Comparative Advantage, international Trade, and Exchange Rates247 Questions
Select questions type


Explain the similarities and differences between the long-run equilibrium for a perfectly competitive firm and a monopolistically competitive firm.Illustrate your answer with a graph demonstrating the long-run equilibrium for the two types of firms.
(Essay)
4.9/5  (88)
(88) Figure 9-8  Figure 9-8 shows cost and demand curves for a monopolistically competitive producer of iced tea.
-Refer to Figure 9-8.What is the profit-maximising output level?
Figure 9-8 shows cost and demand curves for a monopolistically competitive producer of iced tea.
-Refer to Figure 9-8.What is the profit-maximising output level? (Multiple Choice)
5.0/5 (88)
(88) Table 9-5
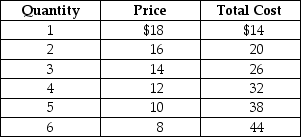 Table 9-5 shows the demand and cost data facing a monopolistically competitive producer of canvas bags.
-Refer to Table 9-5.What are the firm's profit-maximising or loss-minimising price and quantity?
Table 9-5 shows the demand and cost data facing a monopolistically competitive producer of canvas bags.
-Refer to Table 9-5.What are the firm's profit-maximising or loss-minimising price and quantity? (Multiple Choice)
4.9/5 (79)
(79) Figure 9-12  -Refer to Figure 9-12.What is the monopolistic competitor's profit-maximising price?
 (Multiple Choice)
4.7/5 (77)
(77) Suppose that if a local McDonald's restaurant reduces the price of a Big Mac from $4.00 to $3.25,the number of Big Macs it sells per day will increase from 4 to 5.Explain the output effect and the price effect resulting from this change.Using a graph,illustrate both the loss in revenue from selling each of the first 4 Big Macs for $0.75 less and the additional revenue from selling 1 more Big Mac.What is the total change in revenue received which results from this price decrease?
(Essay)
4.8/5 (69)
(69) If firms in a monopolistically competitive market are earning economic profits,which of the following scenarios best reflects the change a representative firm experiences as the market adjusts to its long-run equilibrium?
(Multiple Choice)
4.9/5 (76)
(76) Which of the following is an example of implicit collusion?
(Multiple Choice)
4.8/5 (86)
(86) Consumers in a monopolistically competitive market do not receive any consumer surplus because the price paid for the product exceeds the marginal cost of production.
(True/False)
4.9/5 (77)
(77) Which of the following is not a characteristic of long-run equilibrium in a monopolistically competitive market?
(Multiple Choice)
4.7/5 (71)
(71) You are planning to open a new Italian restaurant in your hometown where there are three other Italian restaurants.You plan to distinguish your restaurant from your competitors by offering northern Italian cuisine and using locally grown organic produce.What is likely to happen in the restaurant market in your hometown after you open?
(Multiple Choice)
4.9/5 (80)
(80) Natural resource cartels such as OPEC are inherently unstable because their members operate with excess capacity and have an incentive to cheat on their output quotas.
(True/False)
4.7/5 (85)
(85) Why are demand and marginal revenue represented by the same curve for a firm in a perfectly competitive market,but by separate curves for a firm in a monopolistically competitive market?
(Essay)
4.7/5 (82)
(82) Which of the following describes a difference between the marginal revenue and demand curves of a perfectly competitive firm and a monopolistically competitive firm?
(Multiple Choice)
4.7/5 (83)
(83) In the long run,what happens to the demand curve facing a monopolistically competitive firm that is earning short-run profits?
(Multiple Choice)
4.8/5 (79)
(79) Airlines often engage in last-minute price cutting to fill remaining empty seats on a flight because this practice will generally
(Multiple Choice)
4.8/5 (82)
(82) Why do most firms in monopolistic competition typically make zero profit in the long run?
(Multiple Choice)
4.7/5 (74)
(74) Table 9-6  Godrickporter and Star Connections are the only two airport shuttle and limousine rental service companies in the mid-sized town of Godrick Hollow. Each firm must decide whether to increase its advertising spending to compete for customers. Table 9-6 shows the payoff matrix for this advertising game.
-Refer to Table 9-6.Is there a dominant strategy for Godrickporter and,if so,what is it?
Godrickporter and Star Connections are the only two airport shuttle and limousine rental service companies in the mid-sized town of Godrick Hollow. Each firm must decide whether to increase its advertising spending to compete for customers. Table 9-6 shows the payoff matrix for this advertising game.
-Refer to Table 9-6.Is there a dominant strategy for Godrickporter and,if so,what is it? (Multiple Choice)
5.0/5 (76)
(76) Table 9-8  Firm A (Alistair's) and Firm B (Baine's) are the only firms selling luggage in the upscale city of Adelaide. Each firm must decide on whether to increase its advertising spending to compete for customers. If one firm increases its advertising budget but the other does not, then the firm with the higher advertising budget will increase its profit. Table 9-8 shows the payoff matrix for this advertising game.
-Refer to Table 9-8.How are the firms in this advertising game caught in a prisoner's dilemma?
Firm A (Alistair's) and Firm B (Baine's) are the only firms selling luggage in the upscale city of Adelaide. Each firm must decide on whether to increase its advertising spending to compete for customers. If one firm increases its advertising budget but the other does not, then the firm with the higher advertising budget will increase its profit. Table 9-8 shows the payoff matrix for this advertising game.
-Refer to Table 9-8.How are the firms in this advertising game caught in a prisoner's dilemma? (Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)