



 Chat with AI
Exam 8: Flexible Budgets, overhead Cost Variances, and Management Control

Exam 1: The Manager and Management Accounting195 Questions
Exam 2: An Introduction to Cost Terms and Purposes224 Questions
Exam 3: Cost-Volume-Profit Analysis208 Questions
Exam 4: Job Costing199 Questions
Exam 5: Activity-Based Costing and Activity-Based Management176 Questions
Exam 6: Master Budget and Responsibility Accounting226 Questions
Exam 7: Flexible Budgets, direct-Cost Variances, and Management Control180 Questions
Exam 8: Flexible Budgets, overhead Cost Variances, and Management Control176 Questions
Exam 9: Inventory Costing and Capacity Analysis211 Questions
Exam 10: Determining How Costs Behave190 Questions
Exam 11: Decision Making and Relevant Information218 Questions
Exam 12: Strategy, balanced Scorecard, and Strategic Profitability Analysis172 Questions
Exam 13: Pricing Decisions and Cost Management210 Questions
Exam 14: Cost Allocation, customer-Profitability Analysis, and Sales-Variance Analysis167 Questions
Exam 15: Allocation of Support-Department Costs, common Costs, and Revenues150 Questions
Exam 16: Cost Allocation: Joint Products and Byproducts151 Questions
Exam 17: Process Costing149 Questions
Exam 18: Spoilage, rework, and Scrap153 Questions
Exam 19: Balanced Scorecard: Quality and Time151 Questions
Exam 20: Inventory Management, just-In-Time, and Simplified Costing Methods151 Questions
Exam 21: Capital Budgeting and Cost Analysis151 Questions
Exam 22: Management Control Systems, transfer Pricing, and Multinational Considerations153 Questions
Exam 23: Performance Measurement, compensation, and Multinational Considerations151 Questions
Select questions type


An unfavorable variable overhead efficiency variance indicates that ________.
(Multiple Choice)
4.8/5  (67)
(67) The variable overhead efficiency variance is computed ________ and interpreted ________ the direct-cost efficiency variance.
(Multiple Choice)
4.9/5 (81)
(81) Use the following information to answer the following questions:
Autogas Corporation manufactures industrial-sized gas furnaces and uses budgeted machine hours to allocate variable manufacturing overhead. The following information relates to the company's manufacturing overhead data:
Budgeted output units 31,000 urits Budgeted machine-hours 16,585 hours Budgeted variable manufacturing overhead costs for 31,000 units \ 348,285 Actual output units produced 33,000 urits Actual machine-hours used 14,400 hours Actual variable manufacturing overhead costs \ 384,000
-What is the flexible-budget variance for variable manufacturing overhead?
(Multiple Choice)
4.9/5 (73)
(73) Marshall Company uses a standard cost system.In April,$266,000 of variable manufacturing overhead costs were incurred and the flexible-budget amount for the month was $300,000.Which of the following variable manufacturing overhead entries would have been recorded for March?
(Multiple Choice)
4.8/5 (84)
(84) The variable overhead spending variance measures the difference between ________,multiplied by the actual quantity of variable overhead cost-allocation base used.
(Multiple Choice)
4.9/5 (93)
(93) Prorated allocation of production-volume variance results in a higher operating income for current year than if the entire favorable production-volume variance were credited to Cost of Goods Sold.
(True/False)
4.9/5 (79)
(79) Explain two concerns when interpreting the production-volume variance as a measure of the economic cost of unused capacity.
(Essay)
5.0/5 (71)
(71) Answer the following questions using the information below:
Roberson Corporation manufactured 30,000 ice chests during September. The variable overhead cost-allocation base is $11.25 per machine-hour. The following variable overhead data pertain to September:
Actual Budgeted Production 30,000 units 24,000 units Machine-hours 15,000 hours 10,800 hours Variable overhead cost per machine-hour: \ 11.00 \ 11.25
-What is the actual variable overhead cost?
(Multiple Choice)
4.8/5 (76)
(76) Answer the following questions using the information below:
Lukehart Industries, Inc., produces air purifiers. Lukehart, Inc., produces the air purifiers in batches. To manufacture a batch of the purifiers, Lukehart, Inc., must set up the machines and assembly line tooling. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and tooling for different models of the air purifiers.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with respect to the number of setup-hours. The following information pertains to June 2015:
Budget Actual Amounts Amounts Units produced and sold 10,000 9,000 Batch size (number of units per batch) 400 375 Setup-hours per batch 6 5.5 Variable overhead cost per setup-hour \ 50 \ 52 Total fixed setup overhead costs \ 18,000 \ 17,750
-Calculate the spending variance for fixed overhead setup costs.
(Multiple Choice)
4.8/5 (82)
(82) Answer the following questions using the information below:
Lukehart Industries, Inc., produces air purifiers. Lukehart, Inc., produces the air purifiers in batches. To manufacture a batch of the purifiers, Lukehart, Inc., must set up the machines and assembly line tooling. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and tooling for different models of the air purifiers.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with respect to the number of setup-hours. The following information pertains to June 2015:
Budget Actual Amounts Amounts Units produced and sold 10,000 9,000 Batch size (number of units per batch) 400 375 Setup-hours per batch 6 5.5 Variable overhead cost per setup-hour \ 50 \ 52 Total fixed setup overhead costs \ 18,000 \ 17,750
-Calculate the spending variance for variable overhead setup costs.
(Multiple Choice)
4.7/5 (90)
(90) When forecasting fixed costs,managers should concentrate on total lump-sum costs instead of unitized fixed overhead costs.
(True/False)
4.9/5 (79)
(79) Standard costing is a cost system that allocates overhead costs on the basis of overhead cost rates based on actual overhead costs times the standard quantities of the allocation bases allowed for the actual outputs produced.
(True/False)
4.8/5 (79)
(79) Computing standard costs at the start of the budget period results in a complex record keeping system.
(True/False)
4.7/5 (87)
(87) Which of the following journal entries is used to record actual variable overhead costs incurred?
(Multiple Choice)
4.7/5 (72)
(72) Answer the following questions using the information below:
Munoz, Inc., produces a special line of plastic toy racing cars. Munoz, Inc., produces the cars in batches. To manufacture a batch of the cars, Munoz, Inc., must set up the machines and molds. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and molds for different styles of car.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with respect to the number of setup-hours. The following information pertains to June 2015:
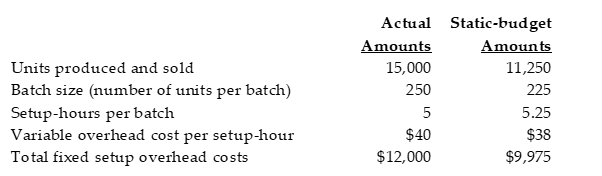 -Calculate the flexible-budget variance for variable overhead setup costs.
 (Multiple Choice)
4.7/5 (76)
(76) The flexible budget enables to highlight the differences ________.
(Multiple Choice)
4.8/5 (75)
(75) When variances are immaterial,which of the following statements is true of the journal entry to write-off the variable overhead variance accounts?
(Multiple Choice)
4.9/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)