



 Chat with AI
Exam 8: Flexible Budgets, overhead Cost Variances, and Management Control

Exam 1: The Manager and Management Accounting195 Questions
Exam 2: An Introduction to Cost Terms and Purposes224 Questions
Exam 3: Cost-Volume-Profit Analysis208 Questions
Exam 4: Job Costing199 Questions
Exam 5: Activity-Based Costing and Activity-Based Management176 Questions
Exam 6: Master Budget and Responsibility Accounting226 Questions
Exam 7: Flexible Budgets, direct-Cost Variances, and Management Control180 Questions
Exam 8: Flexible Budgets, overhead Cost Variances, and Management Control176 Questions
Exam 9: Inventory Costing and Capacity Analysis211 Questions
Exam 10: Determining How Costs Behave190 Questions
Exam 11: Decision Making and Relevant Information218 Questions
Exam 12: Strategy, balanced Scorecard, and Strategic Profitability Analysis172 Questions
Exam 13: Pricing Decisions and Cost Management210 Questions
Exam 14: Cost Allocation, customer-Profitability Analysis, and Sales-Variance Analysis167 Questions
Exam 15: Allocation of Support-Department Costs, common Costs, and Revenues150 Questions
Exam 16: Cost Allocation: Joint Products and Byproducts151 Questions
Exam 17: Process Costing149 Questions
Exam 18: Spoilage, rework, and Scrap153 Questions
Exam 19: Balanced Scorecard: Quality and Time151 Questions
Exam 20: Inventory Management, just-In-Time, and Simplified Costing Methods151 Questions
Exam 21: Capital Budgeting and Cost Analysis151 Questions
Exam 22: Management Control Systems, transfer Pricing, and Multinational Considerations153 Questions
Exam 23: Performance Measurement, compensation, and Multinational Considerations151 Questions
Select questions type


Osium Company made the following journal entry: Variable Manufacturing Overhead Allocated 200,000 Variable Manufacturing Overhead Efficiency Variance 60,000 Variable Manufacturing Overhead Control 250,000 Variable Manufacturing Overhead Spending Variance 10,000 Which of the following statements is true of the given journal entry?

Free
(Multiple Choice)
4.8/5  (68)
(68) Correct Answer: Verified
D
Skytalk Company manufactures weathervanes.The 2015 operating budget is based on the production of 5,300 weathervanes with 1.25 machine-hour allowed per weathervane.Variable manufacturing overhead is anticipated to be $145,750.
Actual production for 2015 was 5,250 weathervanes using 6,050 machine-hours.Actual variable costs were $21.75 per machine-hour.
Required:
Calculate the variable overhead spending and the efficiency variances.
Free
(Essay)
4.7/5 (68)
(68) Correct Answer:Verified
VerifiedBudgeted variable overhead per hour = $145,750 ÷ (5,300 × 1.25)machine-hours = $22
Spending variance = ($21.75 − $22)× 6,050 = $1,512.50 favorable
Efficiency variance = [6,050 − (5,300 × 1.25)] × $22 = $12,650 favorable
Possible reasons for the larger actual materials-handling labor-hours per batch include the possibility of unmotivated,inexperienced,and underskilled employees
Free
(True/False)
4.9/5 (80)
(80) Correct Answer:Verified
VerifiedTrue
Radon Corporation manufactured 25,000 grooming kits for horses during March.The following fixed overhead data pertain to March: Actual Static Budget Production 33,000 units 30,000 units Machine-hours 6,100 hours 6,000 hours Fixed overhead costs for March \ 153,000 \ 144,000
-What is the fixed overhead spending variance?
(Multiple Choice)
4.8/5 (96)
(96) Which of the following is a component of sales-volume variance?
(Multiple Choice)
4.9/5 (76)
(76) In flexible budgets,costs that remain the same regardless of the output levels within the relevant range are ________.
(Multiple Choice)
4.9/5 (78)
(78) Define variable overhead spending variance.Briefly explain why a favorable variable overhead spending variance may not always be desirable.
(Essay)
4.9/5 (80)
(80) Answer the following questions using the information below:
Roberson Corporation manufactured 30,000 ice chests during September. The variable overhead cost-allocation base is $11.25 per machine-hour. The following variable overhead data pertain to September:
Actual Budgeted Production 30,000 units 24,000 units Machine-hours 15,000 hours 10,800 hours Variable overhead cost per machine-hour: \ 11.00 \ 11.25
-What is the flexible-budget amount?
(Multiple Choice)
4.8/5 (74)
(74) Variance analysis of fixed nonmanufacturing costs,such as distribution costs,can also be useful when planning for capacity.
(True/False)
4.8/5 (85)
(85) Answer the following questions using the information below:
Russo Corporation manufactured 16,000 air conditioners during November. The overhead cost-allocation base is $31.50 per machine-hour. The following variable overhead data pertain to November:
Actual Budgeted Production 16,000 units 18,000 units Machine-hours 7,875 hours 9,000 hours Variable overhead cost per machine-hour: \ 31.00 \ 31.50
-What is the flexible-budget amount?
(Multiple Choice)
4.8/5 (83)
(83) An unfavorable price variance for materials-handling labor indicates that the actual cost per materials-handling labor-hour is less than the budgeted cost per materials-handling labor-hour.
(True/False)
4.8/5 (70)
(70) List the four steps to develop budgeted variable overhead cost-allocation.
(Short Answer)
4.7/5 (70)
(70) Answer the following questions using the information below:
Munoz, Inc., produces a special line of plastic toy racing cars. Munoz, Inc., produces the cars in batches. To manufacture a batch of the cars, Munoz, Inc., must set up the machines and molds. Setup costs are batch-level costs because they are associated with batches rather than individual units of products. A separate Setup Department is responsible for setting up machines and molds for different styles of car.
Setup overhead costs consist of some costs that are variable and some costs that are fixed with respect to the number of setup-hours. The following information pertains to June 2015:
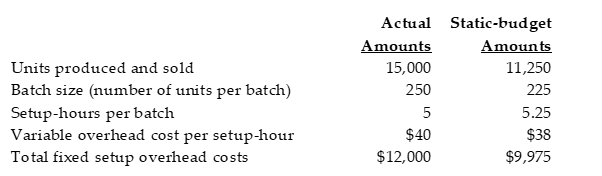 -Calculate the production-volume variance for fixed overhead setup costs.
 (Multiple Choice)
4.9/5 (68)
(68) What are the arguments for prorating a production-volume variance that has been deemed to be material among work-in-process,finished goods,cost and cost of goods sold as opposed to writing it all off to cost of goods sold?
(Essay)
5.0/5 (70)
(70) Different management levels in Bates,Inc.,require varying degrees of managerial accounting information.Because of the need to comply with the managers' requests,four different variances for manufacturing overhead are computed each month.The information for the September overhead expenditures is as follows:
Bud geted output units 3,200 units Bud geted fixed manufacturing overhead \ 20,000 Bud geted variable manufacturing overhead \ 5 per direct labor hour Bud geted direct manufacturing labor hours 2 hours per unit Fixed manufacturing costs incurred \ 26,000 Direct manufacturing labor hours used 7,200 Variable manufacturing costs incurred \ 35,600 Actual units manufactured 3,400 Required:
a.Compute a 4-variance analysis for the plant controller.
b.Compute a 3-variance analysis for the plant manager.
c.Compute a 2-variance analysis for the corporate controller.
d.Compute the flexible-budget variance for the manufacturing vice president.
(Essay)
4.9/5 (79)
(79) Xenon Company makes watches.The fixed overhead costs for 2015 total $648,000.The company uses direct labor-hours for fixed overhead allocation and anticipates 21,600 hours during the year for 540,000 units.An equal number of units are budgeted for each month.
During October,48,000 watches were produced and $52,000 was spent on fixed overhead.
Required:
a.Determine the fixed overhead rate for 2015 based on the units of input.
b.Determine the fixed overhead static-budget variance for October.
c.Determine the production-volume overhead variance for October.
(Essay)
4.7/5 (78)
(78) Can the variable overhead efficiency variance
a.be computed the same way as the efficiency variance for direct-cost items?
b.be interpreted the same way as the efficiency variance for direct-cost items? Explain.
(Essay)
4.9/5 (69)
(69) Which of the following is the correct mathematical expression to calculate the fixed overhead spending variance?
(Multiple Choice)
4.8/5 (84)
(84) An unfavorable production-volume variance indicates an overallocation of fixed overhead costs.
(True/False)
4.8/5 (78)
(78) Lump-sum fixed costs of acquiring capacity decrease automatically if the capacity needed turns out to be less than the capacity acquired.
(True/False)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)