



 Chat with AI
Exam 14: Cost Management

Exam 1: Introduction to Management Accounting78 Questions
Exam 2: An Introduction to Cost Terms and Concepts79 Questions
Exam 3: Cost-Volume-Profit Analysis121 Questions
Exam 4: Measuring Relevant Costs and Revenues for Decision-Making82 Questions
Exam 5: Pricing Decisions and Profitability Analysis62 Questions
Exam 6: Capital Investment Decisions110 Questions
Exam 7: Cost Assignment81 Questions
Exam 8: Activity-Based Costing108 Questions
Exam 9: The Budgeting Process120 Questions
Exam 10: Management Control Systems83 Questions
Exam 11: Standard Costing and Variance Analysis95 Questions
Exam 12: Divisional Financial Performance Measurement86 Questions
Exam 13: Transfer Pricing in Divisionalized Companies63 Questions
Exam 14: Cost Management156 Questions
Exam 15: Strategic Performance Management49 Questions
Select questions type


What is kaizen costing? How does activity analysis help reduce costs?
(Essay)
4.8/5  (78)
(78) _____ are the resources consumed by the activity in producing its output.
(Multiple Choice)
4.8/5 (80)
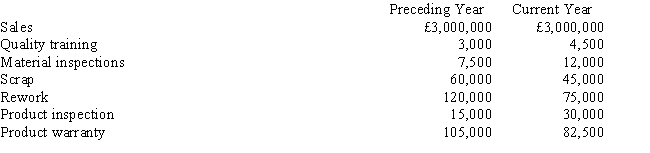
(80) At the beginning of the year, Grant Company initiated a quality improvement program. The program was successful in reducing scrap and rework costs. To help assess the impact of the quality improvement program, the following data were collected for the current and preceding years: As a result of quality improvements, profits have increased by
(Multiple Choice)
4.9/5 (77)
(77) Which of the following process dimensions of the activity-based management model deals with "why"?
(Multiple Choice)
4.9/5 (72)
(72) Each unit of product requires 16 pounds of material. Due to scrap and rework, each unit has been averaging 18 pounds of material. The material costs £6 per pound. If the company wants to reduce nonvalue-added costs by 25 percent next year, the currently attainable standard for material would be
(Multiple Choice)
4.9/5 (75)
(75) The following reasons have been offered for holding inventories:
1. To balance ordering or setup costs and carrying costs
2. To satisfy customer demand (e.g., meet delivery dates)
3. To avoid shutting down manufacturing facilities because of
(a) machine failure
(b) defective parts
(c) unavailable parts
4. Unreliable production processes
5. To take advantage of discounts
6. To hedge against future price increases
Required:
a. Explain how the JIT approach responds to each of these reasons and, consequently, argues for insignificant levels of inventories.
b. The theory of constraints (TOC) criticizes the JIT approach to inventory management, arguing that it fails to protect throughput. Explain what this means and describe how TOC addresses this issue.
(Essay)
4.7/5 (76)
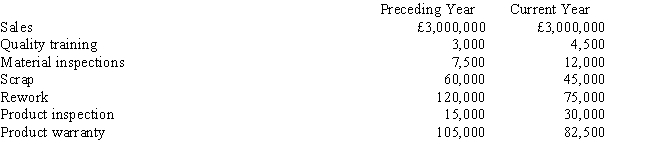
(76) At the beginning of the year, Grant Company initiated a quality improvement program. The program was successful in reducing scrap and rework costs. To help assess the impact of the quality improvement program, the following data were collected for the current and preceding years: For the current year, prevention costs are what percentage of sales?
(Multiple Choice)
4.9/5 (92)
(92) _____ is the effort expended to identify those factors that are the root causes of activity costs.
(Multiple Choice)
4.7/5 (97)
(97) Rollo Company has developed cost formulas for the drivers of the following production activities: The activity levels are projected to be as follows:
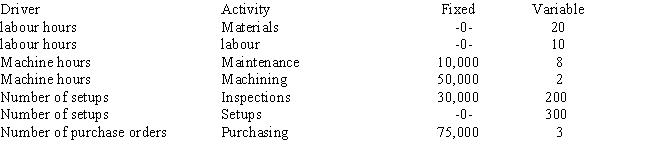 What is budgeted for this projected activity level?
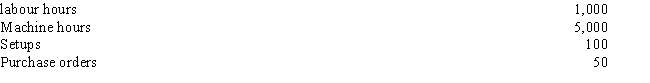
What is budgeted for this projected activity level?
(Multiple Choice)
4.8/5 (90)
(90) Which of the following is not true about assigning rewards in activity-based responsibility accounting?
(Multiple Choice)
4.8/5 (90)
(90) With JIT manufacturing, the major variable cost remaining is
(Multiple Choice)
4.7/5 (63)
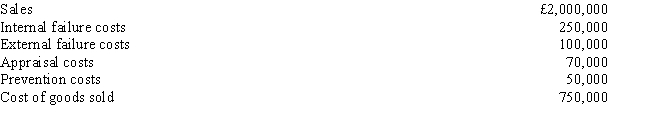
(63) The following information pertains to Kanyon, SA., for 2004: Quality costs are what percentage of sales?
(Multiple Choice)
5.0/5 (83)
(83) A time-and-motion study revealed that it should take 3 hours to produce a product that currently takes 7.5 hours to produce. labour is £18 per hour. The nonvalue-added costs are
(Multiple Choice)
4.8/5 (80)
(80) A company keeps 20 days of materials inventory on hand to avoid shutdowns due to materials shortages. Carrying costs average £4,000 per day. A competitor keeps 10 days of inventory on hand, and the competitor's carrying costs average £2,000 per day. The value-added costs are
(Multiple Choice)
4.9/5 (81)
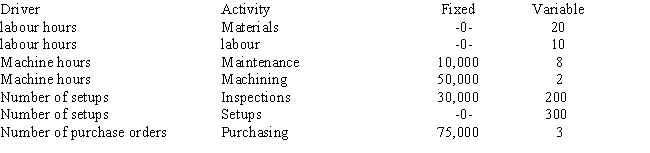
(81) Rollo Company has developed cost formulas for the drivers of the following production activities: If the actual activity was 20 setups and the actual fixed cost for inspections was £28,000 and the variable cost for inspections was £5,000, the total variance for inspections is
(Multiple Choice)
4.7/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)