



 Chat with AI
Exam 14: Cost Management

Exam 1: Introduction to Management Accounting78 Questions
Exam 2: An Introduction to Cost Terms and Concepts79 Questions
Exam 3: Cost-Volume-Profit Analysis121 Questions
Exam 4: Measuring Relevant Costs and Revenues for Decision-Making82 Questions
Exam 5: Pricing Decisions and Profitability Analysis62 Questions
Exam 6: Capital Investment Decisions110 Questions
Exam 7: Cost Assignment81 Questions
Exam 8: Activity-Based Costing108 Questions
Exam 9: The Budgeting Process120 Questions
Exam 10: Management Control Systems83 Questions
Exam 11: Standard Costing and Variance Analysis95 Questions
Exam 12: Divisional Financial Performance Measurement86 Questions
Exam 13: Transfer Pricing in Divisionalized Companies63 Questions
Exam 14: Cost Management156 Questions
Exam 15: Strategic Performance Management49 Questions
Select questions type


A firm's warranty costs are £125,000 per year. A competitor's warranty costs are £25,000 per year. The value-added costs are
(Multiple Choice)
4.8/5  (88)
(88) Using the abbreviations listed below, indicate for each of the costs whether the cost should be classified as:
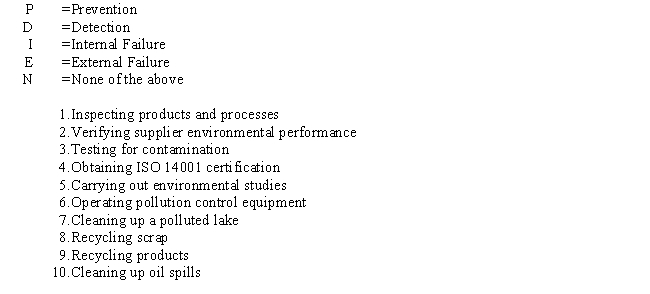
(Essay)
4.8/5 (85)
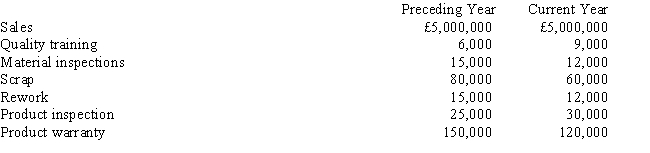
(85) At the beginning of the year, Randy Company initiated a quality improvement program. The program was successful in reducing scrap and rework costs. To help assess the impact of the quality improvement program, the following data were collected for the current and preceding years:
Required:
 a.
Compute each category of quality costs as a percentage of sales for each year.
Prevention costs
Appraisal costs
Internal failure costs
External failure costs
b.
How much has profit increased as a result of quality improvements?
c.
If quality costs can be reduced to 2.5 percent of sales, how much additional profit would result?
a.
Compute each category of quality costs as a percentage of sales for each year.
Prevention costs
Appraisal costs
Internal failure costs
External failure costs
b.
How much has profit increased as a result of quality improvements?
c.
If quality costs can be reduced to 2.5 percent of sales, how much additional profit would result? (Essay)
4.8/5 (83)
(83) According to the life-cycle cost budgeting model, 90 percent of costs are incurred during the
(Multiple Choice)
4.9/5 (71)
(71) Larry Ltd.has developed ideal standards for four activities: labour, materials, inspection, and receiving. Information is as follows: The actual prices paid per unit of each activity driver were equal to the standard prices. The value-added costs for labour are
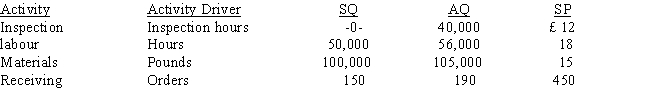
(Multiple Choice)
4.7/5 (76)
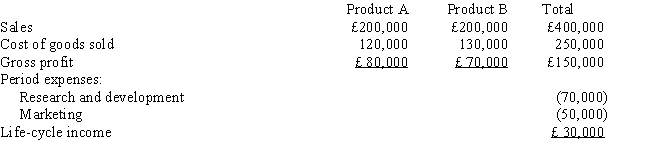
(76) Brad Company developed the following budgeted life-cycle income statement for two proposed products. Each product's life cycle is expected to be two years. A 10 percent return on sales is required for new products. Because the proposed products did not have a 10 percent return on sales, the products were going to be dropped.
Relative to Product B, Product A requires more research and development costs but fewer resources to market the product. Sixty percent of the research and development costs are traceable to Product A, and 30 percent of the marketing costs are traceable to Product A.
If research and development costs and marketing costs are traced to each product, life-cycle income for Product A would be
(Multiple Choice)
4.9/5 (70)
(70) Craig, SA., sells one of its products for £500 each. Sales volume averages 1,000 units per year. Recently, its main competitor priced their competing product at 10 percent below Craig's price. Craig expects its sales to drop dramatically unless it matches the competitor's price. Despite the anticipated price reduction, Craig would like to maintain its current profit per unit.
Information regarding the inputs required to produce 1,000 units of product is as follows:
Required:
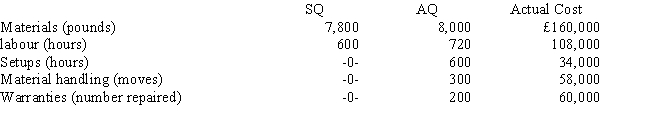 a.
Calculate the target cost for maintaining current market share and profitability.
b.
Calculate the nonvalue-added cost per unit.
c.
If nonvalue-added costs can be reduced to zero, can the target cost be achieved?
a.
Calculate the target cost for maintaining current market share and profitability.
b.
Calculate the nonvalue-added cost per unit.
c.
If nonvalue-added costs can be reduced to zero, can the target cost be achieved? (Essay)
4.9/5 (93)
(93) In comparison to a traditional environment, a JIT environment has more overhead assigned by
(Multiple Choice)
4.9/5 (84)
(84) Describe how the activity-based management model combines the process and costing views. What are the steps involved in each? What are the objectives of the activity-based management system?
(Essay)
4.7/5 (84)
(84) Answer the following questions pertaining to just-in-time inventory management:
a.
Identify key elements of the JIT philosophy.
b.
What elements of the JIT approach contribute to reducing materials inventory?
c.
Why do proponents of JIT believe inventory is an enemy?
(Essay)
4.9/5 (85)
(85) Which of the following process dimensions of the activity-based management model deals with "what"?
(Multiple Choice)
4.8/5 (90)
(90) Which of the following is NOT an expected outcome of activity analysis?
(Multiple Choice)
4.9/5 (88)
(88) For nonvalue-added activities that are unnecessary, the standard quantity is
(Multiple Choice)
4.8/5 (80)
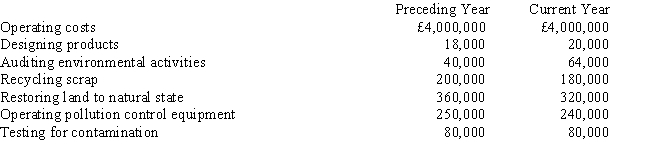
(80) At the beginning of the year, Paris, SA., initiated an environmental cost reduction program. To help assess the impact of the environmental cost reduction improvement program, the following data was collected for the current and preceding year:
Required:
 a.
Compute each category of environmental quality costs as a percentage of operating costs for each year.
Prevention costs
Detection costs
Internal failure costs
External failure costs
b.
How much has profit increased as a result of the environmental cost reduction improvements?
a.
Compute each category of environmental quality costs as a percentage of operating costs for each year.
Prevention costs
Detection costs
Internal failure costs
External failure costs
b.
How much has profit increased as a result of the environmental cost reduction improvements? (Essay)
4.7/5 (88)
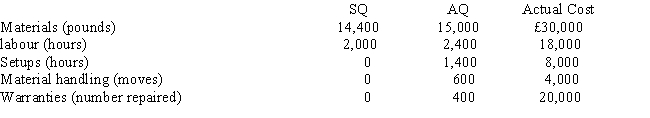
(88) Clark, SA., sells one of its products for £150 each. Sales volume averages 800 units per year. Recently, its main competitor reduced the price of its product to £130. Clark expects sales to drop dramatically unless it matches the competitor's price. In addition, the current profit per unit must be maintained. Information about the product (for production of 800) is as follows:
Required:
 a.
Calculate the target cost for maintaining current market share and profitability.
b.
Calculate the nonvalue-added cost per unit.
c.
If nonvalue-added costs can be reduced to zero, can the target cost be achieved?
a.
Calculate the target cost for maintaining current market share and profitability.
b.
Calculate the nonvalue-added cost per unit.
c.
If nonvalue-added costs can be reduced to zero, can the target cost be achieved? (Essay)
4.9/5 (71)
(71) labour and overhead incurred for rework of defective products is a(n)
(Multiple Choice)
4.8/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)