



 Chat with AI
Exam 13: Transfer Pricing in Divisionalized Companies

Exam 1: Introduction to Management Accounting78 Questions
Exam 2: An Introduction to Cost Terms and Concepts79 Questions
Exam 3: Cost-Volume-Profit Analysis121 Questions
Exam 4: Measuring Relevant Costs and Revenues for Decision-Making82 Questions
Exam 5: Pricing Decisions and Profitability Analysis62 Questions
Exam 6: Capital Investment Decisions110 Questions
Exam 7: Cost Assignment81 Questions
Exam 8: Activity-Based Costing108 Questions
Exam 9: The Budgeting Process120 Questions
Exam 10: Management Control Systems83 Questions
Exam 11: Standard Costing and Variance Analysis95 Questions
Exam 12: Divisional Financial Performance Measurement86 Questions
Exam 13: Transfer Pricing in Divisionalized Companies63 Questions
Exam 14: Cost Management156 Questions
Exam 15: Strategic Performance Management49 Questions
Select questions type


Which of the following types of transfer prices do NOT encourage the selling division to be efficient?
(Multiple Choice)
4.8/5  (80)
(80) Halber Industries is a decentralized company that evaluates its divisions based on ROI. The Brock Division has the capacity to make 2,000 units of a component. The Brock Division's variable costs are £80 per unit.
The Cliff Division can use the Brock component in the manufacturing of one of its own products. The Cliff Division would incur £60 of variable costs to convert the component into its own product, which sells for £300.
Required:
The following requirements are independent of each other:
a.
Assume the Brock Division can sell all of the components that it produces for £180 each. The Cliff Division needs 100 units. What is the correct transfer price?
b.
Assume the Brock Division can sell 1,800 units at £260. Any excess capacity will be unused unless the units are purchased by the Cliff Division, which could use up to 100 units.
Determine the minimum transfer price that the Brock Division would be willing to accept.
Determine the maximum transfer price that the Cliff Division would be willing to pay.
(Essay)
4.8/5 (90)
(90) When an outside market exists for an intermediate product that is perfectly competitive, the ideal method of transfer pricing is often:
(Multiple Choice)
4.9/5 (86)
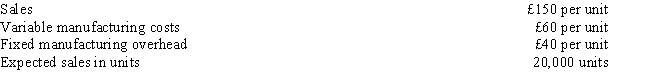
(86) Brown Industries has two divisions: the Hank Division and the Murray Division. Information about a component that the Hank Division produces is as follows:
The Hank Division can produce up to 22,000 components per year. The Murray Division needs 1,000 units of the component for a product it manufactures.
Required:
 a.
Determine the minimum transfer price that the selling division would be willing to accept.
b.
Determine the maximum transfer price that the buying division would be willing to pay.
c.
If the Hank Division did not have excess capacity, what would be the correct transfer price?
a.
Determine the minimum transfer price that the selling division would be willing to accept.
b.
Determine the maximum transfer price that the buying division would be willing to pay.
c.
If the Hank Division did not have excess capacity, what would be the correct transfer price? (Essay)
5.0/5 (85)
(85) British International has a division in the United States that produces tires for automobiles. These tires are transferred to an automobile division in Germany. The tires can be (and are) sold externally in the United States for £60 each. The cost to produce a tire is £40. It costs £3 per tire for shipping and £5 per tire for import duties. When the tires are sold externally, British International spends £2 per tire for commissions and an average of £1 per tire for advertising. An acceptable markup is 30 percent of costs. What is the transfer price if the cost-plus method is used?
(Multiple Choice)
4.9/5 (80)
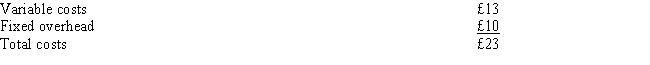
(80) MultiCorp is a decentralized company that rewards divisional managers based on ROI. The Blue Division produces a component that is used by Jam Division. Blue's unit cost of manufacturing 5,000 components (capacity) is:
Blue can sell 4,000 units on the open market for £30 by incurring selling costs of £2 per unit.
An outside supplier has offered Jam 5,000 units of this same component for £29. Orders of less than 5,000 units would cost the Jam Division £31 each. Jam needs the 5,000 components to make finished goods, which provide a total contribution of £245,000 excluding the cost of the component.
The Jam Division's manager has approached the Blue Division manager with an offer to purchase the entire 5,000 units from the Blue Division for a total cost of £130,000 (£26 per unit). If this internal transaction is completed, the Blue Division would not incur the £2 unit selling costs.
Required: Analyze the effect of this offer considering the following:
 a.
Is the Blue Division better off by accepting the offer to sell 5,000 units internally for £26 each?
b.
How much is the company as a whole better or worse off if the transaction is completed internally as opposed to each division dealing externally? Justify your answer.
c.
What is the highest price the Jam Division would consider paying the Blue Division for the component?
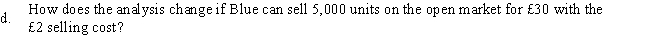
a.
Is the Blue Division better off by accepting the offer to sell 5,000 units internally for £26 each?
b.
How much is the company as a whole better or worse off if the transaction is completed internally as opposed to each division dealing externally? Justify your answer.
c.
What is the highest price the Jam Division would consider paying the Blue Division for the component?
(Essay)
4.9/5 (72)
(72) A selling division produces components for a buying division that is considering accepting a special order for the products it produces. The selling division has excess capacity. The minimum price the selling division would be willing to accept is
(Multiple Choice)
4.9/5 (96)
(96) Figure 4
The Simonds Division produces a component that is used by the Allen Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 400,000 components
Other costs incurred by the Simonds Division are as follows:
 The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Refer to Figure 4. The effect on firmwide income if 50,000 components are transferred internally at £22.50 each instead of purchased from an external supplier at £34 per unit would be a
The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Refer to Figure 4. The effect on firmwide income if 50,000 components are transferred internally at £22.50 each instead of purchased from an external supplier at £34 per unit would be a (Multiple Choice)
4.7/5 (82)
(82) Figure 6
Callahan Industries is a decentralized company that evaluates its divisions based on ROI. The Jones Division has the capacity to make 5,000 units of a component. The Jones Division's variable costs are £200 per unit.
The Thomas Division can use the component in one of its products. The Thomas Division would incur £100 of variable costs to put the component in its own product that sells for £500.
-Refer to Figure 6 above. Assume the Jones Division can sell 4,000 units at £420. Any excess capacity will be unused unless the units are purchased by the Thomas Division, which could use up to 200 units. The maximum transfer price that the Thomas Division would be willing to pay would be
(Multiple Choice)
4.8/5 (72)
(72) Figure 5
Allied Industries has two divisions: the Bradley Division and the Rommel Division. Information about the component that the Bradley Division produces is as follows:
The Bradley Division can produce up to 12,000 components per year. The Rommel Division needs 800 units of the component for a product it manufactures
-.Refer to Figure 5. The minimum transfer price that the Bradley Division would be willing to accept is 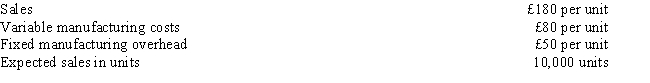
(Multiple Choice)
4.9/5 (82)
(82) Chantilly Industries has two divisions: the Triangle Division and the Square Division. The Triangle Division produces a component that is used by the Square Division. Information about that component is as follows:
The Triangle Division can produce up to 15,000 components per year. The Square Division needs 1,500 units of the component for a product it manufactures.
Required:
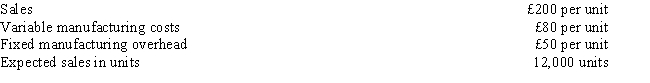 a.
Determine the minimum transfer price that the Triangle Division would accept.
b.
Determine the maximum transfer price that the Square Division would pay.
c.
If the Triangle Division produces and sells 15,000 units in a highly competitive market, what would be the correct transfer price?
a.
Determine the minimum transfer price that the Triangle Division would accept.
b.
Determine the maximum transfer price that the Square Division would pay.
c.
If the Triangle Division produces and sells 15,000 units in a highly competitive market, what would be the correct transfer price? (Essay)
4.9/5 (69)
(69) A selling division produces components for a buying division that is considering accepting a special order for the products it produces. The selling division has excess capacity. The maximum price the buying division would be willing to accept is
(Multiple Choice)
4.8/5 (77)
(77) Figure 6
Callahan Industries is a decentralized company that evaluates its divisions based on ROI. The Jones Division has the capacity to make 5,000 units of a component. The Jones Division's variable costs are £200 per unit.
The Thomas Division can use the component in one of its products. The Thomas Division would incur £100 of variable costs to put the component in its own product that sells for £500.
-Refer to Figure 6 above. The Jones Division can sell all that it produces for £360 each. The Jones Division needs 200 units. What is the correct transfer price?
(Multiple Choice)
4.8/5 (86)
(86) Figure 1
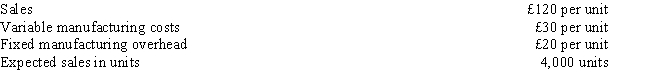
Universe Industries has two divisions: the Haley Division and the Comet Division. Information about a component that the Haley Division produces is as follows:
The Haley Division can produce up to 5,000 components per year. The Comet Division needs 200 units of the component for a product it manufactures.
-Refer to Figure 1 above. The minimum transfer price that the Haley Division would be willing to accept is
(Multiple Choice)
4.9/5 (76)
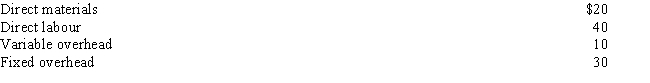
(76) Miggs Manufacturing has one plant located in Belgium and another plant located in the United States. The Belgium plant manufactures a component used in a finished product manufactured at the U.S. plant. Currently, the Belgium plant is operating at 70 percent capacity. In Belgium, the income tax rate is 42 percent; in the United States, the corporate income tax rate is 35 percent. The market price of the component is $200 and the Belgium plant's costs to manufacture the component are as follows:
What is the maximum transfer price that the U.S. division would be willing to pay?
(Multiple Choice)
4.9/5 (74)
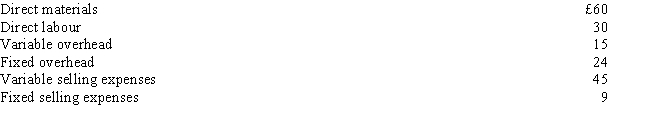
(74) Pautner Company had the following historical accounting data per unit: The units are normally transferred internally from Division A to Division B. The units also may be sold externally for £210 per unit. The minimum profit level accepted by the company is a markup of 30 percent. There were no beginning or ending inventories.
If variable manufacturing costs without a fixed fee are used as the transfer price, Division A's transfer price would be
(Multiple Choice)
4.8/5 (83)
(83) _____ exists when divisions, acting in their own best interests, set transfer prices or make decisions based on transfer prices that are not in the best interest of the organization as a whole.
(Multiple Choice)
4.8/5 (89)
(89) If the divisions exchanging goods are located in different countries with different tax rate structures, the key determinant of transfer prices could be based largely on:
(Multiple Choice)
4.8/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)