



 Chat with AI
Exam 13: Transfer Pricing in Divisionalized Companies

Exam 1: Introduction to Management Accounting78 Questions
Exam 2: An Introduction to Cost Terms and Concepts79 Questions
Exam 3: Cost-Volume-Profit Analysis121 Questions
Exam 4: Measuring Relevant Costs and Revenues for Decision-Making82 Questions
Exam 5: Pricing Decisions and Profitability Analysis62 Questions
Exam 6: Capital Investment Decisions110 Questions
Exam 7: Cost Assignment81 Questions
Exam 8: Activity-Based Costing108 Questions
Exam 9: The Budgeting Process120 Questions
Exam 10: Management Control Systems83 Questions
Exam 11: Standard Costing and Variance Analysis95 Questions
Exam 12: Divisional Financial Performance Measurement86 Questions
Exam 13: Transfer Pricing in Divisionalized Companies63 Questions
Exam 14: Cost Management156 Questions
Exam 15: Strategic Performance Management49 Questions
Select questions type


Which of the following is a legitimate disadvantage of negotiated transfer pricing?
(Multiple Choice)
4.8/5  (78)
(78) Garland Industries is a decentralized company that evaluates its divisions based on ROI. The Shelly Division has the capacity to make 4,000 units of a component. The Shelly Division's variable costs are £160 per unit.
The Blake Division can use the Shelly component in the manufacturing of one of its own products. The Blake Division would incur £170 of variable costs to convert the component into its own product, which sells for £600.
Required:
The following requirements are independent of each other:
a.
Assume the Shelly Division can sell all of the components that it produces for £400 each. The Blake Division needs 200 units. What is the correct transfer price?
b.
Assume the Shelly Division can sell 3,500 units at £440. Any excess capacity will be unused unless the units are purchased by the Blake Division, which could use up to 200 units.
Determine the minimum transfer price that the Shelly Division would be willing to accept.
Determine the maximum transfer price that the Blake Division would be willing to pay.
(Essay)
4.7/5 (81)
(81) Figure 4
The Simonds Division produces a component that is used by the Allen Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 400,000 components
Other costs incurred by the Simonds Division are as follows:
 The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Figure 4 The Simonds Division produces a component that is used by the Allen Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 400,000 components
Other costs incurred by the Simonds Division are as follows:
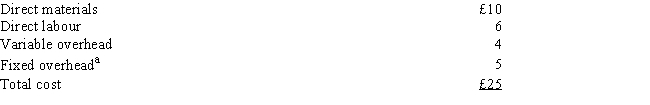 The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
Refer to Figure 4. The minimum transfer price that the Simonds Division would accept is

The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Figure 4 The Simonds Division produces a component that is used by the Allen Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 400,000 components
Other costs incurred by the Simonds Division are as follows:
The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
Refer to Figure 4. The minimum transfer price that the Simonds Division would accept is
(Multiple Choice)
4.8/5 (74)
(74) Figure 5
Allied Industries has two divisions: the Bradley Division and the Rommel Division. Information about the component that the Bradley Division produces is as follows:
The Bradley Division can produce up to 12,000 components per year. The Rommel Division needs 800 units of the component for a product it manufactures
-Refer to Figure 5 above. The maximum transfer price that the Rommel Division would be willing to pay is
(Multiple Choice)
4.9/5 (81)
(81) Figure 5
Allied Industries has two divisions: the Bradley Division and the Rommel Division. Information about the component that the Bradley Division produces is as follows:
The Bradley Division can produce up to 12,000 components per year. The Rommel Division needs 800 units of the component for a product it manufactures
-Refer to Figure 5 above. If the selling division did NOT have excess capacity, the minimum transfer price the selling division would be willing to accept would be
(Multiple Choice)
4.9/5 (76)
(76) _____ is when the transfer price is computed equal to a sales price received by the reseller less an appropriate markup.
(Multiple Choice)
4.9/5 (81)
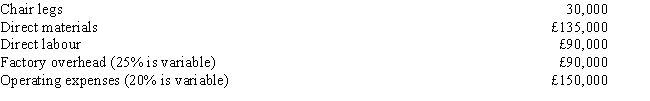
(81) The Kelly Division of Zimmer Company sells all of its output to the Finishing Division of the company. The only product of the Kelly Division is chair legs that are used by the Finishing Division. The retail price of the legs is £20 per leg. Each chair completed by the Finishing Division requires four legs. Production quantity and cost data for 2004 are as follows:
Required:
Compute the transfer price for a chair leg using:
 a.
market price.
b.
variable product costs plus a fixed fee of 20 percent.
c.
full cost plus 20 percent markup.
d.
variable costs.
e.
full cost plus 10 percent markup.
a.
market price.
b.
variable product costs plus a fixed fee of 20 percent.
c.
full cost plus 20 percent markup.
d.
variable costs.
e.
full cost plus 10 percent markup. (Essay)
4.9/5 (71)
(71) Figure 3
The Adam Division produces a component that is used by the West Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 250,000 components
Other costs incurred by the Adam Division are as follows:
 The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3 above. The maximum transfer price that the West Division would be willing to pay is
The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3 above. The maximum transfer price that the West Division would be willing to pay is (Multiple Choice)
4.9/5 (74)
(74) Figure 2
Klaehn Industries is a decentralized company that evaluates its divisions based on ROI. The Fahl Division has the capacity to make 1,000 units of a component. The Fahl Division's variable costs are £40 per unit.
The Melton Division can use the component in one of its products. The Melton Division would incur £50 of variable costs to convert the component into its own product that sells for £160.
-Refer to Figure 2 above. Assume the Fahl Division can sell 800 units at £120 each. Any excess capacity will be unused unless the units are purchased by the Melton Division, which could use up to 100 units. The maximum transfer price that the Melton Division would be willing to pay would be
(Multiple Choice)
4.7/5 (71)
(71) A transfer pricing system should satisfy which of the following objectives?
(Multiple Choice)
4.9/5 (79)
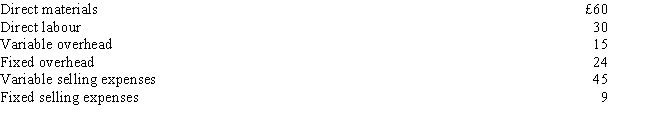
(79) Pautner Company had the following historical accounting data per unit: The units are normally transferred internally from Division A to Division B. The units also may be sold externally for £210 per unit. The minimum profit level accepted by the company is a markup of 30 percent. There were no beginning or ending inventories.
What would be the transfer price if Division X uses full cost plus markup?
(Multiple Choice)
4.9/5 (61)
(61) Figure 3
The Adam Division produces a component that is used by the West Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 250,000 components
Other costs incurred by the Adam Division are as follows:
The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3 above. The effect on firmwide income if 40,000 components are transferred internally at £56 each instead of purchased from an external supplier at £80 per unit would be a
The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3 above. The effect on firmwide income if 40,000 components are transferred internally at £56 each instead of purchased from an external supplier at £80 per unit would be a (Multiple Choice)
4.9/5 (72)
(72) Figure 2
Klaehn Industries is a decentralized company that evaluates its divisions based on ROI. The Fahl Division has the capacity to make 1,000 units of a component. The Fahl Division's variable costs are £40 per unit.
The Melton Division can use the component in one of its products. The Melton Division would incur £50 of variable costs to convert the component into its own product that sells for £160.
-Refer to Figure 2. Assume the Fahl Division can sell all that it produces for £100 each. The Melton Division needs 100 units. What is the correct transfer price?
(Multiple Choice)
4.8/5 (96)
(96) Flugel Enterprises is a decentralized company that evaluates its divisions based on their reported return on investment. One of Flugel's divisions, the Pipe division, manufactures pipe fittings that are used by the Equipment division as well as other users outside the organization. Pipe has the capacity to make only 3,000 of these fittings at a variable cost of £12 per fitting. Fixed costs of the Pipe division are £90,000 per period and include costs that are common to other products the Pipe division makes. Fixed costs allocated to the fittings sold to the Equipment division are £24,000 per period.
The Equipment division uses the fittings and incurs £100 per unit of additional variable costs to make the equipment that sells on the open market for £150. Equipment expects to sell 1,000 pieces of equipment this period. Fixed costs of this division related to depreciation on past expenditures are estimated at £30,000.
Fittings like those transferred from Pipe to Equipment sell on the open market for £25 each.
Top management of the organization allows divisions to negotiate transfer prices and has a policy of not inferring with the negotiation process.
Required:
a.
What is the absolute minimum price Pipe would accept from Equipment for the fittings if Pipe has excess capacity? State any assumptions necessary to answer the question.
b.
What is the maximum price Equipment would pay the Pipe division for the fittings?
c.
What is the minimum price Pipe would accept if Pipe is operating at capacity to fill orders for these fittings on the open market?
(Essay)
4.8/5 (73)
(73) Figure 4
The Simonds Division produces a component that is used by the Allen Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 400,000 components
Other costs incurred by the Simonds Division are as follows:
The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Refer to Figure 4. The maximum transfer price that the Allen Division would be willing to pay is
The component usually sells for £35 in the external market. The Simonds Division is capable of producing 500,000 components per year; however, only 400,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The Allen Division has been buying the same component from an external supplier for £34 each. The Allen Division expects to use 50,000 units of the component next year. The manager of the Allen Division has offered to buy 50,000 units from the Simonds Division for £22.50 each.
-Refer to Figure 4. The maximum transfer price that the Allen Division would be willing to pay is (Multiple Choice)
4.9/5 (81)
(81) Figure 1
Universe Industries has two divisions: the Haley Division and the Comet Division. Information about a component that the Haley Division produces is as follows:
The Haley Division can produce up to 5,000 components per year. The Comet Division needs 200 units of the component for a product it manufactures.
-Refer to Figure 1 above. The maximum transfer price that the Comet Division would be willing to pay is
(Multiple Choice)
4.9/5 (88)
(88) The opportunity cost approach to setting a transfer price would set the minimum transfer price as
(Multiple Choice)
4.8/5 (68)
(68) Figure 3
The Adam Division produces a component that is used by the West Division. The cost of manufacturing the component is as follows:
aBased on a practical volume of 250,000 components
Other costs incurred by the Adam Division are as follows:
The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3. The minimum transfer price that the Adam Division would accept is

The component usually sells for £90 in the external market. The Adam Division is capable of producing 250,000 components per year; however, only 200,000 components are expected to be sold next year. The variable selling expenses are avoidable if the component is sold internally.
The West Division has been buying the same component from an external supplier for £80 each. The West Division expects to use 40,000 units of the component next year. The manager of the West Division has offered to buy 40,000 units from the Adam Division for £56 each.
-Refer to Figure 3. The minimum transfer price that the Adam Division would accept is
(Multiple Choice)
4.9/5 (83)
(83) The opportunity cost approach to setting a transfer price would set the maximum transfer price as
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)