



 Chat with AI
Exam 8: Activity-Based Costing

Exam 1: Introduction to Management Accounting78 Questions
Exam 2: An Introduction to Cost Terms and Concepts79 Questions
Exam 3: Cost-Volume-Profit Analysis121 Questions
Exam 4: Measuring Relevant Costs and Revenues for Decision-Making82 Questions
Exam 5: Pricing Decisions and Profitability Analysis62 Questions
Exam 6: Capital Investment Decisions110 Questions
Exam 7: Cost Assignment81 Questions
Exam 8: Activity-Based Costing108 Questions
Exam 9: The Budgeting Process120 Questions
Exam 10: Management Control Systems83 Questions
Exam 11: Standard Costing and Variance Analysis95 Questions
Exam 12: Divisional Financial Performance Measurement86 Questions
Exam 13: Transfer Pricing in Divisionalized Companies63 Questions
Exam 14: Cost Management156 Questions
Exam 15: Strategic Performance Management49 Questions
Select questions type


The Xiang plant has two categories of overhead: maintenance and inspection. Costs expected for these categories for the coming year are as follows:
The plant currently applies overhead using direct labour hours and expected capacity of 50,000 direct labour hours. The following data have been assembled for use in developing a bid for a proposed job:
 Total expected machine hours for all jobs during the year is 25,000, and the total expected number of inspections is 1,500.
Using activity-based costing and the appropriate activity drivers, the total cost of the potential job would be

Total expected machine hours for all jobs during the year is 25,000, and the total expected number of inspections is 1,500.
Using activity-based costing and the appropriate activity drivers, the total cost of the potential job would be
(Multiple Choice)
4.8/5  (77)
(77) Activity-based costing assigns costs to cost object by first
(Multiple Choice)
4.8/5 (72)
(72) All of the following are unit-based activity drivers EXCEPT
(Multiple Choice)
4.9/5 (85)
(85) In a pure activity-based cost system, which of the following might be treated as period costs?
(Multiple Choice)
5.0/5 (92)
(92) _____ are those that are acquired from outside sources, where the terms of acquisition do NOT require any long-term commitment for any given amount of the resource.
(Multiple Choice)
4.8/5 (88)
(88) Figure 4
Wheat Manufacturing has four categories of overhead. The four categories and the expected overhead costs for each category for next year are as follows:
Currently, overhead is applied using a predetermined overhead rate based upon budgeted direct labour hours. For next year, 20,000 direct labour hours are budgeted.
The company has been asked to submit a bid for a proposed job. The plant manager feels that obtaining this job would result in new business in future years. Usually bids are based upon full manufacturing cost plus 15 percent.
Estimates for the proposed job are as follows:
 In the past, full manufacturing cost has been calculated by allocating overhead using a volume-based cost driver--direct labour hours. The plant manager has heard of a new way of applying overhead that uses cost pools and cost drivers.
Expected activity for the four activity-based cost drivers that would be used are as follows:
 -Refer to Figure 4. If Wheat Manufacturing used direct labour hours as the cost driver and the company's bid is full cost plus 15 percent, the company's bid would be

In the past, full manufacturing cost has been calculated by allocating overhead using a volume-based cost driver--direct labour hours. The plant manager has heard of a new way of applying overhead that uses cost pools and cost drivers.
Expected activity for the four activity-based cost drivers that would be used are as follows:
-Refer to Figure 4. If Wheat Manufacturing used direct labour hours as the cost driver and the company's bid is full cost plus 15 percent, the company's bid would be (Multiple Choice)
4.8/5 (84)
(84) Which of the following items would be classified as committed resources (short-term)?
(Multiple Choice)
4.9/5 (78)
(78) Products might consume overhead in different proportions due to
(Multiple Choice)
4.7/5 (89)
(89) Greem, Inc., has identified the following overhead costs and activity drivers for next year: The following are two of the jobs completed during the year:
 The company's normal activity is 2,000 direct labour hours.
If the four activity drivers are used to allocate overhead costs, total overhead allocated to Job 10A would be

The company's normal activity is 2,000 direct labour hours.
If the four activity drivers are used to allocate overhead costs, total overhead allocated to Job 10A would be
(Multiple Choice)
4.9/5 (72)
(72) Figure 4
Wheat Manufacturing has four categories of overhead. The four categories and the expected overhead costs for each category for next year are as follows:
Currently, overhead is applied using a predetermined overhead rate based upon budgeted direct labour hours. For next year, 20,000 direct labour hours are budgeted.
The company has been asked to submit a bid for a proposed job. The plant manager feels that obtaining this job would result in new business in future years. Usually bids are based upon full manufacturing cost plus 15 percent.
Estimates for the proposed job are as follows:
In the past, full manufacturing cost has been calculated by allocating overhead using a volume-based cost driver--direct labour hours. The plant manager has heard of a new way of applying overhead that uses cost pools and cost drivers.
Expected activity for the four activity-based cost drivers that would be used are as follows:
-Refer to Figure 4. If Wheat Manufacturing used activity-based cost drivers to assign overhead and the company's bid is full cost plus 15 percent, the company's bid would be
In the past, full manufacturing cost has been calculated by allocating overhead using a volume-based cost driver--direct labour hours. The plant manager has heard of a new way of applying overhead that uses cost pools and cost drivers.
Expected activity for the four activity-based cost drivers that would be used are as follows:
-Refer to Figure 4. If Wheat Manufacturing used activity-based cost drivers to assign overhead and the company's bid is full cost plus 15 percent, the company's bid would be (Multiple Choice)
5.0/5 (86)
(86) Which of the following items would be classified as committed resources (long-term)?
(Multiple Choice)
4.7/5 (67)
(67) If activity-based costing is used, setups would be classified as a
(Multiple Choice)
4.9/5 (70)
(70) Moss Ltd. has the following activities: creating bills of materials (BOM), studying manufacturing capabilities, improving manufacturing processes, training employees, and designing tooling. The general ledger accounts reveal the following expenditures for manufacturing engineering: The equipment is used for two activities: improving processes and designing tooling. Thirty-five percent of the equipment's time is used for improving processes and 65 percent is used for designing tools. The salaries are for two engineers. One is paid £50,000, while the other earns £25,000. The £50,000 engineer spends 40 percent of his time training employees in new processes and 60 percent of his time on improving processes. The remaining engineer spends equal time on all activities. Supplies are consumed in the following proportions:
 What is the cost assigned to the training employees activity?

What is the cost assigned to the training employees activity?
(Multiple Choice)
4.9/5 (85)
(85) Moss Ltd. has the following activities: creating bills of materials (BOM), studying manufacturing capabilities, improving manufacturing processes, training employees, and designing tooling. The general ledger accounts reveal the following expenditures for manufacturing engineering: The equipment is used for two activities: improving processes and designing tooling. Thirty-five percent of the equipment's time is used for improving processes and 65 percent is used for designing tools. The salaries are for two engineers. One is paid £50,000, while the other earns £25,000. The £50,000 engineer spends 40 percent of his time training employees in new processes and 60 percent of his time on improving processes. The remaining engineer spends equal time on all activities. Supplies are consumed in the following proportions:
 What is the cost assigned to the improving processes activity?

What is the cost assigned to the improving processes activity?
(Multiple Choice)
4.8/5 (68)
(68) Describe the unit level approach to cost behaviour analysis. Discuss the appropriateness of this approach.
(Essay)
4.9/5 (76)
(76) Green, Inc., has identified the following overhead costs and activity drivers for next year: The following are two of the jobs completed during the year:
 The company's normal activity is 2,000 direct labour hours.
If kilowatt hours are used to assign power costs, the amount of power costs assigned to Job 10A would be

The company's normal activity is 2,000 direct labour hours.
If kilowatt hours are used to assign power costs, the amount of power costs assigned to Job 10A would be
(Multiple Choice)
4.9/5 (81)
(81) Figure 3
The Overdale plant has two categories of overhead: maintenance and inspection. Costs expected for these categories for the coming year are as follows:
The plant currently applies overhead using direct labour hours and expected capacity of 80,000 direct labour hours. The following data has been assembled for use in developing a bid for a proposed job:
 Total expected machine hours for all jobs during the year are 40,000, and the total expected number of inspections is 2,500.
-Refer to Figure 3. Using direct labour hours to assign overhead, the total cost of the potential job would be

Total expected machine hours for all jobs during the year are 40,000, and the total expected number of inspections is 2,500.
-Refer to Figure 3. Using direct labour hours to assign overhead, the total cost of the potential job would be (Multiple Choice)
4.8/5 (87)
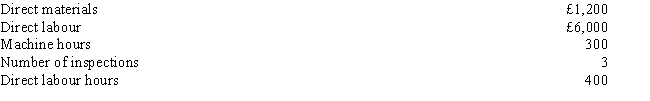
(87) The Greenbriar plant has two categories of overhead: maintenance and inspection. Costs expected for these categories for the coming year are as follows:
The plant currently applies overhead using direct labour hours and expected capacity of 20,000 direct labour hours. The data provided below has been assembled for use in developing a bid for a proposed job. Bid prices are calculated as full manufacturing cost plus 40 percent markup.
 Total expected machine hours for all jobs during the year are 10,000, and the total expected number of inspections is 1,500.
Required:
 a.
Compute the total cost of the potential job using direct labour hours to assign overhead.
Also determine the bid price for the potential job.
b.
Compute the total cost of the job using activity-based costing and the appropriate cost drivers.
Also determine the bid price if activity-based costing is used.
c.
Prepare a memorandum to the plant manager recommending a bid price for the potential job. Support your recommendation by explaining which method best reflects the actual cost of the job.
Total expected machine hours for all jobs during the year are 10,000, and the total expected number of inspections is 1,500.
Required:
a.
Compute the total cost of the potential job using direct labour hours to assign overhead.
Also determine the bid price for the potential job.
b.
Compute the total cost of the job using activity-based costing and the appropriate cost drivers.
Also determine the bid price if activity-based costing is used.
c.
Prepare a memorandum to the plant manager recommending a bid price for the potential job. Support your recommendation by explaining which method best reflects the actual cost of the job. (Essay)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)