



 Chat with AI
Exam 10: Deductions and Losses: Certain Itemized Deductions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Margaret, who is self-employed, paid $6,000 for medical insurance coverage.She can include the $6,000 when calculating her medical expense deduction.
(True/False)
4.9/5  (79)
(79) Joseph and Sandra, married taxpayers, took out a mortgage on their home for $350,000 in 1990.In May of this year, when the home had a fair market value of $450,000 and they owed $250,000 on the mortgage, they took out a home equity loan for $220,000.They used the funds to purchase a single engine airplane to be used for recreational travel purposes.What is the maximum amount of debt on which they can deduct home equity interest?
(Multiple Choice)
5.0/5 (92)
(92) Paul, a calendar year married taxpayer, files a joint return for 2012. Information for 2012 includes the following: 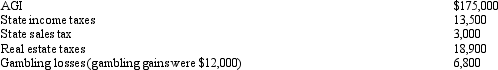 Paul's allowable itemized deductions for 2012 are:
 (Multiple Choice)
4.9/5 (88)
(88) During the year, Eve (a resident of Billings, Montana) spends three consecutive weeks in Louisville, Kentucky.One week is spent representing the Billings First Christian Church at the national convention, and two weeks are spent vacationing with relatives.One third of Eve's travel expenses will qualify as a charitable deduction.
(True/False)
5.0/5 (72)
(72) Interest paid or accrued during the tax year on aggregate acquisition indebtedness of $2 million or less ($1 million or less for married persons filing separate returns) is deductible as qualified residence interest.
(True/False)
4.8/5 (68)
(68) Linda borrowed $60,000 from her parents for a down payment on a condominium.She paid interest of $5,500 in 2010, $0 in 2011, and $9,000 in 2012.The IRS disallowed the deduction. Can you offer any explanation for the disallowance?
(Essay)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)