



 Chat with AI
Exam 16: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Gray Company, a calendar year taxpayer, allows customers to return defective merchandise for a full refund within 30 days of the purchase.In 2012, the company refunded $400,000 for claims involving sales.The $400,000 consisted of $350,000 in refunds from 2012 sales and $50,000 in refunds from 2011 sales.All of the refunds from 2011 sales were for claims filed in 2011 and were paid in January and February 2012.At the end of 2012, the company had $12,000 in refund claims for sales in 2012 for which payment had been approved.These claims were paid in January 2013.Also in January 2013, the company received an additional $30,000 in claims for sales in 2012.This $30,000 was paid by Gray in February 2013.With respect to the above, Gray can deduct:
(Multiple Choice)
4.9/5  (95)
(95) Karen, an accrual basis taxpayer, sold goods in December 2012 for $20,000.The customer was unable to pay cash.So the customer gave Karen a note for $20,000 that was payable in April 2013.The note bore interest at the Federal rate.The fair market value of the note at the end of 2012 was $18,000.Karen collected $20,500 from the customer in April 2013, $20,000 principal plus $500 interest. Under the accrual method, Karen must recognize income of:
(Multiple Choice)
4.7/5 (74)
(74) Gold Corporation, Silver Corporation, and Copper Corporation are equal partners in the GSC Partnership.The partners' tax year-ends are as follows: 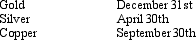
(Multiple Choice)
4.7/5 (86)
(86) Alice, Inc., is an S corporation that has been in business for five years.Its annual gross receipts have never exceeded $1 million. The corporation operates a retail store and also owns rental property.The sales from the retail store and the rental income may be reported by the cash method, unless Alice previously elected the accrual method.
(True/False)
4.9/5 (83)
(83) Which of the following must use the accrual method of accounting? 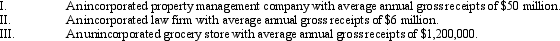
(Multiple Choice)
4.9/5 (84)
(84) When the IRS requires a taxpayer to change accounting methods:
(Multiple Choice)
5.0/5 (86)
(86) Which of the following statements regarding a 52-53 week tax year is correct?
(Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)