



 Chat with AI
Exam 19: Corporations: Distributions Not in Complete Liquidation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


A distribution in excess of E & P is treated as capital gain by shareholders.
(True/False)
4.8/5  (89)
(89) On January 2, 2012, Orange Corporation purchased equipment for $300,000 with an ADS recovery period of 10 years and a MACRS useful life of 7 years.Section 179 was not elected.MACRS depreciation properly claimed on the asset, including depreciation in the year of sale, totaled $79,605.The equipment was sold on July 1, 2013, for $290,000.As a result of the sale, the adjustment to taxable income needed to arrive at current E & P is:
(Multiple Choice)
4.8/5 (95)
(95) In applying the stock attribution rules to a stock redemption, stock owned by a shareholder who owns 65% of a corporation is deemed to be owned in full by the corporation.
(True/False)
4.8/5 (81)
(81) Timothy owns 100% of Forsythia Corporation's stock.Corporate employees and annual salaries include Timothy ($300,000); Richard, Timothy's son ($80,000); Rita, Timothy's daughter ($100,000); and Sandy ($120,000).The operation of Forsythia Corporation is shared about equally between Timothy and Sandy (an unrelated party).Richard and Rita are full-time college students at a university about 150 miles away.Forsythia Corporation has substantial E & P but has not distributed a dividend for the past five years.Discuss problems related to the salary arrangement for Forsythia Corporation.
(Essay)
4.9/5 (71)
(71) Five years ago, Eleanor transferred property she had used in her sole proprietorship to Blue Corporation for 1,000 shares of Blue Corporation in a transaction that qualified under § 351.The assets had a tax basis to her of $100,000 and a fair market value of $270,000 on the date of the transfer.In the current year, Blue Corporation (E & P of $800,000) redeems 250 shares from Eleanor for $220,000 in a transaction that does not qualify for sale or exchange treatment.With respect to the redemption, Eleanor will have a:
(Multiple Choice)
4.9/5 (88)
(88) A corporation that distributes a property dividend must reduce its E & P by the adjusted basis of the property less any liability on the property.
(True/False)
4.8/5 (80)
(80) Grackle Corporation (E & P of $600,000) distributes cash of $200,000 and land (fair market value of $400,000; basis of $250,000) to a shareholder in a qualifying stock redemption. The land distributed is subject to a mortgage of $460,000. Grackle will recognize a gain of $150,000 as a result of the distribution.
(True/False)
4.8/5 (82)
(82) In the current year, Loon Corporation made a distribution in redemption of some of its shares.Loon incurred expenditures in connection with the redemption totaling $35,000 (accounting fees of $9,000, legal fees of $20,000, and brokerage fees of $6,000).The distribution was a qualifying stock redemption.How much of the $35,000 is deductible in the current year?
(Multiple Choice)
4.8/5 (80)
(80) Pheasant Corporation, a calendar year taxpayer, has $400,000 of current E & P and a deficit in accumulated E & P of $180,000.If Pheasant pays a $600,000 distribution to its shareholders on July 1, how much dividend income do the shareholders report?
(Multiple Choice)
4.8/5 (85)
(85) At the time of her death, Janice owned (in terms of the value of the stock outstanding) the following stock: 18% of Heron Corporation and 21% of Hawk Corporation. The value of these stocks is included in Janice's gross estate. For purposes of applying the 35% of the value of adjusted gross estate requirement under § 303 (i.e., redemption to pay death taxes), the Heron and Hawk stocks are aggregated.
(True/False)
4.8/5 (83)
(83) The adjusted gross estate of Debra, decedent, is $8 million.Debra's estate will incur death taxes and funeral and administration expenses of $1 million.Debra's gross estate includes stock in Silver Corporation that she had purchased twelve years ago for $600,000 (date of death fair market value of $3 million).At the time of her death in 2012, Debra owned 80% of the stock in Silver Corporation.Silver Corporation (E & P of $4 million) redeems all of the estate's stock in the corporation for $3 million.Debra's will names her daughter, Dena, who owns the remaining 20% interest in Silver Corporation, as her sole heir.With respect to this redemption, Debra's estate has the following income:
(Multiple Choice)
4.7/5 (69)
(69) Tangelo Corporation has an August 31 year-end.Tangelo had $50,000 in accumulated E & P at the beginning of its 2012 fiscal year (September 1, 2011) and during the year, it incurred a $75,000 operating loss.It also distributed $65,000 to its sole shareholder, Cass, on November 30, 2011.If Cass is a calendar year taxpayer, how should she treat the distribution when she files her 2011 income tax return (assuming the return is filed by April 15, 2012)?
(Multiple Choice)
4.7/5 (70)
(70) Ivory Corporation (E & P of $650,000) has 1,000 shares of common stock outstanding owned by unrelated parties as follows: Veronica, 500 shares, and Tommie, 500 shares. Veronica and Tommie each paid $125 per share for the Ivory stock 12 years ago.In May of the current year, Ivory distributes securities held as an investment (basis of $140,000, fair market value of $250,000) to Veronica in redemption of 200 of her shares.
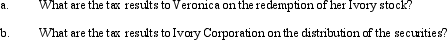
(Essay)
4.9/5 (78)
(78) Yolanda owns 60% of the outstanding stock of Amber Corporation. In a qualifying stock redemption, Amber distributes $20,000 to Yolanda in exchange for one-half of her shares (basis of $35,000). As a result of the redemption, Yolanda has a recognized capital loss of $15,000.
(True/False)
4.9/5 (69)
(69) The dividends received deduction is added back to taxable income to determine E & P.
(True/False)
4.9/5 (86)
(86) When computing E & P, taxable income is not adjusted for additional first-year depreciation.
(True/False)
4.7/5 (72)
(72) Corporate shareholders generally receive less favorable tax treatment from a qualifying stock redemption than from a dividend distribution.
(True/False)
4.7/5 (73)
(73) Scarlet Corporation is an accrual basis, calendar year corporation.Scarlet distributes inventory (basis of $20,000; fair market value of $40,000) to Frank, its shareholder.Assuming that Scarlet has $500,000 of current E & P, what is the impact of the distribution on Scarlet Corporation and on Frank?
(Essay)
5.0/5 (68)
(68) Cash distributions received from a corporation with a positive balance in accumulated E & P at the beginning of the year will be taxed as dividend income.
(True/False)
4.9/5 (77)
(77) Constructive dividends do not need to satisfy the legal requirements for a dividend as set forth by applicable state law.
(True/False)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)