



 Chat with AI
Exam 25: Taxation of International Transactions

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


Which of the following determinations does not require knowing the amounts of one's U.S.- versus foreign-source income?
(Multiple Choice)
4.8/5  (73)
(73) Income tax treaties may provide for either higher or lower withholding tax rates on interest income than the rate provided under U.S.statutory law.
(True/False)
4.8/5 (76)
(76) The IRS can use § 482 reallocations to assure that transactions between related parties are properly reflected in a tax return.
(True/False)
4.8/5 (91)
(91) Xenia, Inc., a U.S.shareholder, owns 100% of Fredonia, a CFC.Xenia receives a $3 million cash distribution from Fredonia.Fredonia's E & P is composed of the following amounts. 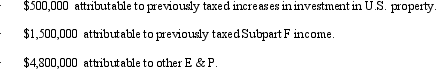 Xenia recognizes a taxable dividend of:
 (Multiple Choice)
4.8/5 (82)
(82) In 2013, George renounces his U.S.citizenship and moves to Fredonia, where income tax rates are very low. George is a multimillionaire and says he "has had it" with high Federal income taxes on wealthy individuals like himself. In 2016, George's U.S.-source income is $1.5 million. That income escapes Federal income taxes.
(True/False)
4.8/5 (78)
(78) ForCo, a subsidiary of a U.S.corporation incorporated in Belgium, manufactures widgets in Belgium and sells the widgets to its 100%-owned subsidiary in Germany.The income from the sale of widgets is not Subpart F foreign base company sales income.
(True/False)
4.9/5 (80)
(80) Abbott, Inc., a domestic corporation, reports worldwide taxable income of $8 million, including a $900,000 dividend from ForCo, a wholly-owned foreign corporation.ForCo's undistributed E & P are $18 million and it has paid $12 million of foreign income taxes attributable to these earnings.What is Abbott's deemed paid foreign tax credit related to the dividend received (before consideration of any limitation)?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following is not a specific separate income "basket" for purposes of the foreign tax credit limitation calculation?
(Multiple Choice)
4.8/5 (96)
(96) The U.S.system for taxing income earned outside its borders by U.S.persons is referred to as the territorial approach, because only income earned within the U.S.border is subject to taxation.
(True/False)
4.9/5 (76)
(76) Liang, an NRA, is sent to the United States by Fuller Corporation, her foreign employer.She spends 50 days in the United States and earns $15,000 for a two-month period.This amount is attributable to 40 U.S.working days and 10 foreign working days.Her employer does not have a U.S.trade or business and Liang spends no other time in the U.S.for the tax year.Liang's U.S.-source taxable income is:
(Multiple Choice)
4.8/5 (72)
(72) SunCo, a domestic corporation, owns a number of patents related to designing sunglasses.SunCo licenses these patents to unrelated parties.SpainCo, a Spanish corporation, paid SunCo $78,000 in royalties related to these licenses.SpainCo uses the patent information in its manufacturing process in its Texas plant.WiscCo, a domestic corporation, paid SunCo $32,000 in royalties related to the licenses.WiscCo uses the patent information in its manufacturing process in its Germany manufacturing plant.How much U.S.-source royalty income did SunCo earn from these licenses?
(Multiple Choice)
4.7/5 (78)
(78) With respect to income generated by non-U.S.persons, does the U.S.apply a "worldwide" or a "territorial" approach. Be specific.
(Essay)
4.8/5 (84)
(84) Arendt, Inc., a domestic corporation, purchases a piece of equipment for use in its manufacture of custom pianos.The equipment is acquired in Ireland at a cost of 200,000 euros when 1 euro: $1.35.Payment is due in 90 days.Arendt acquires 200,000 euros and pays for the machine when 1 euro: $1.15.What is the basis of the asset to Arendt and what is the foreign currency exchange gain or loss, if any?
(Essay)
4.8/5 (78)
(78) Shannon, a foreign person with a green card, spends the following days in the United States. 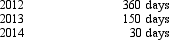 Shannon's residency status for 2014 is:
 (Multiple Choice)
4.7/5 (80)
(80) Your client holds foreign tax credit (FTC) carryforwards, i.e., it is in an "excess credit" position. Give at least three planning ideas that the client should implement, so as to free up the suspended FTCs.
(Essay)
4.9/5 (89)
(89) The purpose of the transfer pricing rules is to ensure that taxpayers have ultimate flexibility in shifting profits between related entities.
(True/False)
4.7/5 (78)
(78) Ridge, Inc., a domestic corporation, reports worldwide taxable income of $800,000, including a $300,000 dividend from Emma, Inc., a foreign corporation.Ridge's U.S.tax liability before FTC is $280,000.Ridge owns 20% of Emma.Emma's E & P after taxes is $8 million and it has paid foreign taxes of $4 million attributable to that E & P.If Ridge elects the FTC, its U.S.gross income with regard to the dividend from Emma is:
(Multiple Choice)
4.8/5 (89)
(89) ForCo, a foreign corporation, purchases widgets from USCo, Inc., its U.S.parent corporation.The widgets are sold by ForCo to another unrelated foreign corporation in the same country as ForCo.The income from sale of the widgets by ForCo is not Subpart F foreign base company sales income.
(True/False)
5.0/5 (97)
(97) The "residence of seller" rule is used in determining the sourcing of all gross income and deductions of a U.S.multinational business.
(True/False)
4.9/5 (79)
(79) USCo, a domestic corporation, receives $700,000 of foreign-source passive income on which foreign taxes of $70,000 are withheld.Its worldwide taxable income is $1,500,000 and its U.S.tax liability before the foreign tax credit is $525,000.What is USCo's allowed foreign tax credit?
(Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)